Summary
Summary
- Every fact in a Deal Intelligence report must trace to a document any reader can open independently.
- Sources are ranked in three tiers, with exchange filings and issuer announcements sitting at the top.
- AI monitoring flags public announcements for the desk but is never itself treated as a source or cited.
- Arithmetic on public figures is permitted but must be labelled as such, not presented as a disclosed price.
01 · Methodology
If a reader cannot open the document, it is not a Deal Intelligence fact. Monitoring is not a source. Private files are out of scope.
Published 16 Sep 2026 · Updated 22 Sep 2026 · Method changes only
Deal Intelligence is not investment, legal, tax or accounting advice. Every material fact is taken from documents that are already public, or from arithmetic on those documents. Read the independence and disclaimer before you treat a number as something you can act on.
Deal Intelligence is a public-record product. If a fact cannot be pointed at a document a reader can open, it does not belong in the article as a fact. This page is the hierarchy, the ledger rules, and the list of things the desk will not touch.
Acquiry does not use material non-public information in Deal Intelligence. It does not use data rooms, mandate files, unpublished models, or private management conversations as sources for these reports. Advisory work and the research desk are separate. If that ever failed on a specific article, the article would have to say so. Silence means the page was built from public documents.
02 · Methodology
Source hierarchy
Prefer the closest primary document. Do not cite an aggregator when the issuer filing or announcement exists.
| Tier | What counts | How it is labelled |
|---|---|---|
| 1 · Primary | Exchange filings (SEC, SEDAR+, ASX, Companies House packages that are actually filed), merger agreements and scheme booklets, issuer IR announcements, official buyer or target press releases on their own domains, earnings releases, audited reports, licence registers, court or regulator decisions | Public record / disclosed |
| 2 · Highly credible secondary | Reuters, Financial Times, Wall Street Journal, Bloomberg, specialist institutional trade press quoting or circulating a primary document | Reported. Used to confirm circulation, not to replace the filing |
| 3 · Supporting | Named interviews already on the record, industry databases, adviser announcements, product documentation the companies publish for customers | Named, and never presented as a disclosure of deal terms |
A trade article that says "people familiar with the matter" is not Tier 1. It can be mentioned as reported colour only when the desk is explicit that it is reported, and it cannot carry a price, a close date, or a stake percentage that the issuer has not published.
03 · Methodology
The source ledger
Each report ends with a numbered ledger. Non-editorial rows outbound to the real press release, IR page, regulator file, or trade URL. They never outbound to acquiry.com pretending to be the document. Related reading, which is a different module, links other Deal Intelligence articles.
Body copy uses superscript citations that jump to the ledger. The lead does not hyperlink "the company announcement" or "Reuters reported". That pattern reads like a generated summary of other people's links. The document is in the ledger. The sentence in the article should still make sense if the reader never clicks.
04 · Methodology
Language, translation, and excerpts
Many digital deals file first in French, German, Korean, Japanese or Spanish. The desk reads those filings. English in the article is Acquiry's, except where a phrase is a defined term that should stay in the original (a French offre publique, a Korean disclosure form code, an ASX ticker). We do not pretend a machine translation is the official English version. Where an issuer later files an official English translation, that file joins the ledger and can replace an earlier reading if it differs.
Quoted phrases are short. Long paste-ups of a filing belong in the filing.
05 · Methodology
What we will not use
- Material non-public information, whether it arrived through a mandate, a friend, or a misplaced email.
- Hack dumps, stolen files, or screenshots of systems the public cannot access.
- Unnamed Slack screenshots and "a source told us" economics.
- Paywalled body text we cannot show a reader how to verify. The public headline and the issuer document are enough.
- Competitor gossip offered as a multiple.
- Acquiry's own unpublished workpapers from a live mandate about the same parties.
06 · Methodology
What "AI-driven" means on this desk
AI-driven technology is used to watch and cluster public announcements so the desk does not miss a filing at 6am. It is not a source. It is not a witness. It does not become a row in the ledger. If a number appears in an article, it came from a document or from arithmetic on documents, and the ledger or the calculation note will show which.
Monitoring can be wrong in the usual ways: a headline that is not a deal, two companies with similar names, a "talks" story with no agreement. Editorial reading of the actual file is the gate. That is why rights deals and property headlines get skipped even when they trend.
07 · Methodology
Worked examples
Merkur / Société Française de Casinos. The public facts are the 17 September 2026 SPA, 95 percent of Casigrangi, 81.21 percent of SFC already held by that vehicle, a transparency price of €6.19 a share, and a Q1 2027 Interior close target. Those go in as disclosed. A reverse-engineered Casigrangi enterprise value does not, because the issuer did not publish one.
Telix / ITM. The cash-free, debt-free upfront of US$1.65 billion, the share mix, and the contingent ITM-11 milestones are in the announcement. Adding the contingent pot to the upfront and printing a single "headline value" as if it were a cheque written today is arithmetic, and it is labelled that way. It is not a disclosed purchase price.
08 · Methodology
What this means for buyers and sellers
For buyers
- Any figure cited in a Deal Intelligence report can be traced to a public document, so buyers can verify the underlying source directly without relying on Acquiry's interpretation.
- Contingent consideration is reported separately from upfront values, giving buyers a clearer view of what is contractually committed versus what remains conditional.
- Reported colour from unnamed sources is flagged explicitly and cannot carry price, close date or stake figures, reducing the risk of acting on unverified deal economics.
For sellers
- Only information the seller has already published can appear as a fact, so Deal Intelligence coverage does not risk exposing confidential terms that remain inside a data room.
- Sellers can identify exactly which of their public filings or announcements have been cited by checking the numbered source ledger at the end of each report.
- Where filings are made in languages other than English, the desk reads those documents directly and notes when an official English translation supersedes an earlier reading.
09 · Methodology
Work with Acquiry
Acquiry runs buy-side and sell-side mandates for digital businesses. We are not limited to the sectors or markets covered here: any sector, any market, bring it to us anyway. Start a mandate (opens in a new tab).
Reference
Frequently asked questions
What sources does Acquiry use for Deal Intelligence reports?
Acquiry uses only public documents, ranked across three tiers. Tier 1 covers exchange filings, merger agreements, issuer press releases and audited reports. Tier 2 covers credible outlets such as Reuters and the Financial Times when they circulate a primary document. Tier 3 covers named interviews, industry databases and company-published product documentation.
Does Acquiry use data rooms or private management conversations in its research?
No. Acquiry does not use material non-public information, data rooms, mandate files, unpublished models or private management conversations as sources for Deal Intelligence reports. Advisory work and the research desk are kept separate.
How does Acquiry handle deal values that include contingent payments?
Contingent amounts are reported separately from the upfront consideration. Adding a contingent pot to an upfront figure and presenting the total as a single headline value is treated as arithmetic, labelled accordingly, and is not described as a disclosed purchase price.
What role does AI play in producing Deal Intelligence articles?
AI-driven technology is used to monitor and cluster public announcements so the desk does not miss a filing. It is not treated as a source, is not cited in the ledger, and every number in an article must still trace to a document or to arithmetic on documents.
Keep reading
Related analysis
Methodology · Research
Independence and disclaimer
Deal Intelligence is not investment, legal or tax advice. It uses public sources only, sits apart from Acquiry mandates, and corrects in place.
Methodology · Research
How numbers are labelled
Disclosed, calculated, analysis and undisclosed labels. No invented enterprise values. Non-GAAP keeps the issuer's definition.
Methodology · Gaming
How Acquiry Deal Intelligence works
How Acquiry's Deal Intelligence desk chooses deals, reads public filings, labels numbers, and stays independent of advice and mandates.
About the analyst
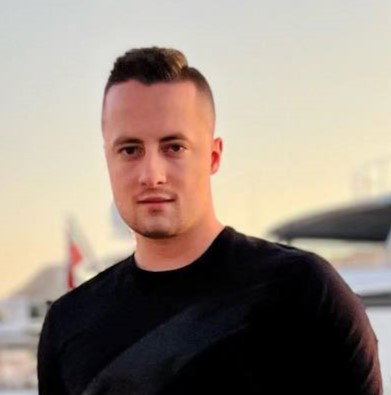
Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.