
01 · Deal Intelligence
01 · Transaction
02 · Deal Intelligence
What osapiens is buying
osapiens bought the Nasdaq Metrio platform and its customers: a reporting and carbon-accounting engine, not Nasdaq itself. The transfer completed on 19 August 2026.
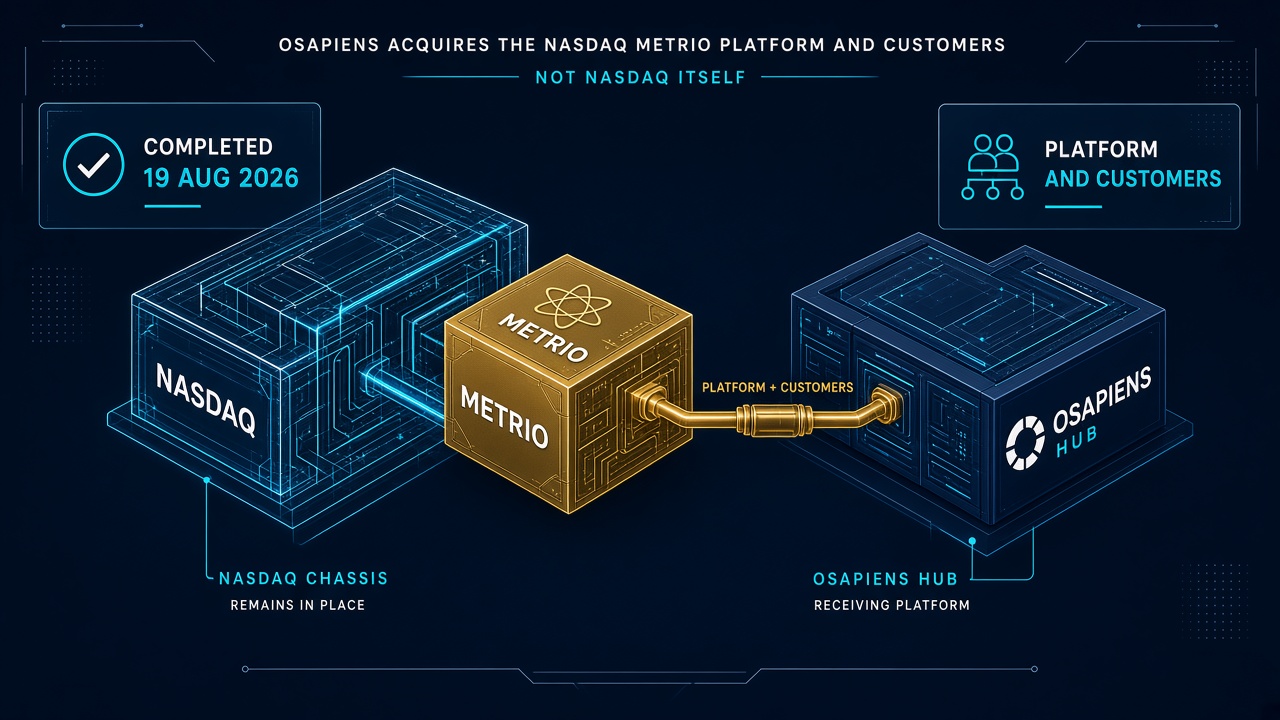
The 19 August osapiens release is specific about the industrial object. Metrio is software for collecting, validating and reporting ESG and greenhouse-gas data. Non-financial reporting and carbon accounting already sit inside the osapiens HUB, through the disclosures and reporting suite and the carbon-accounting suite. What Metrio adds is proven enterprise depth in both, with audit-grade data management designed to keep disclosures current as rules change.
Nasdaq product materials list the working parts of that engine: guided workflows for CSRD, TCFD, California climate laws and ISSB; supplier campaigns; Scope 1, 2 and 3 accounting; more than 42,000 emission factors; and activity logs built for audit. Those are product claims about the system now sitting inside osapiens. They are not a census of the accounts that moved on 19 August.
osapiens describes itself as an AI platform for compliance and supplier intelligence. The HUB pitch is a single sentence worth keeping: verify products, know suppliers, trace goods, own the footprint, and report with confidence, on one platform. Metrio is the reporting-and-carbon end of that sentence. It is not a new supplier-intelligence product. It is the system of record osapiens can now take into North American accounts it did not already own at this depth.
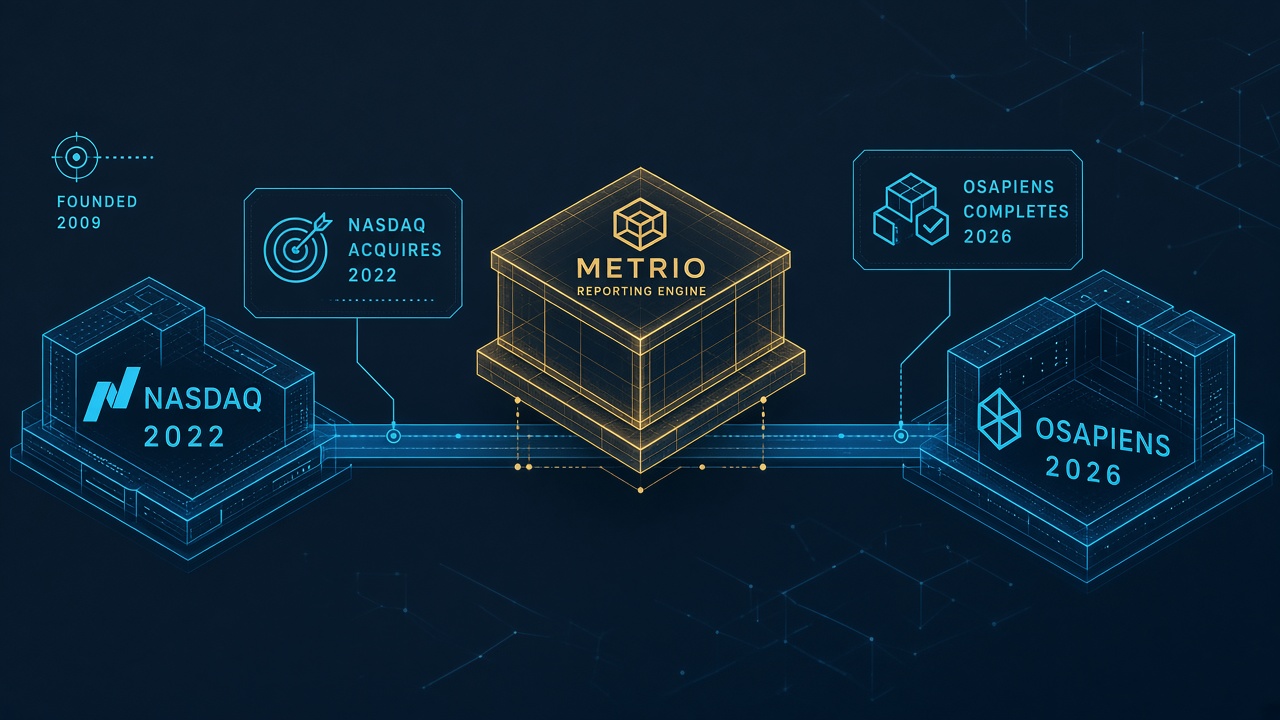
The engine has already changed owners once. On 2 June 2022 Nasdaq, Inc. agreed to acquire Metrio, then a privately held Montreal SaaS business founded in 2009, and said it would keep the headquarters in Montreal. Nasdaq described a CSR reporting platform that had helped more than 5,000 users at more than 100 global companies, and listed B Corp certification, SASB Alliance membership, a United Nations Global Compact signature and CDP accredited-supplier status. Those figures and credentials are 2022 facts. They are not the transferred-customer count for 2026.
Trade press around that first sale named a Canadian-weighted book. BetaKit, covering the 2022 agreement, listed Air Canada, Bell, BMO, Cogeco, Desjardins, Hydro-Québec, Loblaw, RBC and TMX among Metrio's then customers, and named co-founders Patrick Elie and Pierre-Alexandre Hurtubise. Treat that list as 2022 reporting, not as a 2026 completion schedule. ESG Today, writing on the 2026 sale, dates osapiens to 2018 and says Nasdaq relaunched the product as Nasdaq Metrio in 2023 after the 2022 close.
02 · Parties
03 · Deal Intelligence
Who sat on the transaction
A public-company seller, a privately held German software buyer, three named advisers, and a completed close on 19 August 2026.
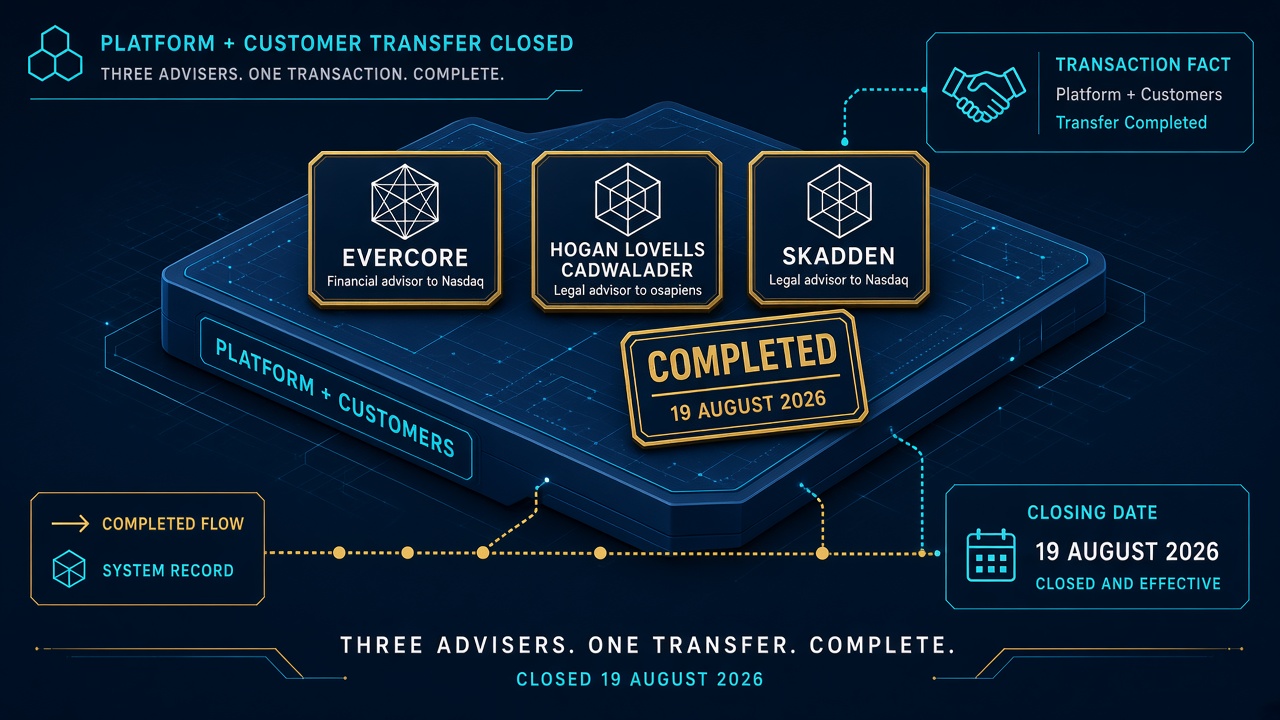
The announcement names osapiens as the acquirer and Nasdaq, Inc. as the seller. MarketScreener, reporting the same day, names the buying entity as Osapiens Services GmbH. Keep both on the page. The group is the Mannheim software company. Services GmbH is the vehicle a deal database attached to the close. Michael Bartels, SVP, Capital Access Platforms, is the named Nasdaq spokesperson. Matthias Jungblut, Co-CEO, speaks for osapiens. Alberto Zamora, the other Co-CEO and co-founder, is the voice on the March Series C, not on this close.
Adviser quality is part of the public record on a listed-company disposal. Evercore ran the sell-side. Hogan Lovells Cadwalader International LLP ran buyer legal. Skadden ran seller legal. That is a full-dress roster for a platform-and-customer carve-out, even when the cheque stays private. It also tells you Nasdaq treated Metrio as a real product line, not a leftover module deleted in a footnote.
Bartels' quote is the seller thesis in two sentences. Metrio, he said, has become a leader for non-financial reporting and carbon accounting in North America. osapiens is the partner that will keep serving those customers with the strategic focus the product needs. The sale lets Nasdaq concentrate on investor relations and governance solutions "in which we have unique expertise" for listed and corporate clients. That is a public-company product-portfolio decision: keep IR and governance, move sustainability reporting to a specialist.
The dateline is New York and Mannheim. osapiens already had U.S. offices. The acquisition is not a first landing. It is a way to arrive with reference customers instead of a greenfield sales cycle. The majority of Metrio's enterprise customers, osapiens says, are in North America.
03 · Fit
04 · Deal Intelligence
Why the businesses fit
osapiens wants one data layer that feeds reporting, supplier intelligence and carbon accounting. Metrio is the North American reporting foothold that layer did not already own at this depth.
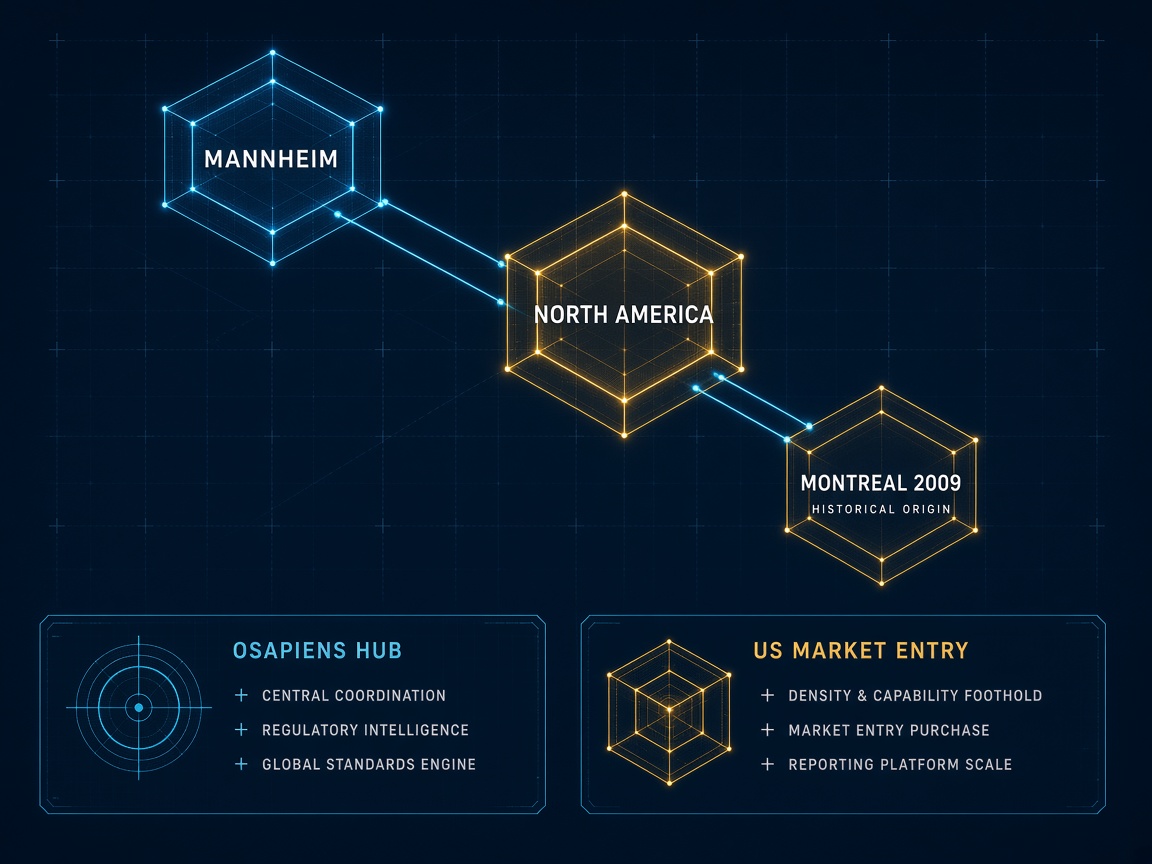
Jungblut did not hedge. "Very few acquisitions fit this precisely." More than 2,500 customers already run compliance processes and supplier intelligence on the osapiens HUB, with non-financial reporting and carbon accounting "centrally integrated." Metrio deepens those two functions and, in the same move, accelerates U.S. entry. That is a capability purchase and a distribution purchase glued together.
“With the acquisition of the Nasdaq Metrio platform and customers, we are now able to further deepen our functionalities to offer even greater value to our customers. At the same time, it allows us to accelerate our entry into the U.S. market.” Matthias Jungblut, Co-CEO, osapiens”
The architecture claim is collect once, reuse many times. Operational and supplier data gathered for a European product-compliance rule can, in that design, feed a North American climate disclosure, a carbon inventory and a supplier-intelligence workflow without a second campaign. osapiens says AI across the platform will raise automation, cut manual effort and lift supplier response rates by reducing duplicate requests. Those are management objectives. They are the reason the data layer is the fit, not a slide about "synergies."
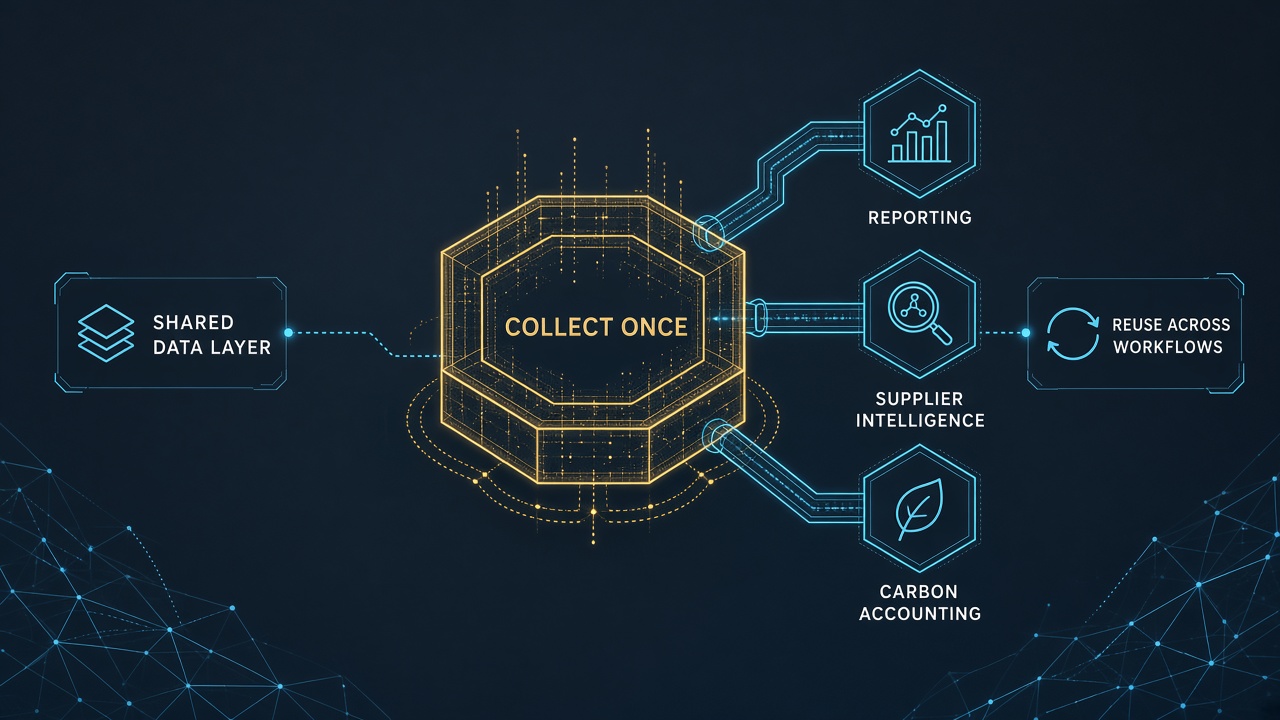
Nasdaq had combined Metrio with investor relations, ESG advisory, governance and corporate services. osapiens is pointing the same engine upstream into supplier intelligence, product compliance and supply-chain operations. The reporting category is similar. The commercial adjacency is not. One owner used Metrio as a capital-markets sustainability product. The new owner wants it as the disclosure layer on an operating-compliance hub.
That is also why the seller logic is clean. Nasdaq is not exiting data. It is choosing IR and governance as the products where it says it has unique expertise, and handing a specialist reporting engine to a buyer whose whole commercial motion is compliance software. Public-company product lines get carved this way when the adjacency inside the seller is weaker than the adjacency inside the buyer.
04 · Product
05 · Deal Intelligence
How the product stacks sit together
Metrio docks into two of seven osapiens suites, disclosures and reporting plus carbon accounting, on a hub that already runs more than 25 solutions.
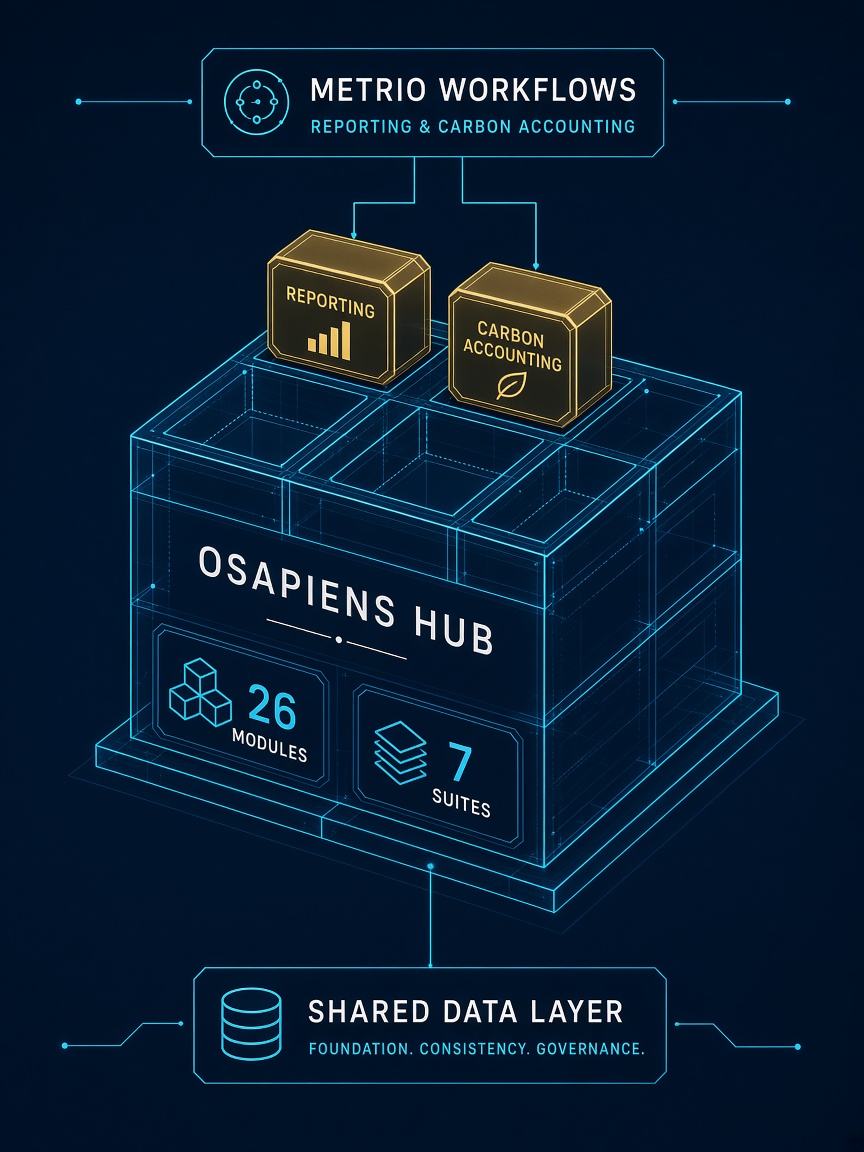
The HUB is a multi-tenant platform built for cross-company collaboration and AI automation. osapiens groups more than 25 solutions into seven suites that cover supplier relationships, compliance, global supply chains, maintenance, service and distribution. The announcement is explicit that Metrio's two strengths, enterprise non-financial reporting and carbon accounting, already have named homes on that hub.
A reporting platform is embedded in year-on-year data, calculation methodologies, framework mappings and audit evidence. The commercial value is the reliability of those longitudinal records as much as the application features. osapiens has a stated architectural answer: a common backbone. The integration still has to prove that the shared layer keeps customer-specific controls, lineage, permissions and historical comparability.
Low-friction path: Metrio stays the reporting system of record while osapiens layers shared supplier and compliance services beneath it, and customers take new modules only where a workflow gain is visible. High-friction path: forced replatforming turns the book into a migration cohort. The difference is data continuity, not a feature checklist.
The rest of the hub is the attach surface. Product compliance, supplier intelligence and traceability sit beside the two suites Metrio deepens. That is how a North American reporting account becomes a candidate for European-style supplier due diligence, and how an existing osapiens manufacturing account gets a climate-disclosure engine that already speaks California, CDP and ISSB.
Capability map
| Capability | osapiens before | Metrio adds | Together |
|---|---|---|---|
| Reporting | Disclosures and reporting suite on the HUB | Enterprise non-financial reporting, audit-grade trails | Deeper system of record, same data layer |
| Carbon | Carbon-accounting suite | Scope 1, 2 and 3 workflows, 42,000+ emission factors | Inventory plus disclosure in one ownership |
| Frameworks | European product, supplier and sustainability rules | California climate laws, CDP, GRI, IFRS, SASB, CSRD, TCFD, ISSB | Cross-Atlantic disclosure coverage |
| Supplier layer | Supplier intelligence and traceability | Supplier campaigns inside the reporting engine | One collection campaign, two uses |
| Geography | Mannheim HQ, Europe and U.S. offices, 650+ staff | Majority of enterprise customers in North America | U.S. entry with local references |
| Distribution | 2,500+ HUB customers worldwide | Transferred Metrio customer base | Two books on one hub, if continuity holds |
05 · Numbers
06 · Deal Intelligence
What the published numbers and capital history say
osapiens publishes 2,500-plus customers, more than 25 HUB solutions, 650-plus employees, and three equity rounds totalling US$247 million of disclosed primary capital. Metrio's 2022 user counts stay labelled historical.
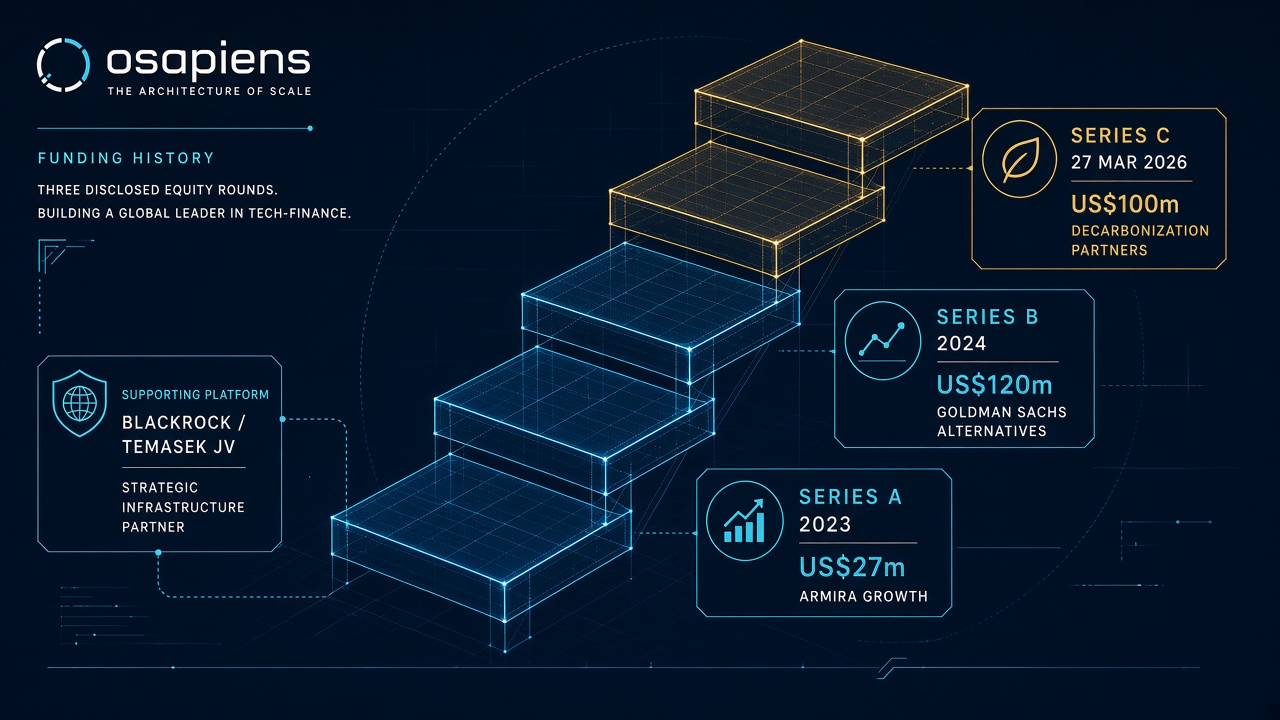
Add the three disclosed rounds and you get US$247 million of named primary capital (US$27m + US$120m + US$100m). That sum is an Acquiry arithmetic check on company figures, not a post-money valuation and not a sources-and-uses table for Metrio. The 27 March 2026 Series C was led by Decarbonization Partners, a BlackRock and Temasek joint venture, and was still subject to regulatory approvals at announcement. Existing investors Goldman Sachs Alternatives and Armira Growth remained on the register. Decarbonization Partners itself has US$1.40 billion of capital from more than 30 institutions. osapiens said the new money would accelerate product innovation and international-market growth. It did not say the money would buy Metrio.
| Round | Date | Amount | Lead |
|---|---|---|---|
| Series A | 2023 | US$27m | Armira Growth |
| Series B | 2024 | US$120m | Goldman Sachs Alternatives |
| Series C | 27 March 2026 | US$100m | Decarbonization Partners |
| Named primary capital | Acquiry sum | US$247m | Three disclosed rounds, not a valuation |
Operating scale sits on the same page as capital, and should stay separate from it. More than 2,500 customers worldwide, from SMEs to global enterprises. More than 25 solutions on a multi-tenant hub. An international team of over 650, headquartered in Mannheim, with offices across Europe and the United States. Nasdaq's 2022 Metrio announcement cited more than 5,000 users and more than 100 companies. Customer count, historic user count, module count and headcount are capability signals. They are not ARR, gross retention or EBITDA.
Demand context is regulatory complexity, not a guaranteed sales cycle. In March 2024 the U.S. Securities and Exchange Commission adopted climate-related disclosure rules, including material climate-risk requirements and, for certain filers, material Scope 1 and Scope 2 emissions. The practical setting remains jurisdictional. Metrio's product list includes California climate laws, CDP, GRI, IFRS and SASB. osapiens positions its HUB around European product, supplier and sustainability rules. That is a cross-Atlantic product story and a policy-maintenance obligation at the same time.
Durable revenue still has to come from recurring workflow value: less duplicate data collection, faster assurance, a reporting calendar that does not reset every ownership change. Regulation can be a catalyst. It is not the whole commercial case. Co-founder Alberto Zamora, on the Series C, framed the investor thesis as sustainable growth plus AI-driven efficiency. Jungblut, on this close, framed the operating thesis as deeper reporting plus a faster U.S. entry. Those two sentences are how the capital and the acquisition are supposed to talk to each other.
06 · Distribution
07 · Deal Intelligence
Where osapiens can put Metrio
Distribution runs both ways. Metrio gives osapiens North American enterprise references. The HUB gives those accounts supplier intelligence, product compliance and a European rule library they did not buy from Nasdaq.
osapiens already had U.S. offices and 650-plus people. What it did not have, on its own account, was a majority-North-American enterprise reporting book with local reference customers. Jungblut's U.S. market-entry line is that gap. Bartels' line is the other side of it: Metrio customers stay on a platform whose owner is in the reporting business as a primary motion, not as an IR adjacent.
The attach into existing osapiens accounts is the quieter half. A manufacturer already running supplier due diligence on the HUB still has to produce CSRD, ISSB or California filings. Metrio is the engine that can take the same collected data and turn it into a disclosure pack. That is the collect-once claim, expressed as a sales motion rather than an architecture diagram.
The 2022 Canadian names are a reminder that Metrio's original density was not "the United States" as an abstraction. Air Canada, Bell, BMO, RBC, TMX and Hydro-Québec were the kinds of accounts Nasdaq bought. Whether any of those relationships still sit in the 2026 transferred book is not something this article will guess. The distribution job in 2026 is the North American majority osapiens did disclose, plus 2,500-plus HUB customers that can now be offered a deeper reporting stack.
07 · Close
08 · Deal Intelligence
How the combination could work
Close is already done. The operating sequence is then stabilise the customer perimeter, validate controls and historical records, and attach shared workflows only where they remove work.
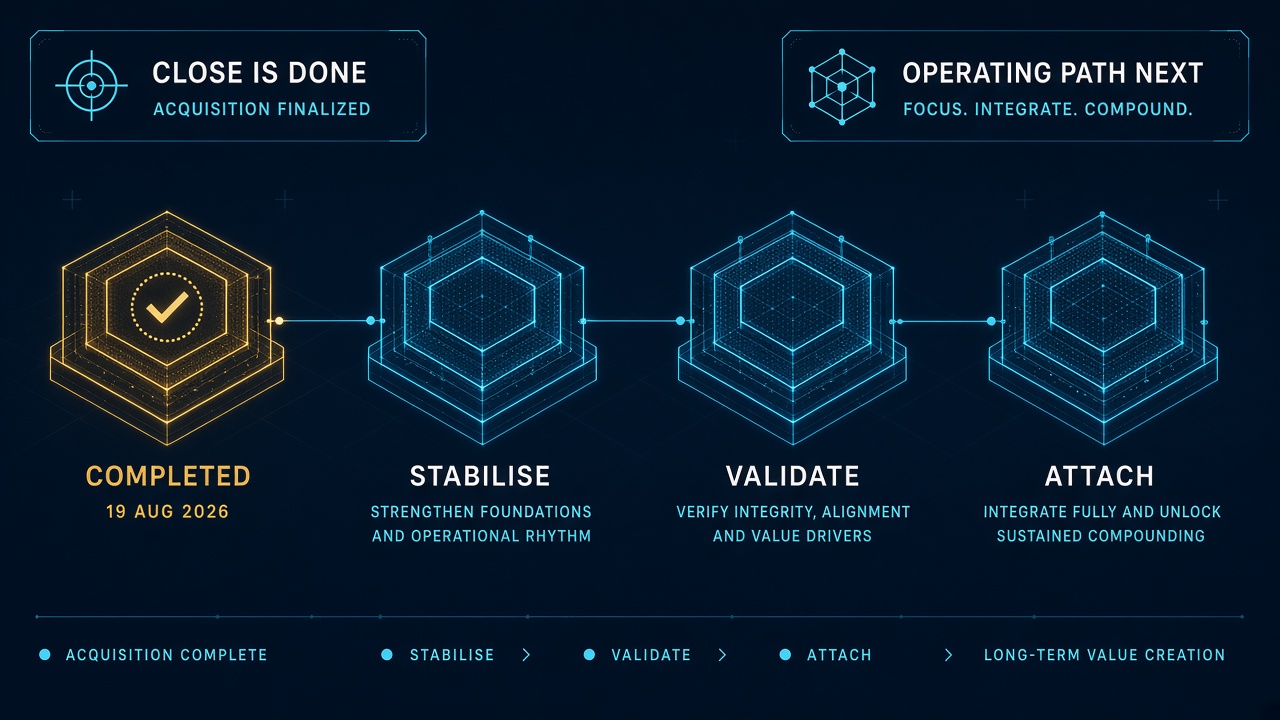
Reporting software punishes a Day-1 app merge. Confirm contracts, support pathways, account owners and renewal timing first. Then map data sources, calculation methods, role permissions, audit logs and framework mappings so the reporting lineage stays verifiable. Only then state which Metrio capabilities stay native, which connect to the HUB, and where a later migration would even be allowed. osapiens already has U.S. offices and a 650-person bench. The operating question is whether that bench is pointed at implementation and content maintenance in the foothold market, not whether a first office has to be opened.
Value then follows a simple order. Retention through the next assurance cycle. Cross-sell of supplier intelligence and compliance workflows into transferred accounts, and reporting depth into existing osapiens accounts, only after that. Workflow efficiency last, measured as fewer duplicate requests and shorter cycle time. If the book does not renew, the other two levers do not get a chance.
- Customer continuityFirst cycle. Contracts, support, data hosting and reporting-calendar timing through the next assurance window.
- Product architectureConnected services. Shared data layer under a native Metrio system of record, rather than a forced replatform.
- U.S. operating capacityLocal build. Sales, implementation, support and regulatory-content investment against the North American book.
- Attach after retentionSecond motion. Supplier-intelligence and product-compliance attach into transferred accounts; reporting depth into the 2,500-plus HUB base.
- Rule maintenanceOngoing. California, CSRD, ISSB, CDP and GRI mappings have to stay current on one backbone.
08 · View
09 · Deal Intelligence
Acquiry view
Acquiry view. osapiens bought a reporting system of record it can distribute through a compliance hub it already owns, and it bought it as a completed platform-and-customer transfer rather than a bid for Nasdaq. The fit is a North American foothold plus an engine that sits at the reporting end of a collect-once architecture. Evercore, Hogan Lovells and Skadden on the roster tell you Nasdaq treated the line as a real disposal. The economics stay off the page. The industrial logic does not.
The best companies are acquired, not sold. Nasdaq is concentrating on investor relations and governance. osapiens is identifying a specific capability, enterprise sustainability reporting with audit-grade data trails, and filling it inside a market it wants to enter faster than a greenfield sales build. If reporting continuity holds through the next assurance cycle, the customer base becomes a distribution surface. If migration becomes a reimplementation, the same base reads as a vendor change.
Sources
10 · Deal Intelligence
Sources and methodology
Primary company announcements rank above product pages, trade press and older Nasdaq filings. Historical 2022 user counts and named accounts stay labelled historical. The US$247 million capital sum is an Acquiry addition of three disclosed rounds.
- 1.01osapiens announcement, 19 August 2026 (opens in a new tab)Primary
- 2.02osapiens corporate site and product overview (opens in a new tab)Primary
- 3.03osapiens Series C announcement, 27 March 2026 (opens in a new tab)Primary
- 4.04Nasdaq to acquire Metrio, 2 June 2022 (opens in a new tab)Primary
- 5.05Nasdaq Metrio product page (opens in a new tab)Product
- 6.06Nasdaq sustainability products overview (opens in a new tab)Product
- 7.07SEC climate-related disclosure rules, 6 March 2024 (opens in a new tab)Regulator
- 8.08ESG Today, 19 August 2026 (opens in a new tab)Reported
- 9.09MarketScreener, 19 August 2026 (opens in a new tab)Reported
- 10.10Nasdaq IR, Metrio acquisition, 2 June 2022 (opens in a new tab)Primary
- 11.11BetaKit, 3 June 2022 (opens in a new tab)Reported
Method: Acquiry Deal Intelligence methodology. Acquiry was not engaged by any party. Nothing here is investment advice.
Keep reading
Related analysis
Deal Intelligence · SaaS
R1 Acquires Humata Health and Moves Prior Authorisation Into the Revenue-Cycle Operating System
Acquiry Deal Intelligence analysis of R1's acquisition of Humata Health, prior-authorisation automation for Phare OS. Terms undisclosed.
Deal Intelligence · SaaS
Bending Spoons puts $1.285bn on Airtable and turns its roll-up on enterprise software
Milan-listed Bending Spoons signed an all-cash definitive agreement for 100% of Airtable at $1.285 billion enterprise value. Equity value is roughly $2.25 billion once net cash is included, the roll-up's largest disclosed bet and first major workflow platform acquisition since listing on Nasdaq.
Deal Intelligence · SaaS
Francisco Partners puts ~$650m on Weave and takes healthcare's AI engagement platform private
Francisco Partners signed a definitive agreement on 18 August 2026 to acquire Weave Communications (NYSE: WEAV) at approximately $650 million aggregate equity value and $7.40 per share in cash. The ~34% premium take-private folds a 40,000-location AI patient engagement and payments platform into PE ownership with a Q4 2026 close target.
Explore the sector:SaaS acquisitions
About the analyst

Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.