
01 · Market Report
The biggest cheques went to firms that sell advice. AI deals were about infrastructure.
We only count a price when it appears in a filing or a company release we have actually read. On that basis, the quarter produced US$60.4bn of disclosed value across 9 deals, led by Aon’s US$17bn for USI. Reported figures, such as the US$7.5bn attached to Stripe and OpenRouter, are shown but kept out of the totals.
Every deal below has its own story, its own deal file with the exact wording of the source, and direct links to the filing. Read it end to end, or jump to the one you care about.
02 · Market Report
The quarter the brokers and accountants got bought
Three of the six largest disclosed deals we tracked were for firms that sell advice and distribution, not products. Insurance broking and accounting are fragmented, recurring and cash-generative, which makes them easy to finance at scale.
Aon writes a US$17bn cheque for USI and moves into the American middle market
The largest disclosed transaction in our Q3 sample, and the second time in three years Aon has paid more than US$10bn for a US broker.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Insurance broking | 31 August 2026 | US$17.0bn | Disclosed |
Aon disclosed a US$17.0bn cash payment for USI Insurance Services in an 8-K exhibit filed on 11 September (opens in a new tab). The figure includes repayment of USI’s debt, so it is closer to an enterprise value than an equity cheque. That matters when you compare it with the other deals in this report. It is not an overpayment on the equity.
USI serves commercial property and casualty, employee benefits and personal-risk clients across the United States. For Aon, whose core has long been large corporate and specialty risk, that is a distribution footprint it could not build organically at any reasonable speed. The deal follows Aon’s US$13.4bn purchase of NFP in 2024, which pointed the same way.
All-cash consideration at this size says two things. Aon is comfortable taking on leverage against broking cash flows. And the seller wanted certainty over a share-based structure. Both fit a market where broking assets have traded as quasi-infrastructure: recurring commission income, low capital intensity and pricing power that follows premium rates.
“Acquiry’s read This is a distribution deal wearing a broking badge. Aon is buying tens of thousands of mid-sized client relationships it can sell analytics, reinsurance and benefits consulting into.”
What to watch
- Antitrust review in US regional markets where both firms place commercial lines.
- Aon’s leverage guidance and whether it pauses buybacks to fund the payment.
- Producer retention. Mid-market broking value leaves the building with the people.
An 88% premium takes The Baldwin Group private
Sequence Holdings and DFO Management are paying US$32.50 a share for majority control. It is the richest premium we recorded all quarter.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Insurance distribution | 14 September 2026 | US$7.7bn | Disclosed |
The Baldwin announcement (opens in a new tab) sets the price at US$32.50 per share, an 88% premium to the unaffected close on 17 June. That reference date is nearly three months before signing. It tells you the shares had already moved on speculation, and that the board wanted credit for the full run-up.
The Tampa-based broker, which rebranded from BRP Group in 2024, built itself through a long run of acquisitions and embedded-insurance partnerships with homebuilders and lenders. Public markets never fully rewarded that model. Integration costs and earnout liabilities kept reported margins below the private-equity-owned peers Baldwin was competing with for deals.
A majority take-private removes the quarterly scrutiny and lets the buyers keep consolidating without explaining every adjusted-EBITDA bridge to the market. Read it next to Aon and USI: strategic buyers and private capital are chasing the same broking cash flows from opposite directions.
“Acquiry’s read An 88% premium is not a signal that Baldwin was cheap. It shows how much further private buyers will stretch for scaled US distribution than the public market would.”
- Whether a go-shop or competing bid emerges before the shareholder vote.
- How much of the existing management and founder equity rolls into the new structure.
Grant Thornton, backed by New Mountain, bids US$5bn for CBIZ
A private-equity-funded accounting firm buying a listed one. The roll-up of the US mid-tier accountancy market has reached the public companies.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Accounting and advisory | 29 July 2026 | US$5.0bn | Disclosed |
CBIZ’s filing (opens in a new tab) confirms a US$55.00 cash offer, about 54% above its 30-day volume-weighted average price, for a US$5bn enterprise value. The buyer is Grant Thornton Advisors, the US firm that took a majority investment from New Mountain Capital in 2024.
Two years ago this deal could not have happened. Partnership structures and independence rules kept outside capital away from audit firms. The fix was to split the advisory business from the attest practice, and that opened the door. CBIZ had already used the same logic to absorb Marcum in 2024, so Grant Thornton is buying a platform that has done this before.
The prize is scale in tax, advisory and outsourced finance for mid-market clients: annuity-like revenue with high retention. Pricing is the question. Private equity will need to raise utilisation and cross-sell without losing the partners who own the client relationships.
“Acquiry’s read Of every deal this quarter, this is the clearest proof that sponsors have found a way to own professional-services partnerships at listed-company scale.”
- Audit-independence carve-outs and whether regulators require any divestment.
- Partner attrition in the first two busy seasons after close.
03 · Market Report
Platforms buying reach, not technology
The two big platform deals of the quarter were about customers and geography. Neither Uber nor Grab needed new software. They wanted the markets and the credit books that come with them.
Uber goes for control of Delivery Hero at EUR 41.50 a share
A voluntary offer valuing the Berlin group at US$14.8bn, with Prosus’s irrevocable handing Uber about 53% before any other shareholder tenders.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Delivery and marketplaces | 16 July 2026 | US$14.8bn | Disclosed |
Uber’s 8-K exhibit (opens in a new tab) lays out a voluntary takeover offer at EUR 41.50 per share. That puts the equity value at US$14.8bn for 100%, or US$13.7bn once you strip out the stake Uber already owns. The decisive line is the irrevocable undertaking from Prosus, Delivery Hero’s largest shareholder, which takes Uber to about 53%.
That structure makes the offer effectively unlosable on control. Minority holders who don’t tender stay in a company that Uber runs and consolidates. The price only has to be good enough for Prosus, which has spent two years looking for a clean exit from its food-delivery holdings.
Strategically, it gives Uber scale in Asia, the Middle East and parts of Europe where Delivery Hero brands lead, all at once. It also brings antitrust exposure wherever the two already overlap. Expect remedy negotiations market by market, not a single clearance.
“Acquiry’s read The headline is US$14.8bn, but the real cheque is closer to Prosus’s block. Uber buys control first and can decide later whether it wants the rest.”
- Minimum acceptance conditions and whether Uber pursues a squeeze-out or delisting.
- Competition reviews in markets where Uber Eats and Delivery Hero brands overlap.
- What Prosus does with the proceeds.
Grab proposes US$1.49bn for majority control of Atome Financial
Southeast Asia’s super-app moves to own the lending book behind buy-now-pay-later at the checkout.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Consumer credit | 28 September 2026 | ~US$1.49bn | Reported, not disclosed |
The number comes from Linklaters’ announcement (opens in a new tab) that it is advising Grab on a proposed US$1.49bn acquisition of a majority stake in Atome Financial. We have not yet retrieved the SGX notice or a Grab release, so treat the terms as reported rather than filed.
Atome built its business on buy-now-pay-later and consumer credit across Southeast Asia. Grab already runs payments and a digital-banking push. Owning a scaled lending and underwriting operation closes the loop: Grab sees the transaction, and now it can fund the credit behind it.
The risk is the one that has hurt every BNPL operator since 2022: credit losses in a slowing consumer cycle, and regulators treating instalment credit as lending. Control means Grab owns that book outright rather than sharing it with a partner.
“Acquiry’s read Like Uber, Grab is buying a customer relationship it already sees at checkout. The difference is that this one comes with a balance sheet.”
- The exchange filing and the exact stake and valuation it confirms.
- Licensing approvals in each market where Atome lends.
04 · Market Report
Private equity pays up to leave the market
Two sponsor take-privates, one in medtech manufacturing and one in small-business software, show the same pattern: a clear gap between what public markets would pay and what private buyers will.
KKR bids US$127 a share for Integer, the contract maker behind cardiac devices
A 51.8% premium for a business most patients have never heard of, and most device makers depend on.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Medtech manufacturing | 3 August 2026 | US$5.7bn | Disclosed |
Integer’s announcement (opens in a new tab) sets the price at US$127 per share, about US$5.7bn of enterprise value and a 51.8% premium to the unaffected close on 29 April. As with Baldwin, the unaffected date is months before signing, a sign the market had already priced in some chance of a bid.
Integer, formerly Greatbatch, sits deep in the medical device supply chain. It makes the leads, batteries, catheters and assemblies that big OEMs put their names on. It is sticky, regulated work: switching a qualified supplier on a Class III device can take years.
Those qualities suit private ownership. Long customer contracts support leverage, and a sponsor can fund capacity and tuck-ins without explaining lumpy quarters to public investors.
“Acquiry’s read KKR is paying for switching costs. Every regulated product line Integer supplies is a contract its customers cannot easily walk away from.”
- Financing terms and how much leverage a regulated manufacturer can carry.
- Any customer-concentration disclosures in the proxy.
Francisco Partners takes Weave private for US$7.40 a share
Small-business software for dentists, optometrists and vets, sold for about US$650m at a 34% premium.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Vertical software | 18 August 2026 | US$0.65bn | Disclosed |
Weave’s press release exhibit (opens in a new tab) confirms a US$7.40 cash price, about 34% above the undisturbed level, for roughly US$650m of equity value. It is the smallest disclosed deal in our sample, and one of the most typical.
Weave has what sponsors look for in sub-scale public software: a focused customer base, recurring revenue, and a product that sits at the front desk of every practice it serves. Public investors wanted faster growth or higher margins. Francisco Partners can pursue either without the quarterly stock reaction.
Expect bolt-ons. Payments, patient engagement and AI reception agents are all adjacent products a private owner can buy and cross-sell into the installed base.
“Acquiry’s read This is the template for a mid-2020s software take-private: a real product, a stalled share price, and a buyer who can move faster than the market’s patience.”
- Go-shop outcome and any competing sponsor interest.
- Early add-on acquisitions in payments or AI front-desk tools.
05 · Market Report
Picks and shovels for the AI build-out
The quarter’s AI deals were not about models. They were about the layers around them: routing and billing for model traffic, and silicon that runs inference on a battery.
Stripe buys OpenRouter and puts itself in the path of AI model spend
Terms were not disclosed. A New York Times source put the price at about US$7.5bn, which would make it the largest AI infrastructure deal we recorded.
| Sector | Announced | Value | Status |
|---|---|---|---|
| AI infrastructure | 19 August 2026 | ~US$7.5bn | Reported, not disclosed |
CNBC reported (opens in a new tab) the acquisition on 19 August. Neither party gave a price. The roughly US$7.5bn figure comes from an anonymous source quoted by the New York Times, so we treat it as reported, not disclosed, and it is excluded from every total in this report.
OpenRouter is a routing and billing layer for large language models. Developers call one API, and OpenRouter picks the model, provider and price and settles the bill. Every AI request that flows through it is also a payment. That is why Stripe wants it.
The fit is billing, not intelligence. Stripe already processes usage-based subscriptions for a large share of AI companies. Owning the router lets it see, meter and settle model consumption at the source, and potentially offer credit and fraud controls on top of it.
“Acquiry’s read Stripe is betting that AI spend becomes a payments category of its own, and it wants to own the checkout for it.”
- Whether model providers treat a Stripe-owned router as neutral.
- Any confirmed price in Stripe’s next investor or tender-offer materials.
Analog Devices pays US$1.35bn cash for Alif and its edge-AI microcontrollers
A bet that the next billion AI inference chips will be in wearables, sensors and appliances, not data centres.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Semiconductors | 9 September 2026 | US$1.35bn | Disclosed |
The ADI filing (opens in a new tab) confirms a US$1.35bn all-cash purchase of Alif Semiconductor. It is small by ADI’s standards, but it answers a gap in its portfolio: low-power processors that run machine-learning models directly on the device.
ADI’s strength is the analog edge, the sensors, converters and power parts that turn the physical world into data. Alif sits one step up, running inference on that data locally without a cloud round trip. Put together, ADI can sell a sensing-to-decision reference design rather than components.
For context on how silicon strategy has shifted this year, see our analysis of AMD and World Labs, which came at the same problem from the model end.
“Acquiry’s read Cash, not shares, and a price below US$1.5bn. ADI is buying a roadmap it could not build fast enough, and it isn’t reaching for scale.”
- Design-win announcements that bundle ADI sensors with Alif processors.
- Retention of Alif’s engineering team.
06 · Market Report
Crypto firms buy the regulated plumbing
Both digital-asset deals we could verify were purchases of licences, flows and institutional relationships, not tokens or protocols.
Circle buys Tazapay for US$400m to push USDC into trade payments
The USDC issuer adds a Singapore-based cross-border payments business and the licences that come with it.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Stablecoins and cross-border payments | 8 September 2026 | ~US$0.40bn | Reported, not disclosed |
CoinDesk reported (opens in a new tab) that Circle agreed to buy Tazapay for US$400m. We retrieved the article text and the terms matched. We have not seen the figure in a Circle filing.
Tazapay handles collections and payouts for businesses trading across Asia, the Middle East and beyond. The hard part of that business is not the software. It is the licences, banking partners and compliance stack in each corridor. Circle is buying those so USDC can settle real invoices, not just crypto trades.
Set it next to Grab and Atome: in both cases, the buyer is paying for regulated access to Asian payment flows.
“Acquiry’s read Stablecoin issuers are becoming payment companies. This is Circle buying the corridors rather than waiting to be invited in.”
- Licence transfer approvals in Tazapay’s key markets.
- USDC settlement volumes Circle attributes to the business.
BitGo agrees to buy NYDIG’s institutional trading business, price blank
The filing is signed and dated. The share counts in the exhibit are not, so the value is officially undisclosed.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Institutional digital assets | 27 August 2026 | Undisclosed | No price published |
BitGo’s 8-K exhibit (opens in a new tab) references an Equity Purchase Agreement dated 27 August and shows that part of the consideration is paid in BitGo Class A shares. The share counts in the filed form are blank, so no value can be inferred.
BitGo’s core is custody and wallet infrastructure. Adding NYDIG’s institutional trading operation lets it offer execution alongside safekeeping, which is what asset managers and corporates holding bitcoin increasingly ask for.
Paying partly in stock also makes NYDIG’s owners BitGo shareholders, an alignment choice that is common when the buyer’s shares are liquid and the seller believes in the combined platform.
“Acquiry’s read A small deal on paper. It shows custody businesses turning into full-service prime brokers for digital assets.”
- The definitive share count in a later filing or registration statement.
- Client migration from NYDIG to BitGo.
07 · Market Report
Pipelines, pills and a bank merger
Outside technology and financial services, three deals stand out: a midstream bolt-on, a consumer-health brand and a bank combination where the listed company is not the one in control.
ONEOK adds Brazos’s Midland Basin assets for US$4.425bn
Another gathering and processing bolt-on in the Permian, extending a buying streak that began with Magellan.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Midstream energy | 30 August 2026 | US$4.43bn | Disclosed |
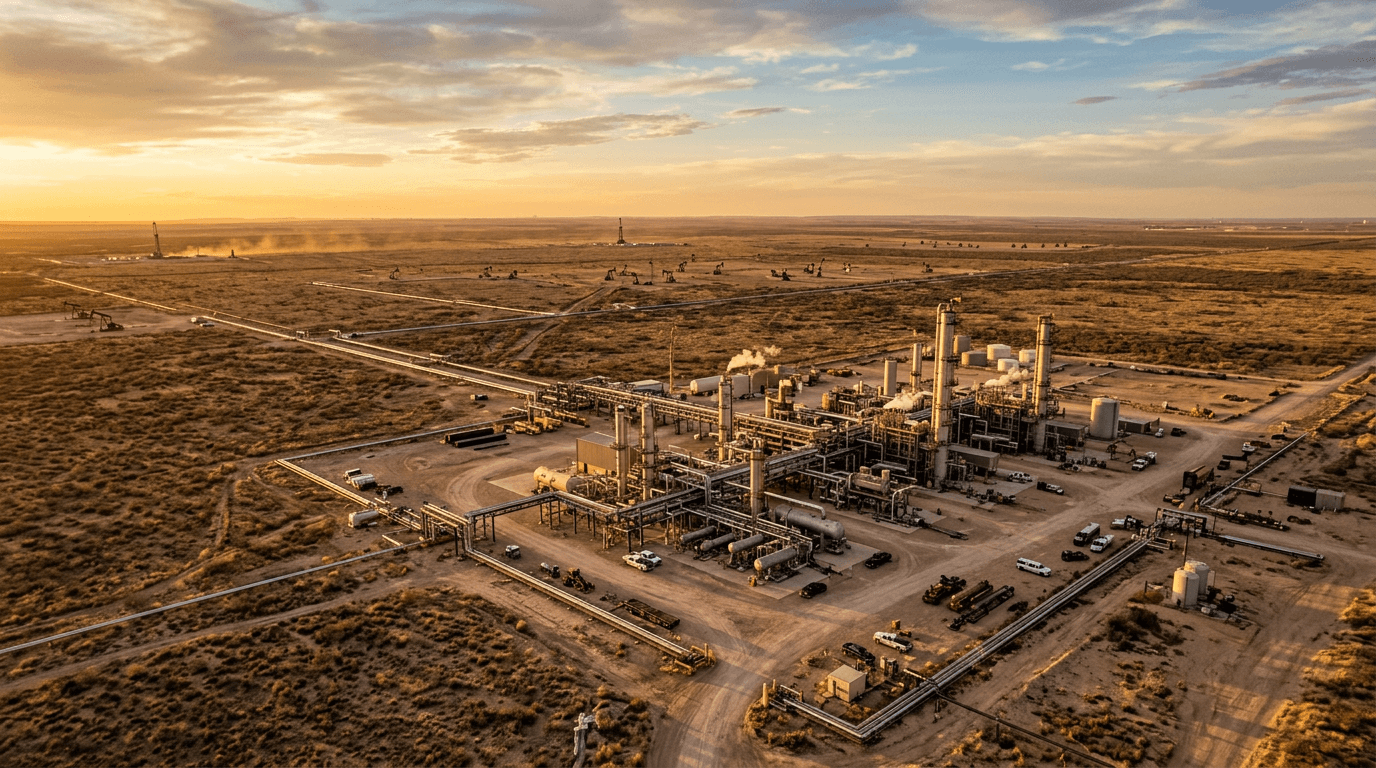
ONEOK’s release (opens in a new tab) sets the purchase price at US$4.425bn for Brazos Midstream’s Permian Midland Basin assets. We retrieved the text through a syndication site and the terms matched.
ONEOK has spent three years turning itself from a natural-gas-liquids specialist into a diversified midstream major, through Magellan in 2023 and EnLink and Medallion in 2024. Brazos adds gathering and processing capacity in the same basin, feeding volumes into pipes ONEOK already owns.
These are some of the most predictable deals in M&A: fee-based contracts, known geology and obvious synergies. Execution risk sits with producer drilling activity, not integration.
“Acquiry’s read Bolt-ons like this are the cleanest synergy maths of the quarter. ONEOK is buying volume for its own pipes.”
- Hart-Scott-Rodino clearance timing.
- Producer activity guidance in the Midland Basin.
Procter & Gamble agrees to buy Thorne for US$3.8bn
Disclosed not in a press release but in a subsequent-events note in P&G’s annual report. It is a large bet on premium supplements.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Consumer health | 4 August 2026 | US$3.8bn | Disclosed |
The deal surfaced in the subsequent-events note of P&G’s 10-K (opens in a new tab): an agreement dated 4 August to acquire Thorne for US$3.8bn. For a company that has mostly shrunk its brand portfolio over the past decade, that is a notable reversal.
Thorne was taken private by L Catterton in 2023. If the headline holds, the sponsor has multiplied its money in about three years, a strong reference point for anyone selling a premium consumer-health brand.
For P&G, Thorne adds a practitioner channel and a direct-to-consumer data relationship its mass-market vitamin lines lack. The integration risk is cultural: a clinical, science-led brand inside a mass-marketing machine.
“Acquiry’s read P&G rarely buys. When it does, it pays for categories where it believes premium pricing will hold through a downturn.”
- Whether P&G keeps Thorne operating as a standalone brand.
- Any earnout or contingent consideration disclosed at close.
EverBank and WaFd combine in an all-stock deal EverBank will control
WaFd files the paperwork, but EverBank’s holders end up with 59.2% of the combined bank.
| Sector | Announced | Value | Status |
|---|---|---|---|
| Regional banking | 8 September 2026 | ~US$3.9bn | Reported, not disclosed |

The WaFd filing (opens in a new tab) describes an all-stock combination in which EverBank holders will own 59.2% of the combined company and WaFd holders 40.8%. The US$3.9bn headline value circulating in press coverage does not appear in the text we retrieved, so we hold it as reported.
The ownership split is the story. WaFd is the listed filer, but economic control goes to EverBank’s owners, making this effectively a reverse merger that gives a private bank a public listing and a Pacific Northwest franchise in one move.
Regional bank consolidation has been held back for years by slow approvals. A deal of this size is a test of how quickly regulators are now willing to clear mid-sized combinations.
“Acquiry’s read Count this as EverBank buying WaFd, whatever the filing header says. The ownership split decides who is really in charge.”
- Regulatory approval timeline.
- Board composition and which management team leads the combined bank.
Off the books
08 · Market Report
Reported, not confirmed
Big headlines we could not verify from a filing or company release. They are part of the story of the quarter, but they are not in our numbers.
Nvidia and Hugging Face
US$12.9bn, reported
A syndicated report on 27 August said Nvidia had agreed to buy Hugging Face for US$12.9bn. Neither company confirmed it in anything we could retrieve, and the only EDGAR hit was an unrelated mention. If true, it would be the largest AI deal of the year. Until one of the parties confirms it, it stays out of our numbers.
Syndicated report (MSN)
Goldman Sachs and NEOS
US$2.25bn, headline only
Headlines on 12 August put a US$2.25bn price on Goldman’s purchase of NEOS, the options-income ETF issuer, including its bitcoin and ether funds. We found no SEC filing in the window. It would fit Goldman’s push into asset management and BitGo’s thesis that institutions want digital-asset exposure in regulated wrappers.
Cyera completes Oasis Security
Terms undisclosed
Data-security company Cyera said on 3 September it had completed its acquisition of Oasis Security, a specialist in non-human identity: the service accounts, API keys and AI agents that now outnumber human users in most enterprises. Both are private, so no filing is expected.
Syndicated release (Yahoo Finance)
Casualties
09 · Market Report
Deals that broke, or might
Terminated deals and regulatory threats. They show where the ceiling on dealmaking currently sits.
Solstice and Element walk away
US$14.5bn merger terminated
Reuters reported on 27 August that Solstice and Element had terminated their US$14.5bn merger after shareholder feedback. It is the largest broken deal we recorded. It would have been the third-largest in our sample had it survived.
Reuters
Brussels lines up against UPM and Sappi
Reported block, no decision yet
EU antitrust regulators were reported on 18 September to be preparing to block the combination of the two paper and pulp producers, citing people familiar with the matter. No Commission decision had been published at our cutoff.
Syndicated Reuters report (MSN)
Howmet and a GE Aerospace deal
Counterparty unidentified
Howmet’s chief executive told Reuters on 9 September he was “fine” with a GE Aerospace deal. We could not identify the counterparty or terms, so it is noted here and excluded from everything else.
Analyst profile
10 · Market Report
How we built this
This is a curated sample, not a census of global M&A. We found candidates through news discovery, then matched each deal’s terms against SEC EDGAR filings or the text of a company release. Values are US dollars as announced. Where a price includes debt repayment, or is an asset price rather than equity value, the deal file says so. Research cutoff: 30 September 2026. Final Q3 figures from the major data providers are usually published in early October.
Keep reading
Related analysis
Market Report · Digital M&A
The Flight to Control: Q2 2026 Digital M&A Market Report
Headline value accelerated while deal count contracted. Buyers paid less for category exposure and more for control: infrastructure, licences, proprietary data, workflow and distribution.
Research · AI
The Great Re-rating:Q1 2026 Digital M&A Market Report
The Great Re-rating: Q1 2026 Digital M&A Market Report. Acquiry provides specialist digital M&A advisory for buyers and sellers.
News · SaaS
SaaS Valuation Multiples in 2026: What the Data Actually Shows
By Joash Boyton, Founder & Managing Director, Acquiry • February 2026
Explore the sector:Fintech M&ASaaS acquisitions
About the analyst

Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.