
01 · Deal Intelligence
01 · Transaction
02 · Deal Intelligence
What Schneider is bidding for
Schneider Electric, through SE 2026 A SAS, has signed an investment agreement for an intended voluntary public takeover of all outstanding Shelly Group shares at EUR 70.00 per share, contingent on at least 95% acceptance and regulatory clearances.
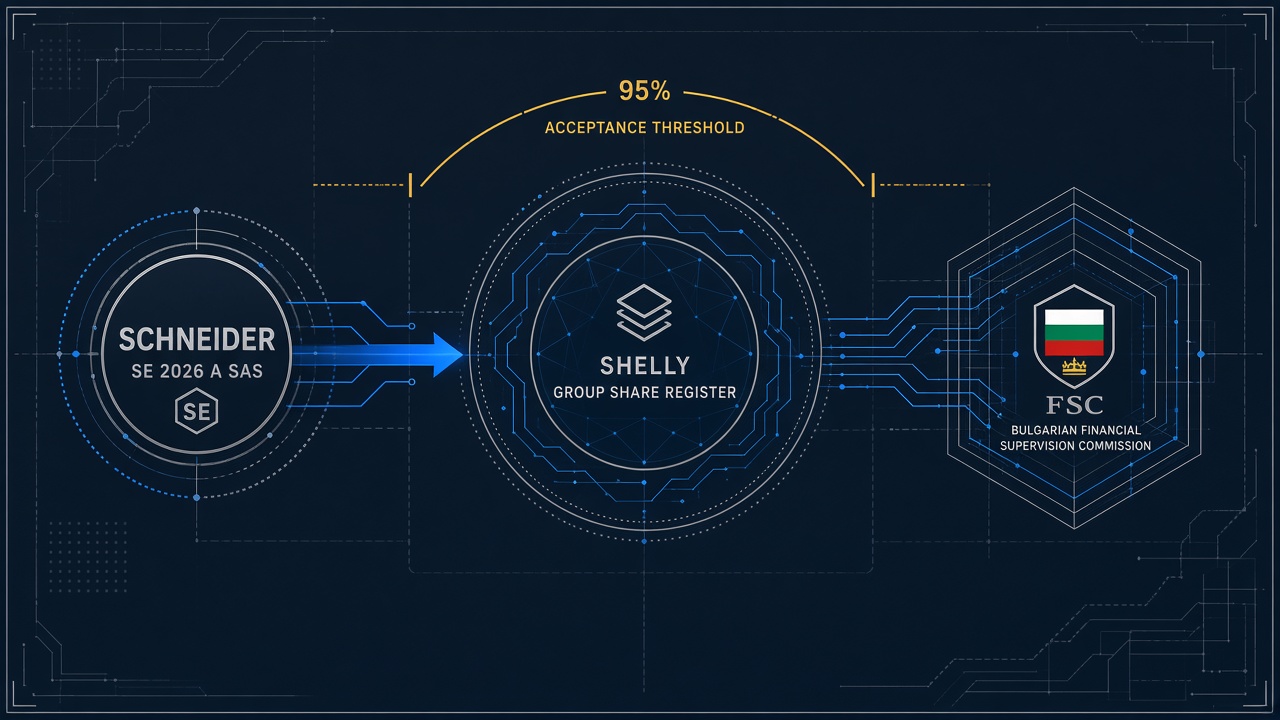
Legal identity matters. The bidder is SE 2026 A SAS, an indirectly wholly-owned subsidiary of Schneider Electric SE. The target is Shelly Group SE, listed on Frankfurt’s Regulated Market (Prime Standard) with Sofia and Munich as the operating centre of gravity for its smart-home device business. The investment agreement is the document that exists today. The offer document is the document that does not.
The 95% threshold is the industrial structure. Schneider is not describing a simple majority bid that leaves a large stub. It is describing a path that, if completed, would put the Schneider group at or above the level typically associated with squeeze-out mechanics in European public takeovers. The adhoc is careful: completion is subject to the published offer document, applicable regulatory clearances and that minimum acceptance threshold.
Board posture is preliminary, not a final reasoned opinion. On the information available to date, Shelly’s directors say a voluntary public takeover at EUR 70.00 would be in the interests of the company, shareholders, employees and other stakeholders. Secondary coverage has also reported founder support. Founder alignment, if it holds into the formal offer, is how a 95% bar becomes achievable rather than theoretical.
02 · Price
03 · Deal Intelligence
How the EUR 70.00 offer is framed
The primary price is EUR 70.00 per share. Secondary reporting puts equity value at about EUR 1.27 billion excluding debt, or roughly $1.45 billion. Enterprise value, net debt and a purchase multiple are not in the adhoc.
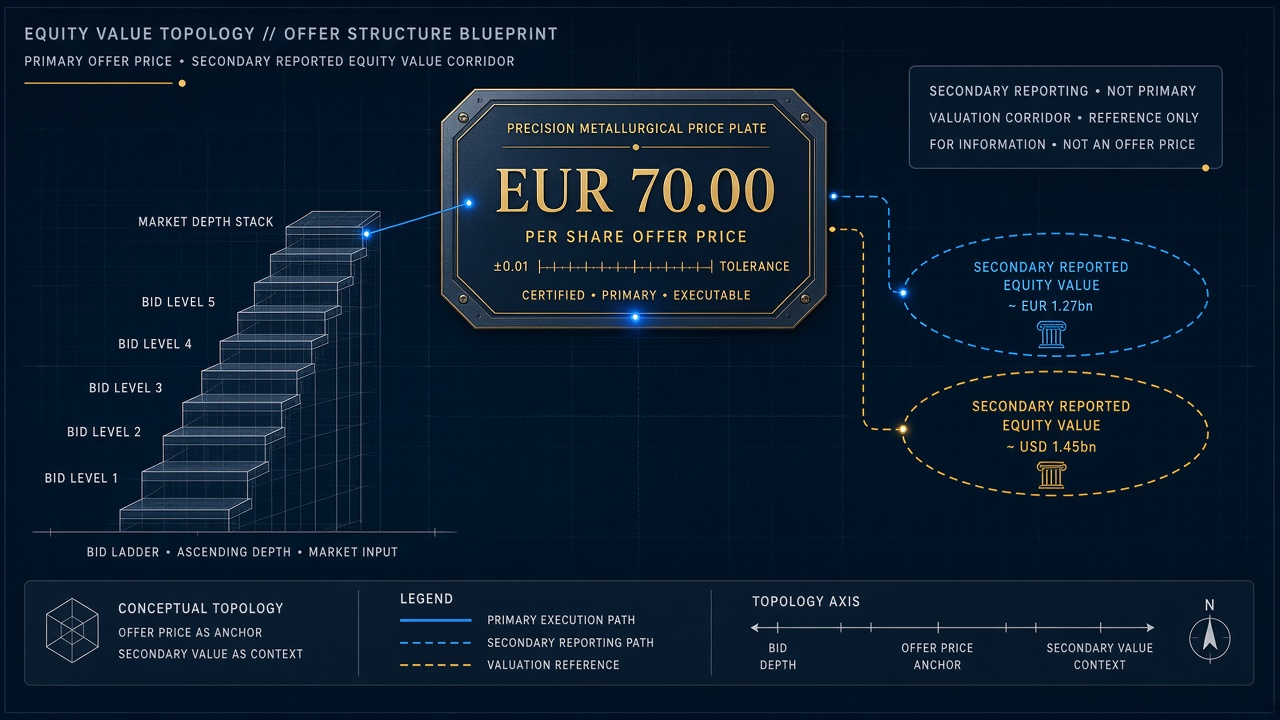
EUR 70.00 is the only consideration figure Shelly’s MAR disclosure states. It is cash-per-share language for an intended voluntary offer, not a staged formula and not a mix of cash and paper. Until the offer document appears, that is the price investors can underwrite against.
Reuters, republished by Global Banking & Finance Review, reported that the EUR 70.00 offer values Shelly at around EUR 1.27 billion ($1.45 billion) excluding debt. Bloomberg was earlier reported as covering advanced talks at the same price corridor. Those equity-value figures are labelled secondary here because they are not restated in the EQS adhoc. They are useful context for deal size; they are not a substitute for a primary enterprise-value bridge.
Offer architecture and secondary equity print
Chart data
| Item | Value | Label |
|---|---|---|
| Offer price per share | EUR 70.00 | Primary (adhoc) |
| Minimum acceptance | 95% | Primary (adhoc) |
| Equity value excl. debt | ~EUR 1.27bn | Secondary (Reuters) |
| Approx. USD equity | ~$1.45bn | Secondary (Reuters) |
Shelly EQS adhoc for price and threshold. Reuters via Global Banking & Finance Review for equity value excl. debt.
03 · Fit
04 · Deal Intelligence
Why smart-home devices fit Schneider
Schneider Electric is an industrial energy-management and automation group. Shelly Group builds connected home devices (relays, sensors, meters and cloud control) that sit at the residential and light-commercial edge of that same energy stack.
Shelly’s public identity is a Sofia- and Munich-centred maker of smart-home technology: compact connected devices that switch loads, read energy, sense the room and talk to a cloud control layer. Schneider’s public identity is larger and heavier: power management, industrial automation, data-centre infrastructure and building systems. The acquisition logic is density at the edge: put a fast-growing consumer and prosumer device franchise inside a group that already sells the panel, the software and the integrator relationships that sit one layer up.
That is a distribution argument as much as a product argument. Schneider already reaches installers, utilities-adjacent channels and building OEMs. Shelly already reaches DIY and professional smart-home channels across a wide geographic footprint. Owning Shelly lets Schneider decide whether those channels stay separate, cross-sell, or gradually share identity and energy data, without inventing a Day-1 app merge that the adhoc does not describe.
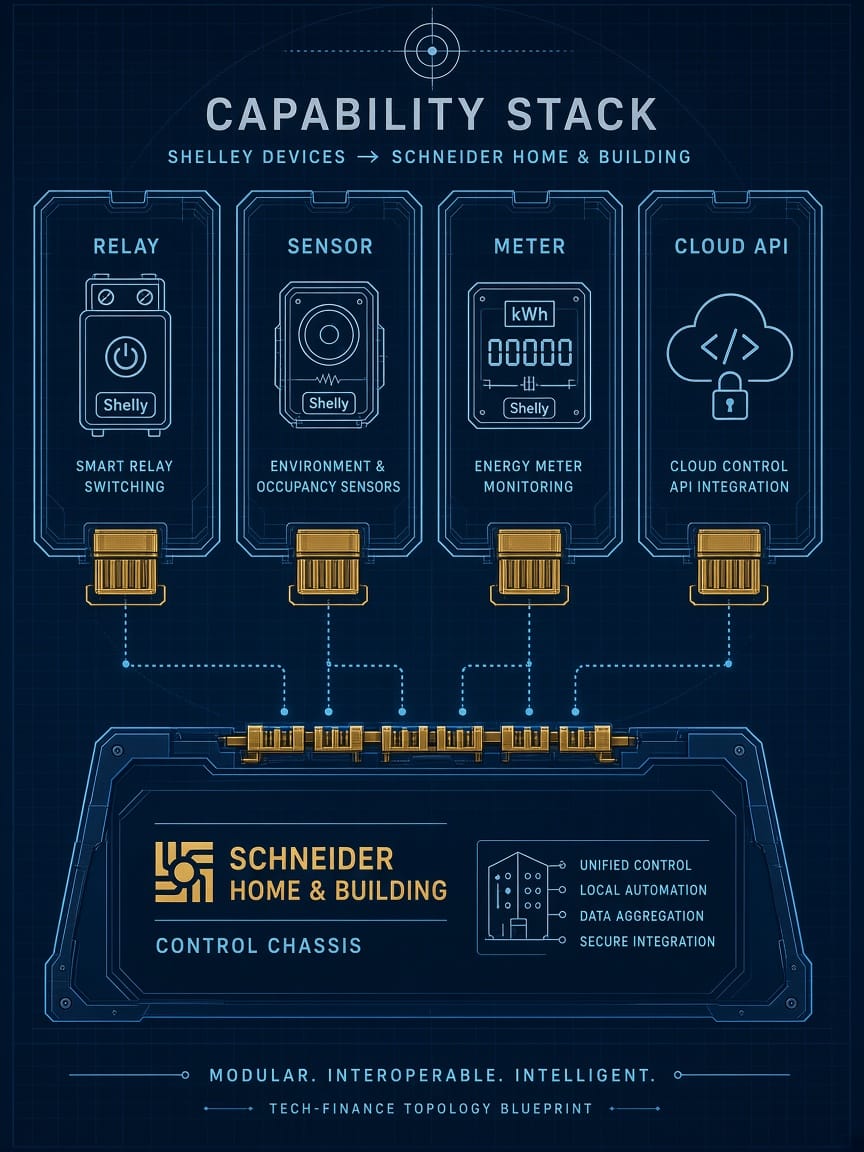
Capability transfer is the other half. Shelly’s stack is device firmware, cloud orchestration and a product cadence that ships connected hardware into retail and professional channels. Schneider’s stack is systems, standards and long-cycle enterprise selling. The combination is useful if Schneider can keep Shelly’s product velocity while plugging device telemetry into broader energy-management offers. It is less useful if the device franchise is forced into industrial release cycles that blunt the brand that created the growth.
Secondary H1 2026 figures, with revenue up roughly a quarter and EBIT and net profit up faster still, describe a company already compounding at the edge Schneider wants. The industrial question after close is whether that growth rate survives inside a larger group, not whether the products conceptually fit.
04 · Numbers
05 · Deal Intelligence
What the H1 2026 baseline says
Zonebourse secondary coverage puts Shelly’s H1 2026 revenue at EUR 68.3 million (+26.5%), EBIT at EUR 17.7 million (+45.6%) and net profit at EUR 15.4 million (+51.4%). Those figures are secondary, not restated in the investment-agreement adhoc.
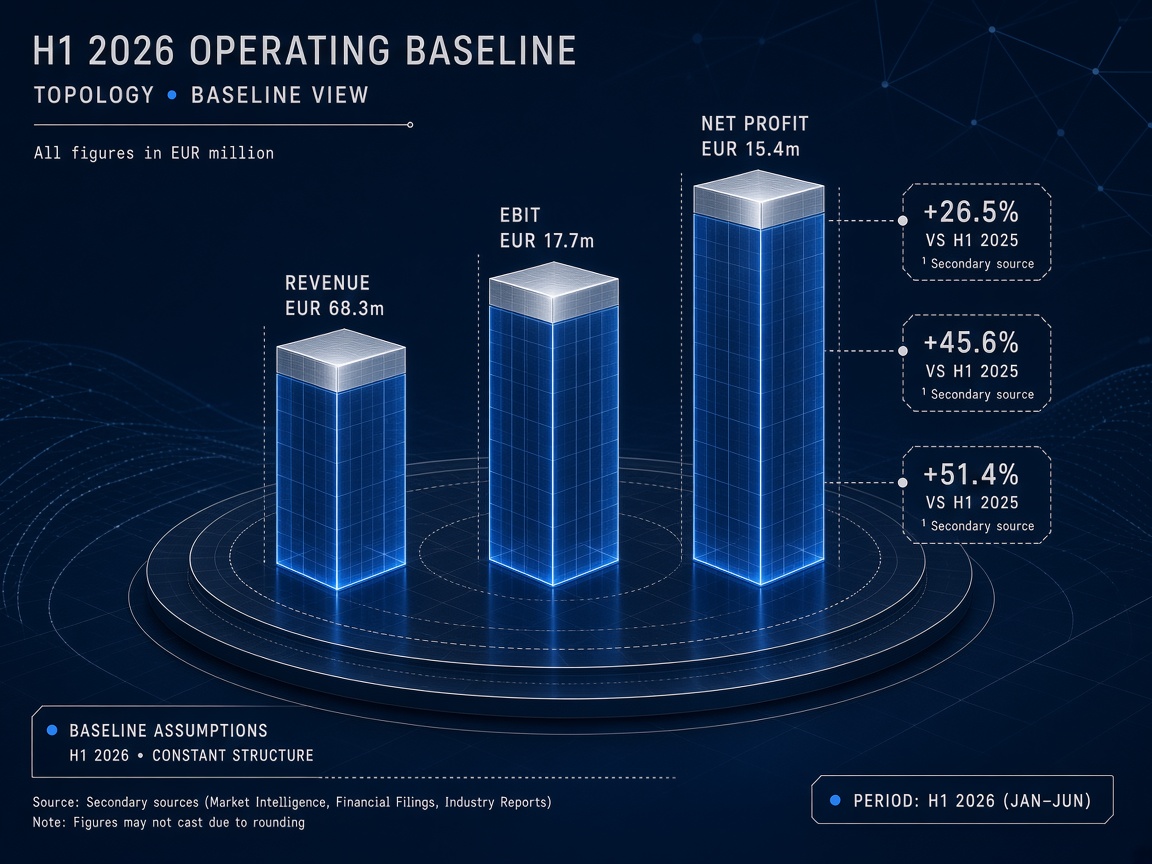
Keep the labels honest. TradingSat’s Zonebourse copy is secondary reporting of Shelly’s first-half operating results, not Shelly’s MAR takeover disclosure. Revenue of EUR 68.3 million with 26.5% growth, EBIT of EUR 17.7 million with 45.6% growth and an EBIT margin of about 26%, and net profit of EUR 15.4 million with 51.4% growth, describe a profitable, accelerating device business. They do not, by themselves, produce a clean trailing multiple against the secondary equity value, because debt, cash, seasonality and full-year annualisation are not bridged in that coverage.
What the baseline does establish is why Schneider would pay cash for control rather than partner at arm’s length. A smart-home franchise growing revenue mid-twenties and expanding EBIT faster than sales is the kind of edge asset industrial groups usually build slowly. Buying it at a published cash price, subject to 95% acceptance, is the faster route, if the offer clears.
H1 2026 operating baseline (secondary)
| Item | Value | Label |
|---|---|---|
| Revenue | 68.3 | Secondary (Zonebourse) |
| EBIT | 17.7 | Secondary (Zonebourse) |
| Net profit | 15.4 | Secondary (Zonebourse) |
Zonebourse via TradingSat. Not restated in Shelly’s investment-agreement adhoc.
05 · Close
06 · Deal Intelligence
What still has to happen
The investment agreement is signed. The formal offer is not. Bulgarian FSC review, offer publication, the 95% acceptance threshold and other regulatory clearances all sit ahead. Expected close timing is not in the investment-agreement adhoc.
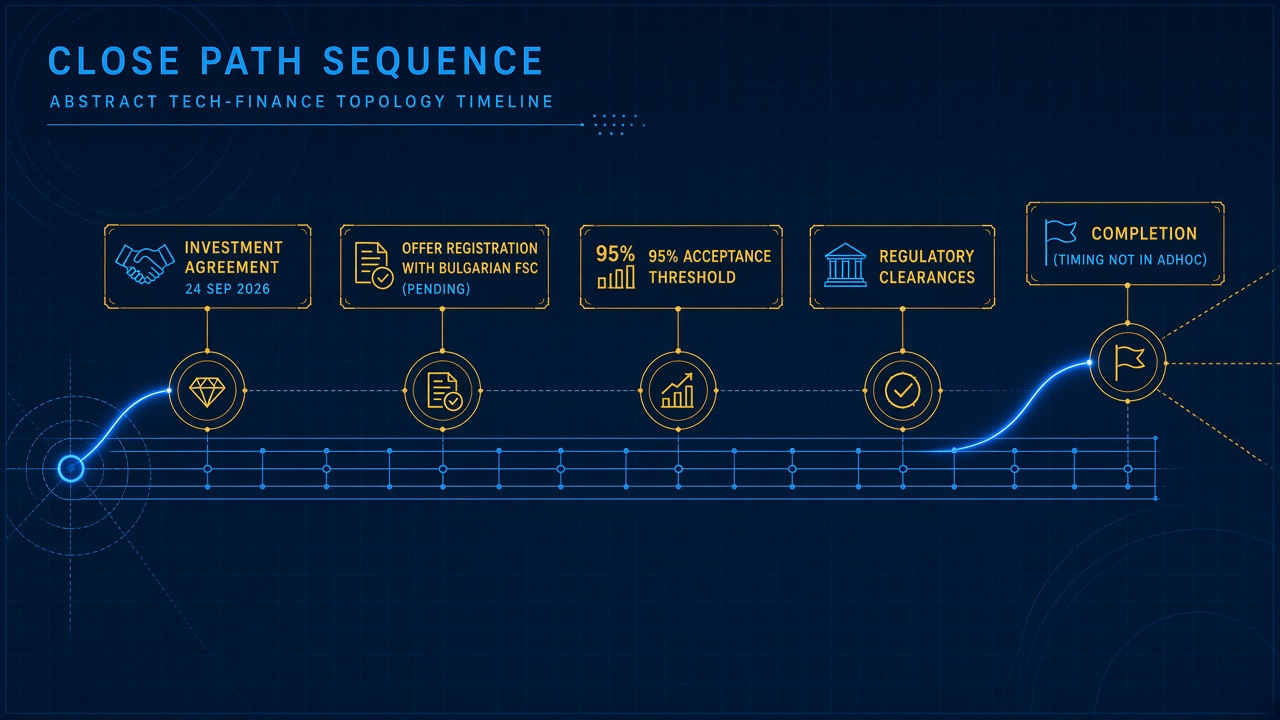
Shelly’s disclosure is explicit about what this announcement is not. It does not constitute an offer to acquire or sell securities. The Bulgarian Financial Supervision Commission may suspend or prohibit publication of any offer. Completion, if an offer is launched, will be subject to the published offer document, applicable regulatory clearances and the minimum acceptance threshold.
Some secondary coverage has mentioned a possible Q1 2027 completion window. That date is not treated here as primary. The investment-agreement adhoc does not name an expected close. Until a formal offer document or a later MAR update does, the live calendar is: support the registration path, clear the FSC, publish the offer, clear 95%, clear other regulators, then complete.
- Investment agreementSigned 24 Sep 2026. Intended voluntary offer at EUR 70.00 with company support terms.
- Formal offer / FSCPending. Not registered or published as of the adhoc.
- Acceptance threshold95%. Direct, affiliates and indirect holding after completion.
- Close timingNot in adhoc. Secondary Q1 2027 mentions are not primary facts.
06 · View
07 · Deal Intelligence
Acquiry view
Acquiry view. Schneider is buying an edge franchise it would otherwise have to assemble device by device. EUR 70.00 cash and a 95% bar are a clear, almost squeeze-out structure. The equity value that makes the headline, about EUR 1.27 billion excluding debt, is secondary reporting, and that honesty matters. The industrial thesis does not need an invented multiple to stand up.
The best companies are acquired, not sold. Shelly’s board has already said, on a preliminary basis, that this price is in stakeholders’ interests, and secondary reports describe founder support. If that alignment holds through FSC publication and the acceptance period, Schneider gets a profitable, fast-growing smart-home stack inside an energy-management group that already sells the layer above. If the 95% bar fails, the agreement has already told investors what Schneider was unwilling to own: a large listed stub.
Sources
08 · Deal Intelligence
Sources and methodology
Shelly’s EQS adhoc ranks above secondary reporting. Equity value excl. debt and H1 2026 operating figures are labelled secondary where they appear. Close timing is not taken from coverage that is absent from the adhoc.
- 1.01EQS adhoc: Shelly Group investment agreement with Schneider Electric, 24 September 2026 (opens in a new tab)Primary
- 2.02Global Banking & Finance Review (Reuters), 24 September 2026 (opens in a new tab)Reported
- 3.03TradingSat / Zonebourse, Schneider OPA on Shelly Group, 24 September 2026 (opens in a new tab)Reported
- 4.04Global Banking & Finance Review (Reuters/Bloomberg talks coverage), 24 September 2026 (opens in a new tab)Reported
- 5.05Shelly Group corporate / investor site (opens in a new tab)Company
- 6.06Acquiry Deal Intelligence calculations and labellingAcquiry
Method: Acquiry Deal Intelligence methodology. Acquiry was not engaged by any party. Nothing here is investment advice.
Keep reading
Related analysis
Deal Intelligence · Industrials
Telix to Acquire ITM for $1.65bn and Own the Radioisotope Stack
Telix will acquire 100% of ITM for US$1.65bn cash-free/debt-free, mostly in shares, plus up to US$700m of ITM-11 milestones. Close is targeted by the end of 2026.
Deal Intelligence · Industrials
GE Aerospace to Buy CPP: $11.75bn for Mission-Critical Castings
GE Aerospace agreed to acquire Consolidated Precision Products for a $11.75bn cash purchase price, financed with $7bn cash and the remainder in new debt, with close aimed at the second half of 2027.
Deal Intelligence · Industrials
Madison Air Acquires ebm-papst and Builds a Global Airflow Platform From the Component Up
Madison Air’s acquisition of ebm-papst: €5.1bn enterprise value, 14.6x forecast 2026 adjusted EBITDA, $160m run-rate synergy plan and the industrial logic behind a cross-border airflow platform.
About the analyst

Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.