
01 · Deal Intelligence
01 · Transaction
02 · Deal Intelligence
What GE Aerospace is buying
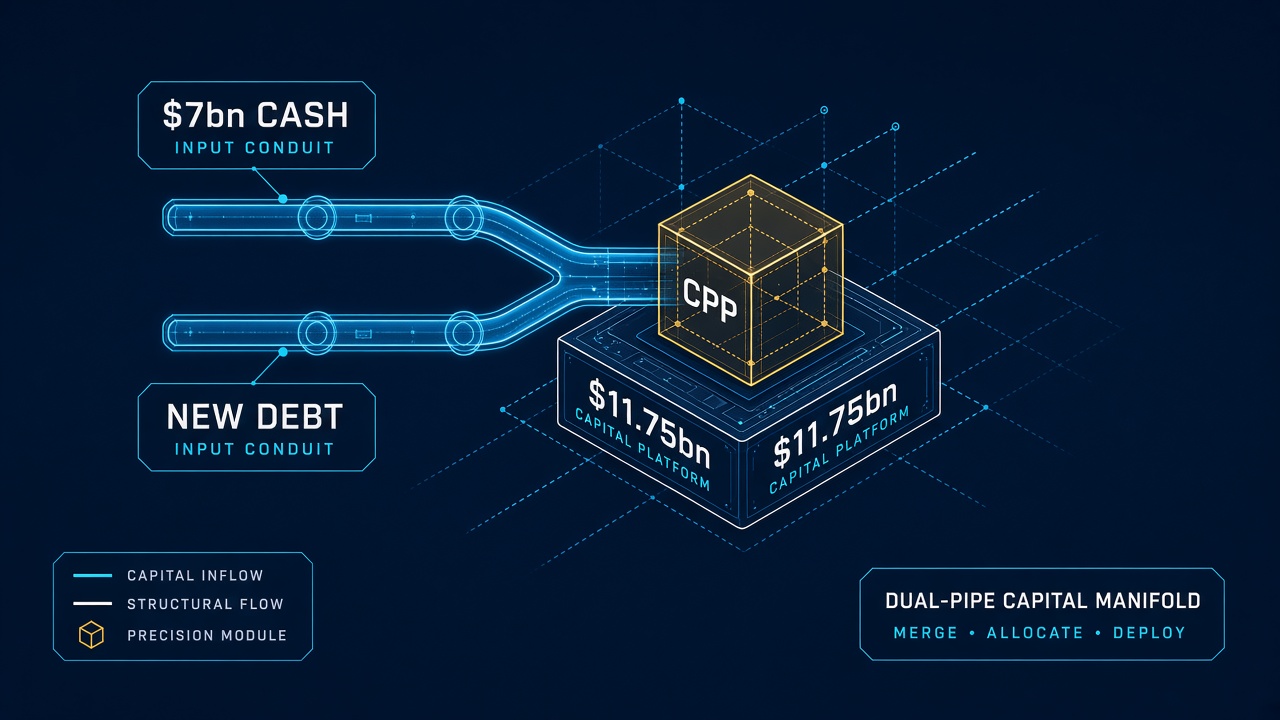
GE Aerospace is paying a disclosed $11.75 billion cash purchase price for Consolidated Precision Products, financed with $7 billion of cash and the remainder in new debt, with close aimed at the second half of 2027.
The 8 September announcement from Cincinnati is a supplier take-in. CPP is headquartered in Cleveland, Ohio, and was founded in 1991. The press release describes it as one of the world’s largest producers of investment and precision sand castings, spanning superalloy, titanium, aluminum, magnesium and steel for commercial and military aircraft, weapon systems, helicopters and industrial gas turbines. The company states a global team of about 6,600 employees across more than 20 facilities.
GE Aerospace has been a CPP customer for over fifteen years. That is the commercial tell. This is not a cold auction of an unknown foundry. It is a long-standing supplier relationship converting into ownership. Chairman and CEO H. Lawrence Culp, Jr. put the strategic sentence on the page: investing in mission-critical casting capacity is needed to support strong simultaneous demand across commercial engines, aftermarket and defense.
Advisers on the release are named. Paul, Weiss, Rifkind, Wharton & Garrison LLP is lead legal counsel to GE Aerospace. Evercore and PJT Partners are lead financial advisers to GE. Morgan Stanley & Co. LLC and Guggenheim Securities, LLC advised CPP, with Cleary Gottlieb as legal counsel. Those names sit on the closing desk. They do not change the industrial thesis.
GE also says there is no change to its capital allocation plans. That is a company statement about what this cheque does not displace, not a sources-and-uses table. Until regulatory clearance lands, this remains signed, not owned.
02 · Price
03 · Deal Intelligence
How the $11.75bn cheque is built
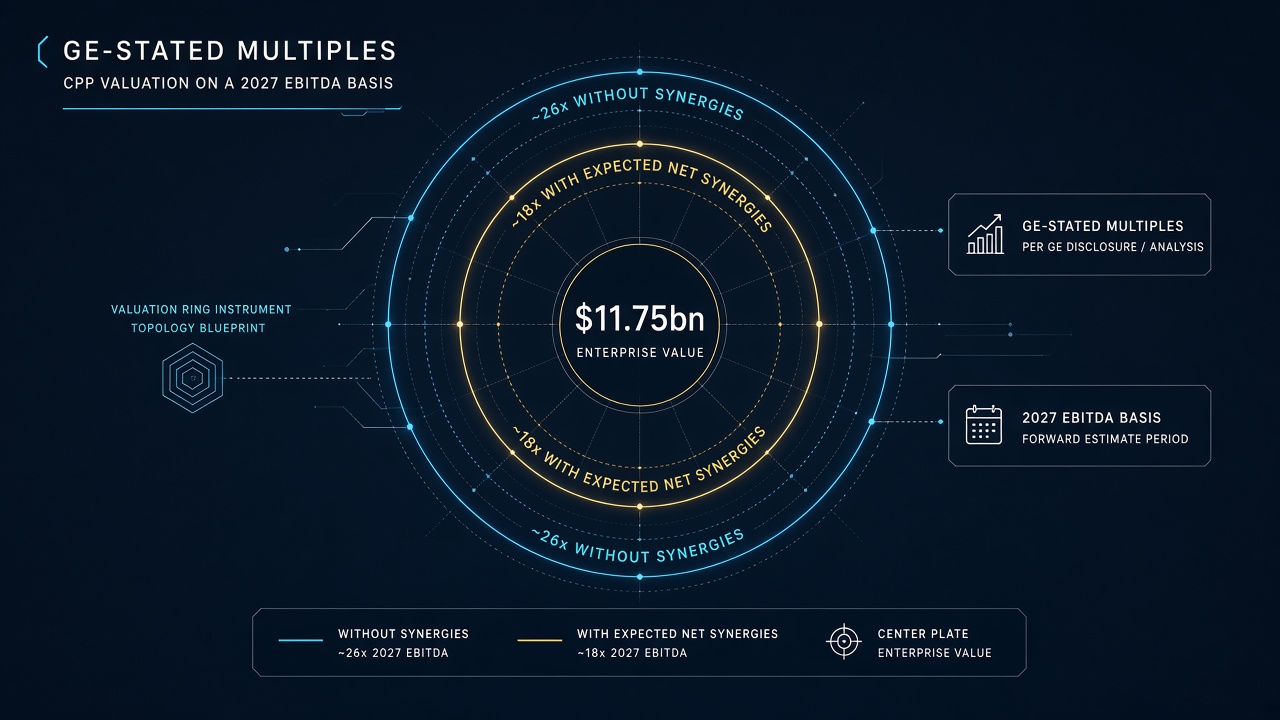
The disclosed stack is simple: $11.75 billion cash purchase price, $7 billion of cash financing, the remainder in new debt, and GE-stated 2027 EBITDA multiples of about 18x with expected net synergies or about 26x without.
Subtracting the $7 billion cash slice from the $11.75 billion purchase price leaves $4.75 billion as the disclosed remainder to be financed with new debt. That residual is an Acquiry calculation ($11.75bn − $7bn). GE did not publish a named facility size, a coupon, or a post-close leverage table in the IR update. Treat $4.75 billion as the arithmetic the announcement allows, not as a term sheet.
The investor presentation furnished with the 8-K adds operating colour without inventing a public EBITDA dollar print. GE targets about $200 million of net synergies, with productivity described as more than 2x the contribution from supply-chain and procurement and other buckets. It also states a double-digit ROIC by year five. Those are company forward statements. Adjusted EPS and free cash flow accretion in year one is likewise GE-stated, and the asterisk is material: excluding one-time costs and deal-related amortization.
How the $11.75bn purchase price is financed
Chart data
| Item | Value | Label |
|---|---|---|
| Cash purchase price | 11.75 | Disclosed |
| Cash financing | 7.00 | Disclosed |
| Remainder in new debt | 4.75 | Acquiry calculation |
GE Aerospace IR update and press release. Remainder is Acquiry arithmetic from disclosed inputs.
GE-stated 2027 EBITDA multiples
| Item | Value | Label |
|---|---|---|
| With expected net synergies | ~18x | GE-stated |
| Without synergies | ~26x | GE-stated |
| Expected net synergies | ~$200m | GE investor presentation |
GE Aerospace announcement and Exhibit 99.1 investor presentation.
03 · Fit
04 · Deal Intelligence
Why the businesses fit
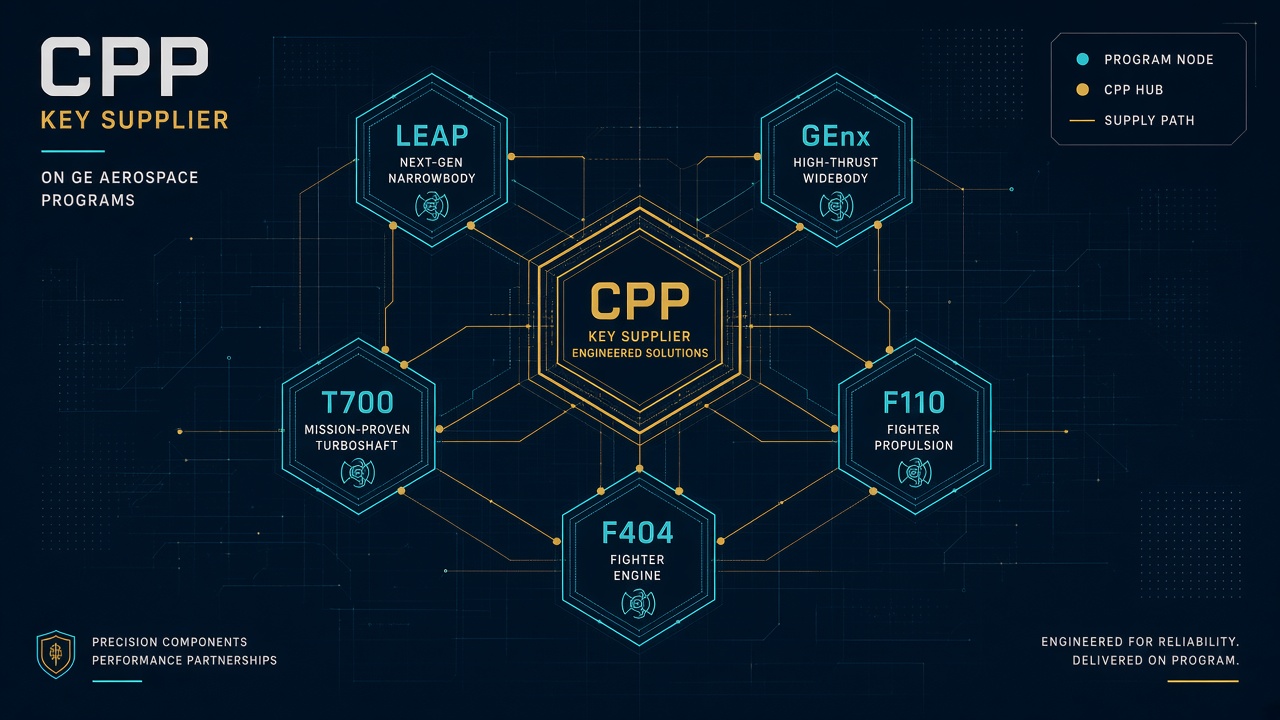
GE is buying castings capacity into a bottleneck that sits under commercial engines, aftermarket and defense at once, with CPP already a key supplier on named GE programs including LEAP and GEnx.
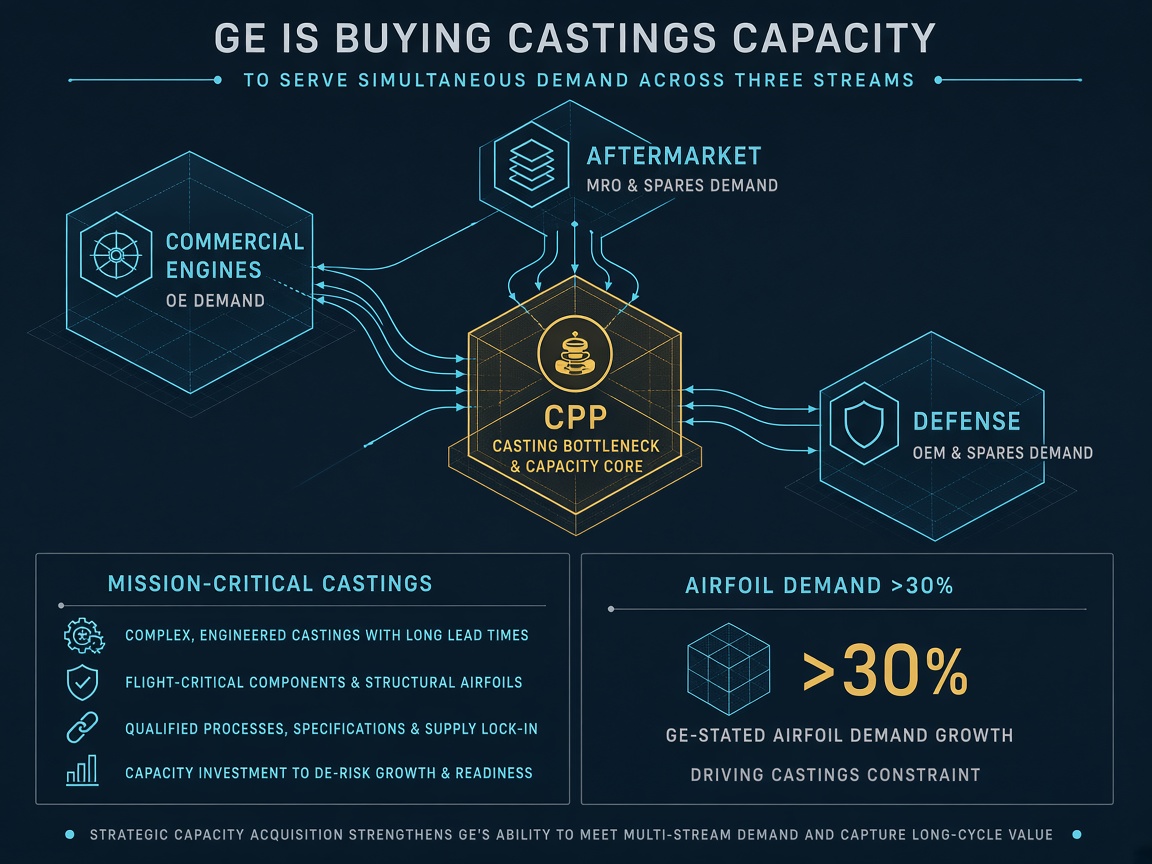
Reuters framed the industrial problem in plain language: precision-cast metal parts used in jet engines, including turbine blades and vanes, have been a supply constraint. GE’s own presentation says airfoil demand is growing more than 30% across commercial engines, aftermarket and defense. Buying CPP is one way to put capacity under that curve without waiting for every supplier to expand on its own clock.
CPP is already inside GE’s program map. The investor materials name LEAP, GEnx, T700, F110 and F404 as key GE Aerospace programs where CPP is a key supplier. That list is the distribution argument in reverse. GE already consumes the product. Ownership changes who controls the ramp, the yield and the readiness to deploy new airfoil technology.
Culp’s second point matters for the technology story. GE wants to combine its technology capabilities and FLIGHT DECK, its proprietary lean operating model, with CPP’s manufacturing experience. The claimed outcomes are higher output, process and quality improvements, and faster deployment of enhanced airfoil technology for the current fleet and next-generation platforms. That is a design-to-manufacturing integration argument, labelled as a company expectation.
CPP CEO James Stewart called GE a long-standing partner and said the companies expect to strengthen that relationship. Warburg Pincus and Berkshire Partners both described a platform they had scaled with management. Those are seller-side closing remarks. The strategic content sits in GE’s capacity and technology language.
04 · Numbers
05 · Deal Intelligence
What the GE-stated numbers say
GE’s investor presentation states about $2.0 billion of CPP 2027E revenue, a mix of about 60% commercial aerospace, 20% defense and 20% power and other, about 6,600 employees, and about $200 million of expected net synergies.
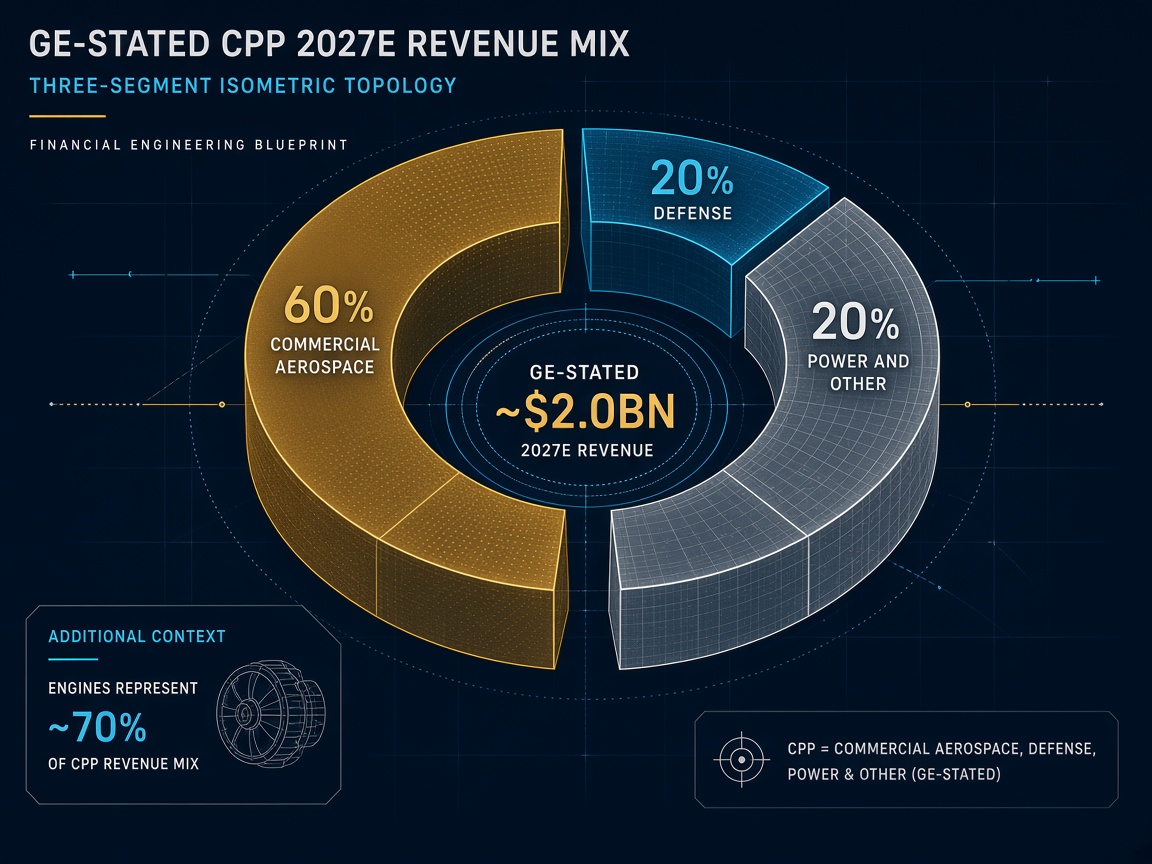
Keep the labels. The $2.0 billion figure is estimated 2027 revenue, not a trailing audited number in the announcement. About 70% of revenue is described as coming from commercial and defense engines, with the remainder primarily missiles and power. Employees are about 6,600 across more than 20 facilities. Those operating facts are GE’s overview of CPP, not an Acquiry reconstruction.
If the $11.75 billion purchase price is set against the $2.0 billion 2027E revenue figure, the arithmetic is about 5.9x 2027E revenue ($11.75bn ÷ $2.0bn). That is an Acquiry observation from two GE-disclosed figures with different natures: a cash purchase price and an estimated forward revenue. It is not a company-published revenue multiple, and it is not a substitute for the EBITDA multiples GE did publish.
GE Aerospace itself reports an installed base of approximately 50,000 commercial and 30,000 military aircraft engines, and about 57,000 employees. Those are buyer-side scale markers from the same press release. They explain why a casting bottleneck matters: the installed base and the new-build and aftermarket work that sits on it both need airfoils.
GE-stated CPP 2027E revenue mix
| Segment | Share | Label |
|---|---|---|
| Commercial aerospace | ~60% | GE-stated |
| Defense | ~20% | GE-stated |
| Power and other | ~20% | GE-stated |
| 2027E revenue | ~$2.0bn | GE-stated estimate |
GE Aerospace Exhibit 99.1 investor presentation, 8 September 2026.
05 · Capability
06 · Deal Intelligence
How the casting stack fits
CPP’s disclosed product set is highly engineered airfoils and structural castings across titanium, superalloy and soft metal, docking into GE Aerospace propulsion programs and FLIGHT DECK operating methods.
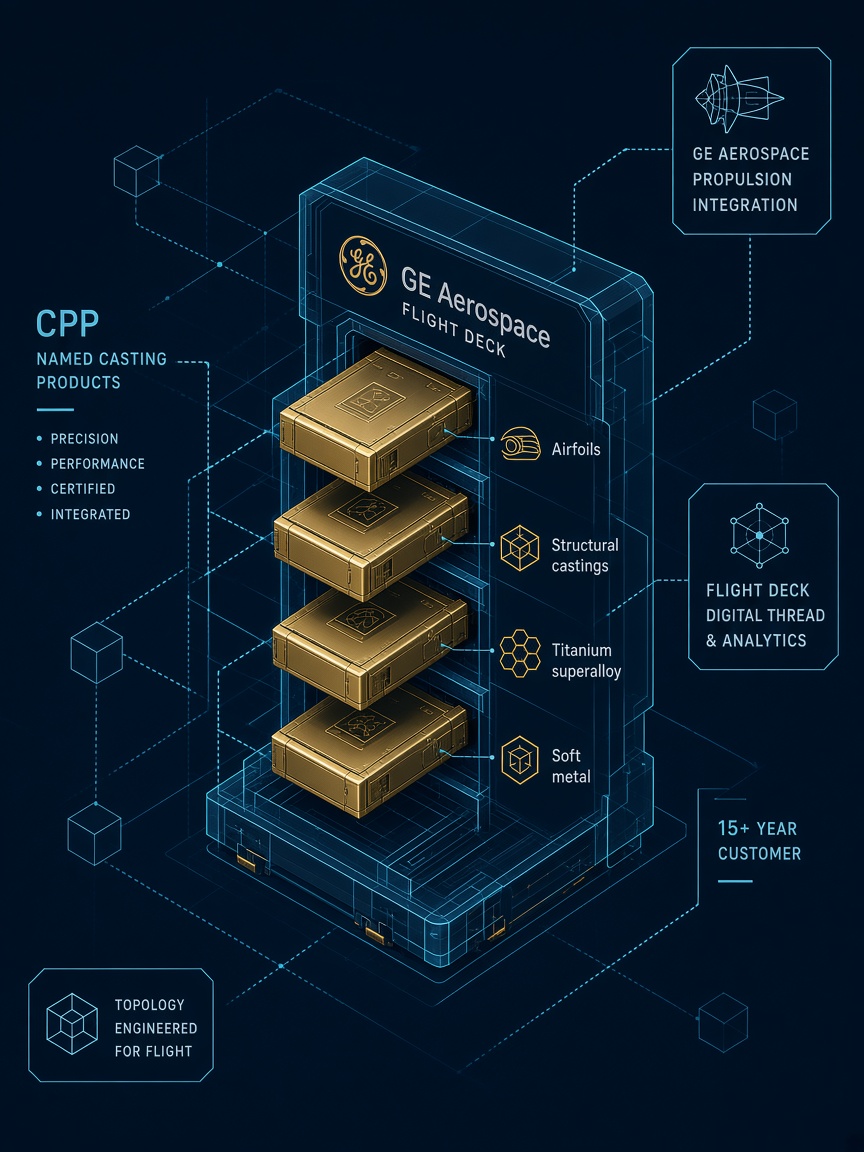
Under the hood, the acquisition is a manufacturing readiness purchase. GE says enhanced proprietary airfoil technology enables cooler metal temperatures, supporting durability and efficiency, and that the technology applies to current engines such as LEAP as well as next-generation platforms. Owning CPP is meant to shorten the path from design to manufacturable ramp by connecting design data with casting capacity.
FLIGHT DECK is the operating system GE wants to push harder inside CPP. The IR note is specific about the levers: process and quality improvements, higher output, additional jobs to support deployment, and continued reliance on other partners and suppliers. GE is not claiming CPP replaces the rest of the castings supply chain. It is claiming CPP is part of the solution while GE deepens technical and operational relationships elsewhere.
Precedent inside GE’s own manufacturing family is Avio Aero, Unison and Dowty, named in the presentation as a proven model that still serves external customers. That is GE describing a playbook it already runs on other industrial assets, not a promise that CPP will look identical on day one.
06 · Close
07 · Deal Intelligence
How the combination could work
The deal was signed on 8 September 2026. Close is expected in the second half of 2027, subject to regulatory approvals and customary conditions, then FLIGHT DECK deployment and capacity investment.
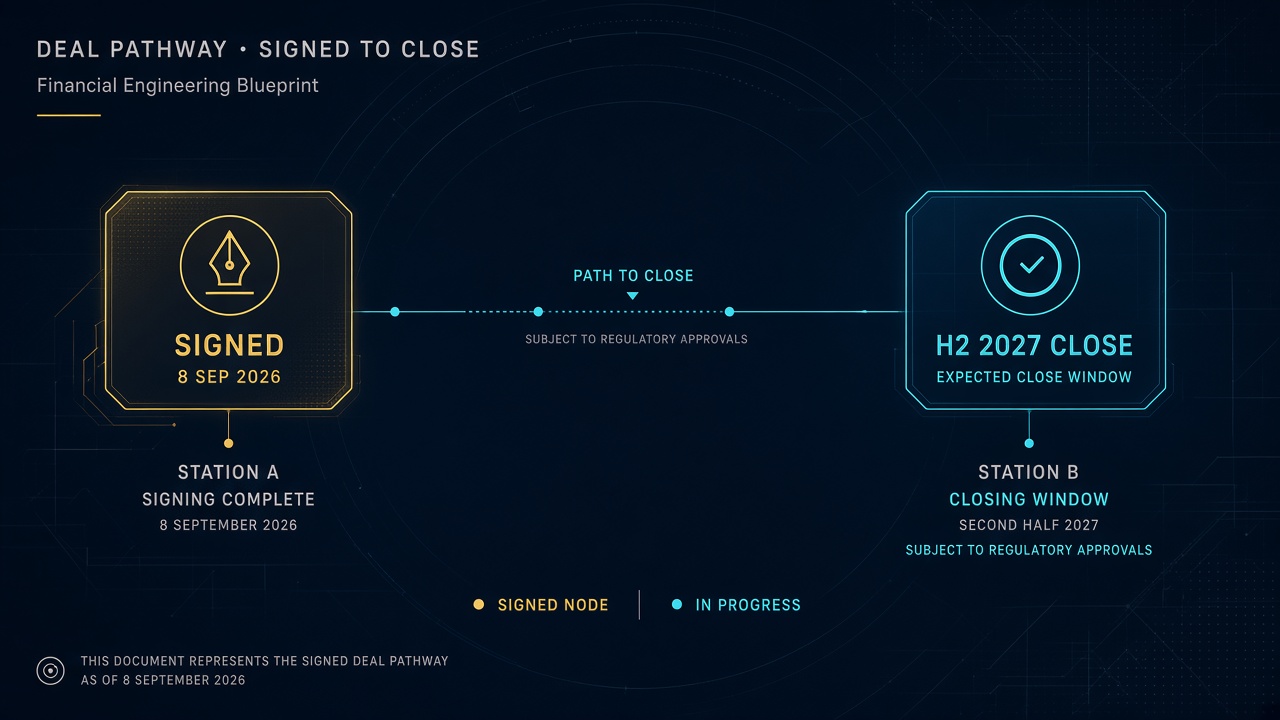
The announcement does not publish a named agency list, a reverse termination fee, or an outside date beyond the H2 2027 expectation. Until those appear in a fuller filing, the live calendar is the one GE did publish. After close, the operating sequence in the company materials is capacity, FLIGHT DECK, and readiness for enhanced airfoil technology, with incremental planned capital investments over time.
Later reporting added a useful boundary. On 17 September, Reuters quoted CFO Rahul Ghai calling the CPP deal a unique situation and saying GE does not see broad vertical integration as the answer to every aerospace supply-chain constraint. That is management narrowing the thesis after announcement: own this bottleneck, do not assume every part of the value stream follows.
- Signed8 Sep 2026. Definitive agreement announced from Cincinnati.
- Financing$7bn cash + new debt. Remainder Acquiry-calculated at $4.75bn from disclosed inputs.
- ApprovalsPending. Close targeted for H2 2027, subject to regulatory and customary conditions.
- Operating pathPost-close. FLIGHT DECK deployment, capacity investment, enhanced airfoil readiness.
07 · View
08 · Deal Intelligence
Acquiry view
Acquiry view. GE Aerospace is buying control of a castings bottleneck it already sits on as a customer. The $11.75 billion cash purchase price is large because the constraint is industrial, not cosmetic. The financing split is clean. The multiple language is GE’s own, and the 18x-with-synergies print only works if the $200 million net-synergy machine and the FLIGHT DECK yield story arrive.
The best companies are acquired, not sold. Warburg Pincus and Berkshire Partners are exiting a scaled casting platform into a strategic that needs the parts. If H2 2027 close holds, GE owns a piece of the supply chain that decides how fast LEAP, GEnx and the defense book can actually ship metal. That is the deal.
Sources
09 · Deal Intelligence
Sources and methodology
Primary GE disclosures and the furnished 8-K materials rank above reporting. Calculations use disclosed inputs and are labelled. Adjusted EPS, free cash flow and EBITDA multiples remain GE’s non-GAAP framing where the company says so.
- 1.01GE Aerospace IR update, 8 September 2026 (opens in a new tab)Primary
- 2.02GE Aerospace Form 8-K / RNS PDF (Exhibits 99.1 and 99.2), 8 September 2026 (opens in a new tab)SEC
- 3.03Reuters, 9 September 2026 (opens in a new tab)Reported
- 4.04StockTitan filing mirror, GE 8-K, 8 September 2026 (opens in a new tab)SEC
- 5.05Reuters, 17 September 2026 (opens in a new tab)Reported
- 6.06GE Aerospace corporate site (opens in a new tab)Primary
- 7.07Warburg Pincus (opens in a new tab)Seller
- 8.08Acquiry Deal Intelligence calculationsAcquiry
Method: Acquiry Deal Intelligence methodology. Acquiry was not engaged by any party. Nothing here is investment advice.
Keep reading
Related analysis
Deal Intelligence · Industrials
Schneider to Buy Smart Device Firm Shelly in $1.4 Billion Deal
Schneider Electric, via SE 2026 A SAS, intends a voluntary public takeover of Shelly Group at EUR 70.00 per share, with a 95% acceptance threshold and Bulgarian FSC clearance still ahead.
Deal Intelligence · Industrials
Telix to Acquire ITM for $1.65bn and Own the Radioisotope Stack
Telix will acquire 100% of ITM for US$1.65bn cash-free/debt-free, mostly in shares, plus up to US$700m of ITM-11 milestones. Close is targeted by the end of 2026.
Deal Intelligence · Industrials
Madison Air Acquires ebm-papst and Builds a Global Airflow Platform From the Component Up
Madison Air’s acquisition of ebm-papst: €5.1bn enterprise value, 14.6x forecast 2026 adjusted EBITDA, $160m run-rate synergy plan and the industrial logic behind a cross-border airflow platform.
About the analyst

Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.