What Telix is buying
Telix is buying 100% of ITM: a commercial-scale lutetium-177 manufacturer with a 65-country distribution net, plus a late-stage neuroendocrine therapeutic that has finished one Phase 3 trial.
| Node | Disclosed fact |
|---|---|
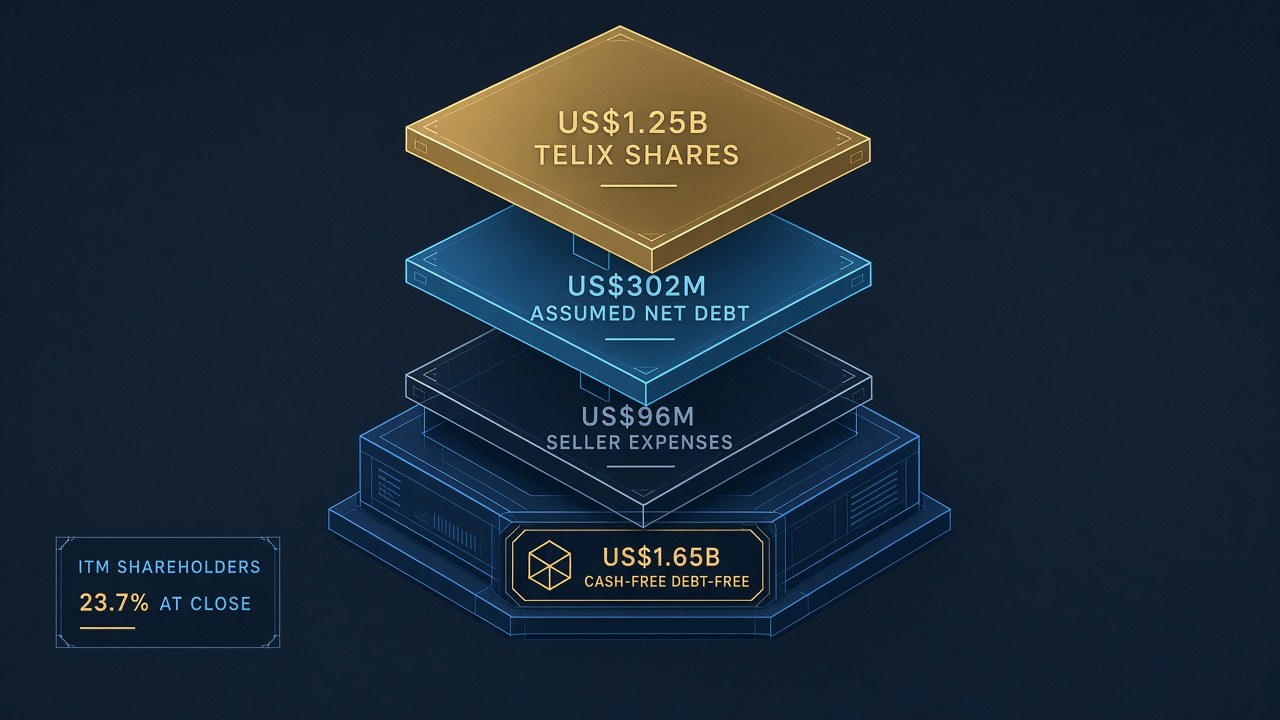
| Share consideration | US$1.25 billion in 105.8 million Telix shares at US$11.84 |
| Assumed net debt | US$302 million |
| Seller rollover and expenses | US$96 million, payable by the sellers |
| Upfront | US$1.65 billion cash-free/debt-free |
| ITM ownership at close | 23.7% of Telix shares on issue |
ITM was founded in 2004. It is private. The announcement describes an end-to-end radioisotope business: raw materials and irradiation, GMP production of non-carrier-added lutetium-177, quality-control release and specialist logistics into more than 65 countries. Telix says ITM is the world’s largest supplier of 177Lu by revenue, a primary external supplier of lutetium for Novartis’s Pluvicto, and a contracted supplier to other commercial and clinical customers. That is a manufacturing franchise sitting next to Telix’s existing precision-medicine commercial book, not a discovery-stage bolt-on.[1][2]
The second asset is ITM-11 (177Lu-edotreotide), a somatostatin-receptor agonist aimed at gastroenteropancreatic neuroendocrine tumours. COMPETE, the first Phase 3 trial, is complete and was published in The Lancet on 2 July 2026. COMPOSE, a second Phase 3 in more aggressive Grade 2–3 disease, has finished enrolment. A lung-NET study, LEVEL, is about 90% enrolled. None of those programmes is approved. The FDA sent a complete response letter on 7 August 2026 limited to chemistry, manufacturing and controls and a third-party facility inspection. No additional clinical or nonclinical data were requested. Resubmission of that NDA, or a path to resubmission that Telix accepts, is a closing condition.[1][2][5]
Control is straightforward. Telix acquires all outstanding issued equity securities of ITM. After close, existing Telix shareholders own about 76.3% and ITM shareholders own about 23.7% of Telix shares on issue. Shares issued as upfront consideration come out as Nasdaq ADRs after staggered escrow of up to 15 months. Founders and key executives are locked until the earlier of three months after the first FDA milestone and 15 months after closing. Other ITM holders are locked until the earlier of that first milestone and 12 months. Limited waiver language lets sellers cover tax and transaction expenses.[1][2]
How the price is built
Upfront is US$1.65 billion cash-free/debt-free, almost all in Telix paper plus assumed net debt. Up to US$700 million more is payable only if ITM-11 clears named FDA gates and a FY 2030 sales formula.
| Gate | Disclosed fact |
|---|---|
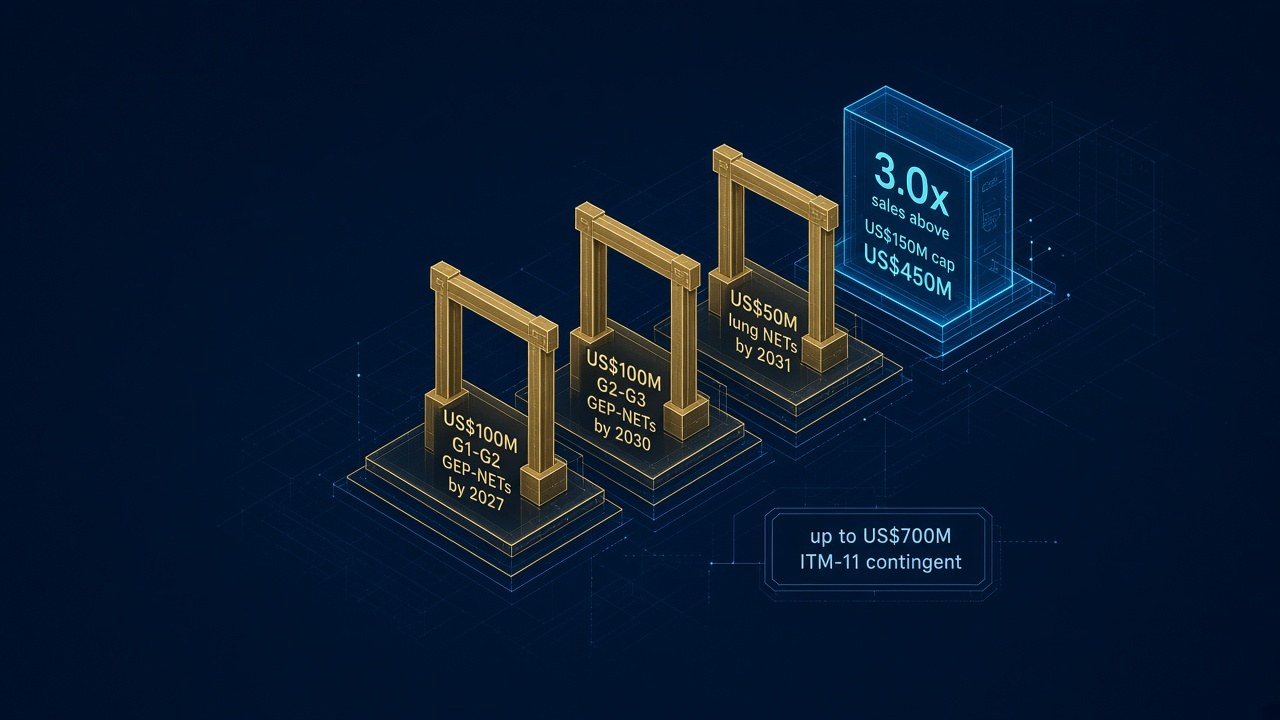
| Milestone 1 | US$100 million on FDA approval for G1-G2 GEP-NETs by 31 December 2027 |
| Milestone 2 | US$100 million on FDA approval for G2-G3 GEP-NETs by 31 December 2030 |
| Milestone 3 | US$50 million on FDA approval for lung NETs by 31 December 2031 |
| Sales milestone | 3.0x ITM-11 global net sales in FY 2030 above US$150 million, capped at US$450 million |
| Contingent cap | Up to US$700 million, cash or Telix shares at Telix’s election |
Add the three disclosed upfront lines and you get US$1.648 billion (US$1.25bn + US$302m + US$96m). That is an Acquiry arithmetic check on Telix’s own split, sitting US$2 million under the US$1.65 billion cash-free/debt-free headline, which the presentation flags as subject to closing adjustments for cash, expenses, net working capital and debt. It is not a second price. The US$11.84 share price is the 30-day trailing VWAP on the ASX before signing, A$16.65 converted at AUD/USD 0.71. Exact share count can still move with those adjustments.[2][8]
Headline coverage that prints “US$2.35 billion” is adding the US$1.65 billion upfront to the US$700 million contingent cap. That sum is an Acquiry observation about two disclosed ceilings (US$1.65bn + US$700m), not a cash cheque and not an enterprise value. Telix did not publish an EV/EBITDA multiple. Combined 2025 adjusted EBITDA on the pro forma page is a US$6 million loss. This article does not turn that loss into a purchase multiple.[2][8]
The sales milestone is a formula, not a hope. Telix pays 3.0 times ITM-11 global net sales in FY 2030 in excess of US$150 million, up to US$450 million. Hitting the cap therefore requires US$150 million of excess sales, or US$300 million of FY 2030 ITM-11 net sales (US$150m + US$450m ÷ 3.0). That US$300 million figure is an Acquiry illustration of the disclosed formula, not a company forecast. All milestone consideration is payable in cash or shares, with share settlement at the 30-day VWAP when the milestone hits, converted to Nasdaq ADRs. If shareholders do not approve the milestone share issues, Telix must pay those milestones in cash.[2][8]
Chart data
| Item | Value | Label |
|---|---|---|
| Telix shares to sellers | 1,250 | Disclosed |
| Assumed net debt | 302 | Disclosed |
| Seller rollover and expenses | 96 | Disclosed |
| Upfront cash-free / debt-free | 1,650 | Disclosed |
| Parts sum | 1,648 | Acquiry calculation |
| ITM-11 contingent cap | 700 | Disclosed; not in the upfront |
Telix announcement and ASX investor presentation, 21 September 2026. Parts sum is an Acquiry arithmetic check.
Why the businesses fit
Telix already sells precision-medicine imaging. ITM already makes and ships the therapeutic isotope. Putting them in one group is a supply-chain purchase with a neuroendocrine overlay, not a new geography.
| Node | Disclosed fact |
|---|---|
| Telix | Precision-medicine commercial platform |
| ITM | Isotope GMP manufacturing and distribution |
| ITM 2025 revenue | US$273 million audited |
Radiopharmaceuticals have a half-life problem. Lutetium-177 does not sit in a warehouse waiting for a better price. ITM’s disclosed operating claim is just-in-time delivery: 24 to 48 hours inside the EU and US, 72 hours across 65 countries, more than 400 destinations a week, and a 2025 order-fulfilment rate above 99%. Telix already needs that isotope for late-stage assets it names as TLX591-Tx, TLX597-Tx and TLX250-Tx. Buying the supplier is how a therapeutics company stops being a customer in a tight irradiation market.[2]
The pipeline overlay is complementary rather than duplicative on the disclosed map. Telix’s late-stage work sits in prostate, brain, neuroendocrine and renal cancers. ITM-11 is a GEP-NET therapeutic that has already run a head-to-head Phase 3 against everolimus. COMPETE reported median progression-free survival of 23.9 months versus 14.1 months, a stratified hazard ratio of 0.673, and fewer Grade 3/4 treatment-related adverse events (18% versus 40%). That is a published clinical result, not a marketing claim, and it still has to survive CMC remediation after the August CRL.[2][5]
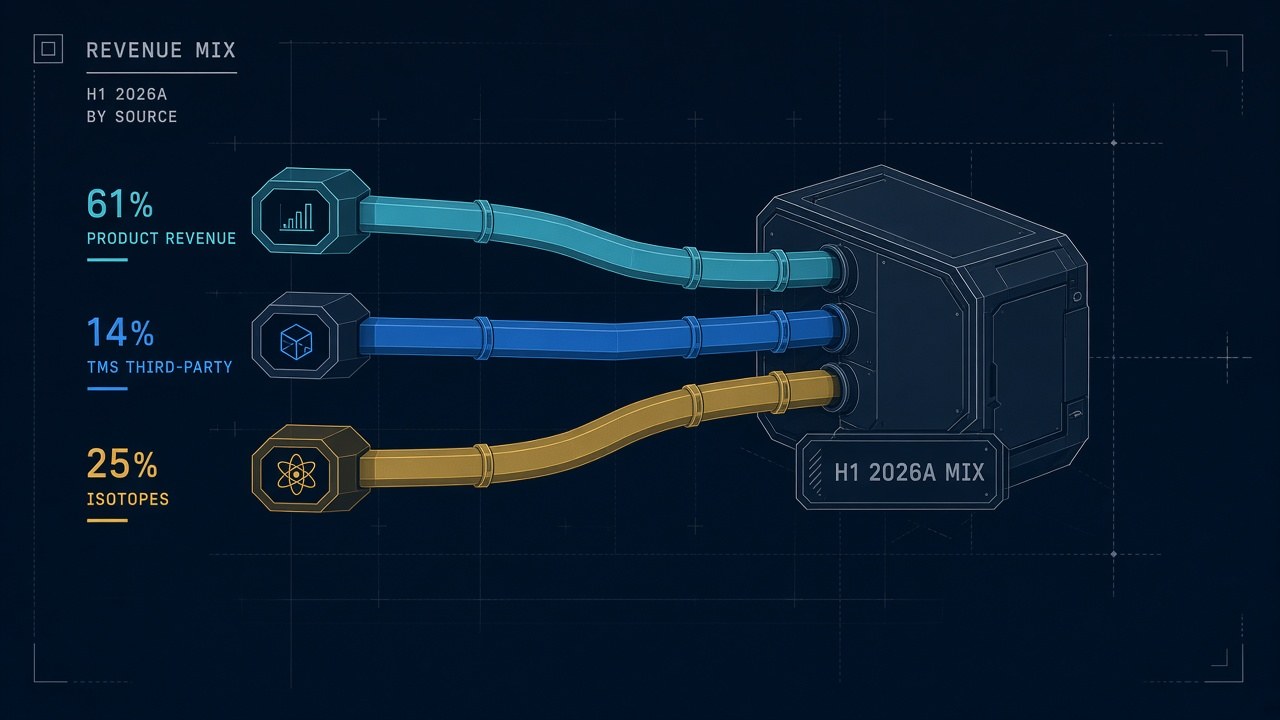
H1 2026A combined mix, as Telix draws it, is 61% product revenue, 14% TMS third-party revenue and 25% isotopes. Manufacturing is the profit engine ITM is being paid for: the presentation says ITM’s manufacturing division is expected to generate FY 2026 annualized EBITDA of US$106 million, from unaudited H1 figures. Telix also says ITM should be EBITDA-positive for the group from FY 2027, subject to targeted synergies and commercial timing, excluding one-off implementation costs. Those 2026 and 2027 figures are company estimates, not trailing audited EBITDA.[2]
| Stream | Disclosed fact |
|---|---|
| Product revenue | 61% of H1 2026A combined mix |
| TMS third-party revenue | 14% |
| Isotopes | 25% |
How the isotope stack sits together
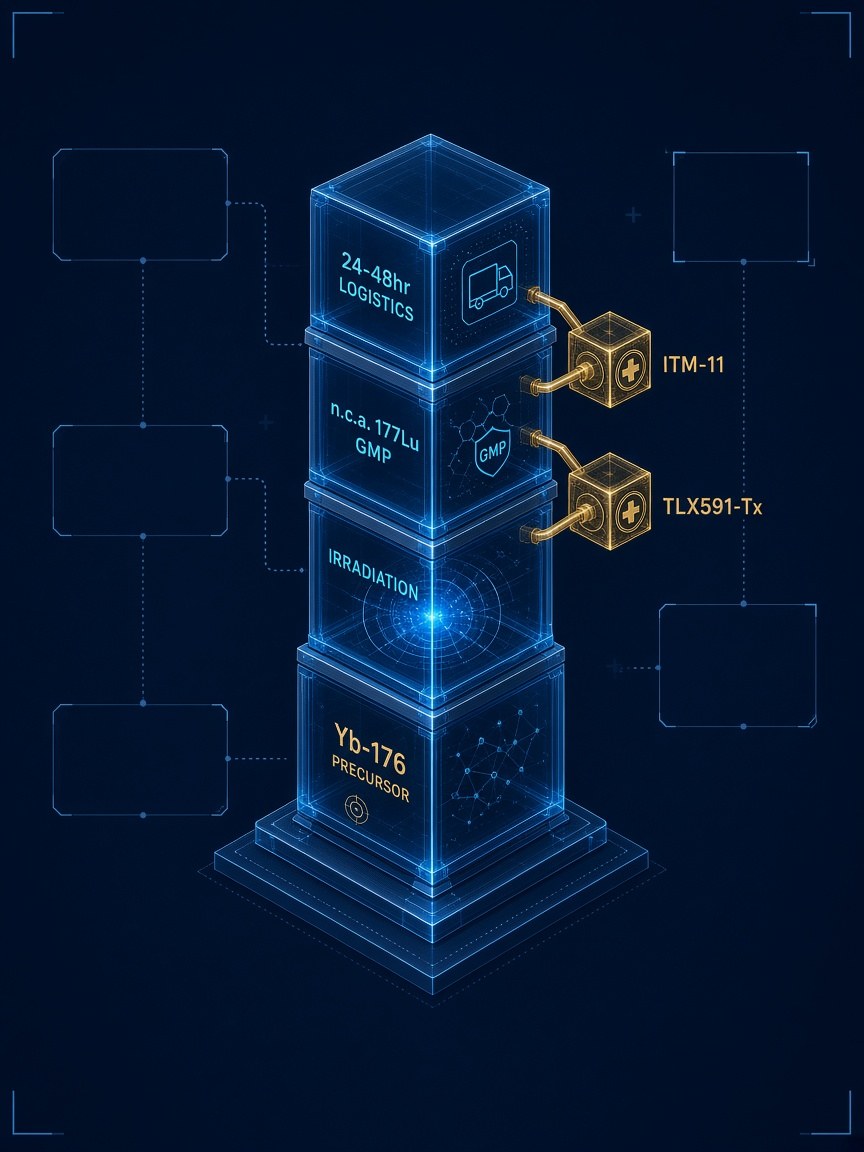
ITM starts with ytterbium, irradiates it, and releases medical-grade lutetium-177 on a 24-hour clock. Telix is plugging that factory into drugs it already has in the clinic.
| Layer | Disclosed fact |
|---|---|
| Precursor | Large stockpile of non-restricted ytterbium-176 with exclusive supply agreements |
| Irradiation | Exclusive 24/7/365 Isogen agreement using Bruce Power reactors |
| GMP product | Non-carrier-added lutetium-177, commercially scaled |
| Logistics | 24–48 hours in EU/US; 72 hours across 65 countries |
| Docked programmes | ITM-11; Telix TLX591-Tx among named late-stage assets |
The scarce inputs are the ones Telix chose to name. ITM holds a large stockpile of non-restricted ytterbium-176 with exclusive supply agreements, and an exclusive Isogen irradiation contract that Telix describes as 24/7/365 access to Bruce Power reactors. Proprietary production includes recycling for cost efficiency. In-house and partner GMP sites, two of them on the 2025 snapshot, are the capacity claim. This is a regulated production network, not a software integration.[2]
Next-generation isotopes sit on the same chassis. Actinium-225 is an Actineer joint venture with exclusive long-term access to radium-226 precursor from Canadian Nuclear Laboratories. Telix says ITM is positioned to be one of the first commercial suppliers of GMP-grade 225Ac. Terbium-161 is earlier: a future growth line using the same manufacturing playbook, with industry interest in prostate cancer. Those are disclosed development directions, not commercial products today.[2]
ITM-11 is the near-term therapeutic on that lutetium column. It pairs edotreotide with n.c.a. 177Lu for SSTR-positive GEP-NETs. Telix cites a US$1.7 billion U.S. addressable market on a management estimate of about US$210,000 per patient, and about US$800 million of current global annual sales for approved SSTR-targeted radioligand therapies. Those are labelled market figures, not ITM-11 forecasts. COMPOSE’s next catalyst is a second interim analysis expected in the first half of 2027. LEVEL’s interim is expected in the second half of 2027.[1][2]
Low-friction path: keep ITM’s isotope customers, including the Pluvicto supply relationship, while Telix’s own late-stage assets stop competing for third-party lutetium. High-friction path: customer concentration in the isotope book, or a delayed NDA resubmission, turns a manufacturing acquire into a pipeline wait. The SPA already prices that second risk through the contingent cheque and the resubmission closing condition.[2]
What the numbers say
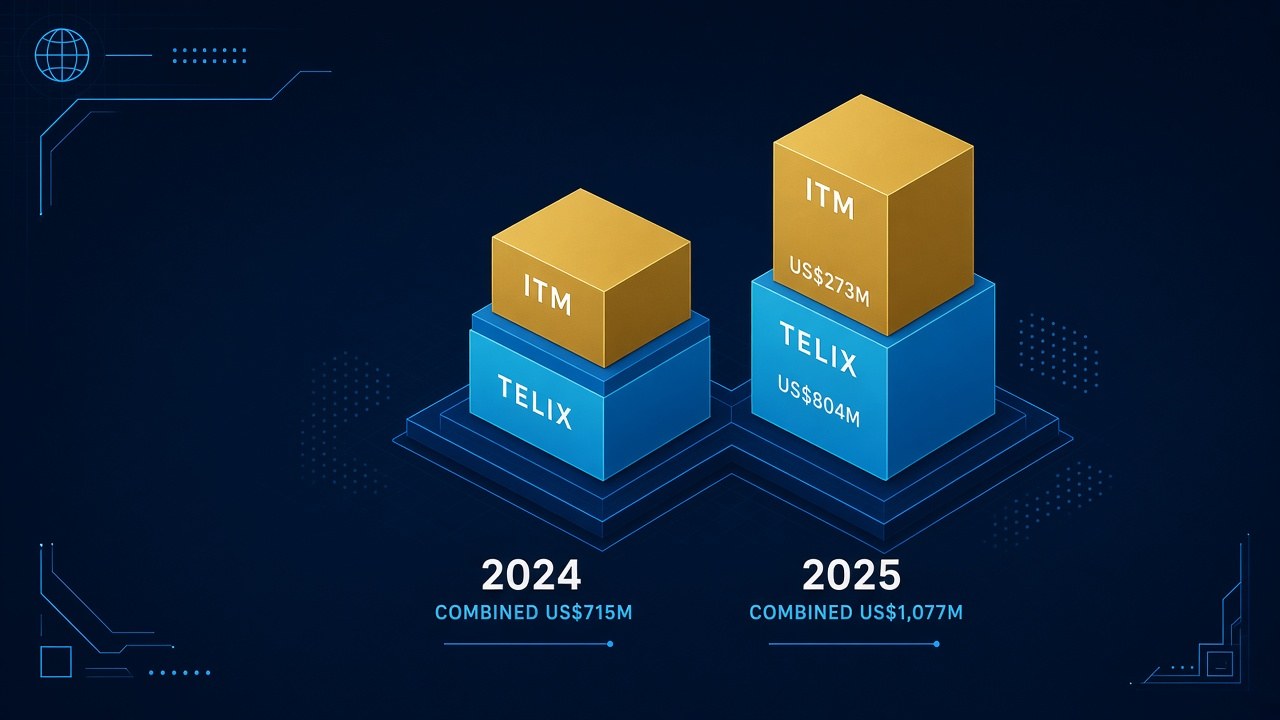
Audited 2025 combined revenue is US$1,077 million. ITM contributed US$273 million of that and turned manufacturing into a US$77 million adjusted-EBITDA line. 2026 combined revenue above US$1.3 billion is a management estimate.
| Year | Disclosed fact |
|---|---|
| 2024 combined revenue | US$715 million pro forma |
| 2025 Telix revenue | US$804 million audited |
| 2025 ITM revenue | US$273 million audited |
| 2025 combined revenue | US$1,077 million pro forma, excludes targeted synergies |
Keep the labels on the income statement. Telix reports under IFRS. ITM reports under IFRS as adopted by the EU. ITM dollar figures are translated at EUR/USD 1.14. Combined columns exclude targeted synergies. On that basis, 2025 combined gross profit is US$545 million, combined operating profit is a US$27 million loss, and combined adjusted EBITDA is a US$6 million loss. Split by Telix’s own segments, 2025 manufacturing adjusted EBITDA is a US$55 million profit because ITM’s manufacturing line printed US$77 million against Telix’s manufacturing loss of US$22 million. Precision medicine remains the Telix profit centre at US$216 million of 2025 adjusted EBITDA. Therapeutics remains the drain.[2]
H1 2026, unaudited, is the run-rate Telix wants you to see. Combined revenue US$633 million. Combined adjusted EBITDA US$40 million, of which ITM’s H1 figure excludes a US$19 million once-off cost on a loan reassignment. ITM H1 2026 revenue was US$156 million. Annualising that unaudited half gives about US$312 million, which sits next to Telix’s comment that ITM revenue is expected around US$300 million in 2026. Telix 2026 revenue guidance at the upper end is US$970 million plus US$40 million of other income. Adding those company figures is how Telix reaches combined 2026 revenue and income exceeding US$1.3 billion. That is a management construct, not an audited year.[2]
The balance sheet at 30 June 2026, unaudited, shows combined cash of US$325 million, combined borrowings of US$685 million and combined net assets of US$746 million, before at-acquisition intangibles. Telix cites a combined pro forma market capitalisation of US$5.3 billion “based on deal size.” Synergies are a Telix target of US$50 million in the first two years, on top of an ITM cost-saving programme aimed at returning operating costs to FY 2025 levels. Those US$50 million are a target, excluding one-off integration costs.[2]
Chart data
| Item | 2024 | 2025 | Label |
|---|---|---|---|
| Telix revenue | 517 | 804 | Audited, as reported |
| ITM revenue | 198 | 273 | Audited; EUR/USD 1.14 |
| Combined revenue | 715 | 1,077 | Pro forma, excludes synergies |
| Combined adjusted EBITDA | (22) | (6) | Pro forma, non-IFRS |
| ITM manufacturing adj. EBITDA | 8 | 77 | Segment line inside combined |
Telix ASX investor presentation, 21 September 2026, full-year pro forma income statement. Adjusted EBITDA is the companies’ non-IFRS measure.
How the combination could work
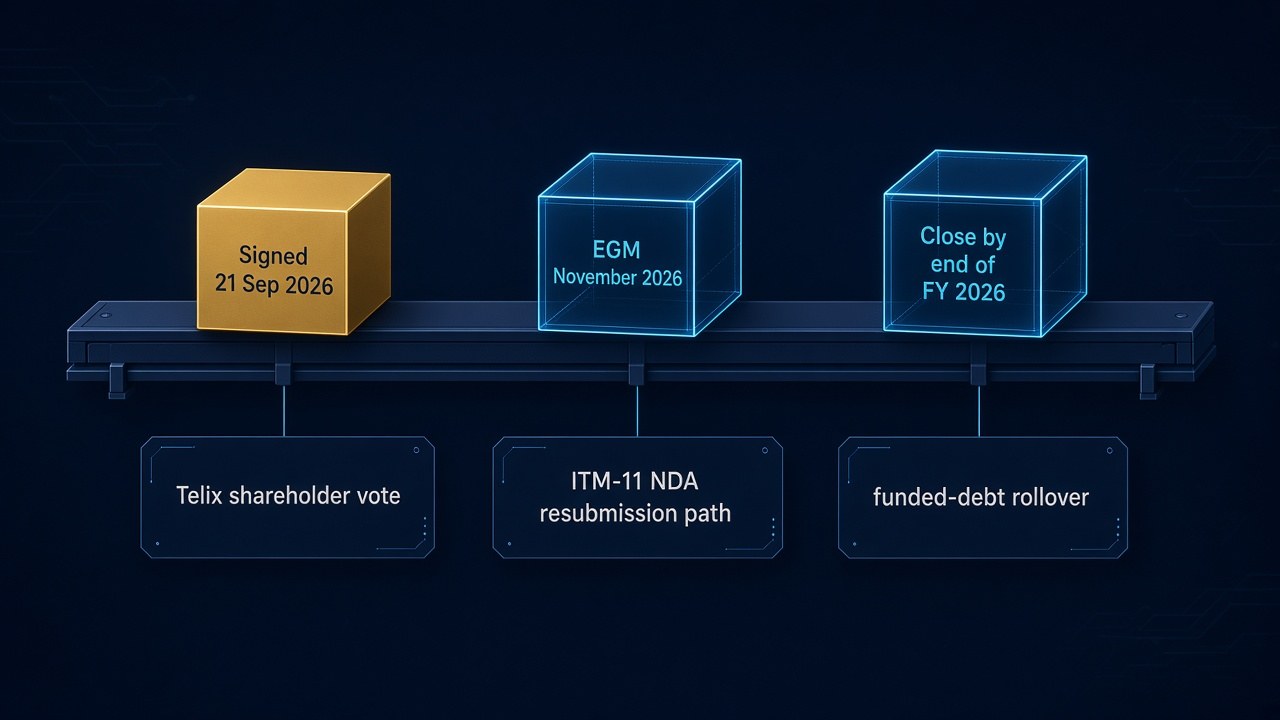
Close is targeted by the end of 2026 after a November EGM. The live conditions are a Telix share-issue vote, an ITM-11 resubmission path, and a rollover of ITM’s funded debt. Distribution is already global; the work is keeping it that way.
| Node | Disclosed fact |
|---|---|
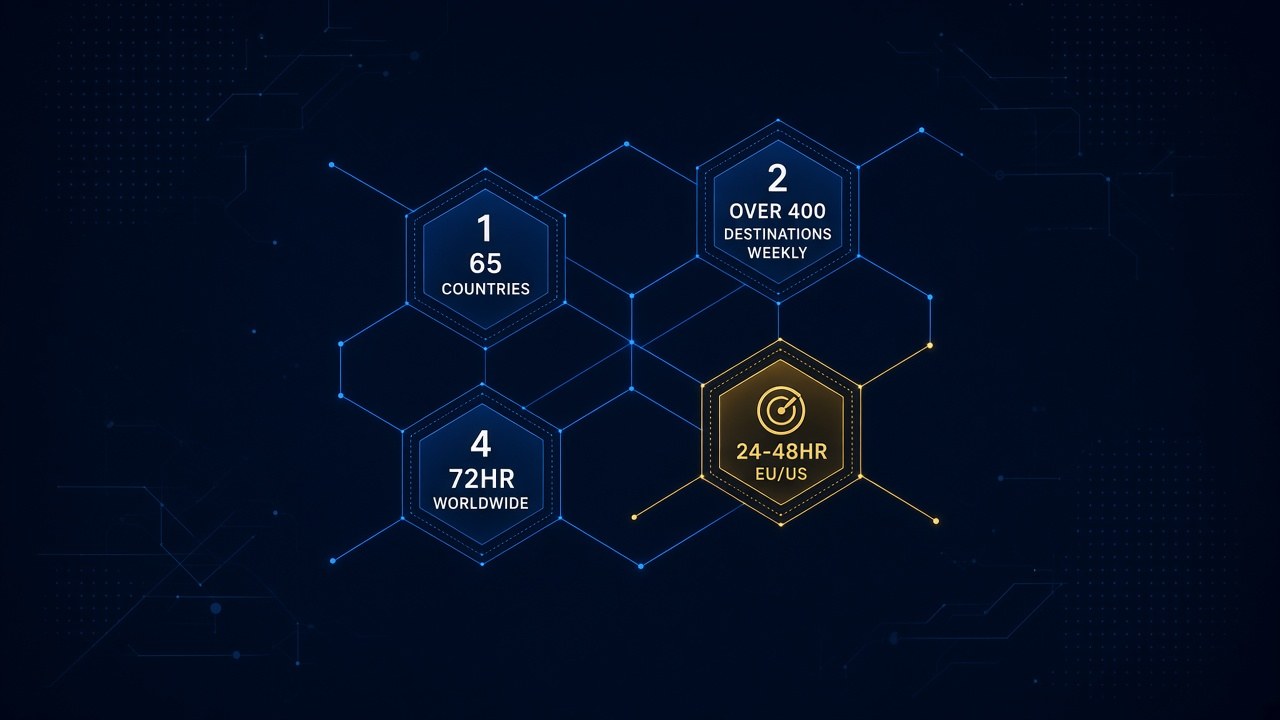
| Coverage | 65 countries |
| Weekly destinations | More than 400, including distributor-managed sites |
| EU/US delivery | 24–48 hours |
| Wider delivery | 72 hours across 65 countries |
| Stage | Disclosed fact |
|---|---|
| Signed | 21 September 2026 |
| EGM | Expected November 2026, Telix share issue for upfront consideration |
| Close | Targeted by end of FY 2026 |
| Vote-failure fee | US$5 million if Telix shareholders do not approve the upfront share issue |
| End date | 31 December 2026, extendable three months for regulatory delays |
Telix will ask shareholders for three things at the EGM: the upfront share issue, maximum share issues for each milestone, and the appointment of Dr Cavey and Dr Barbara Weber to the board from closing. Failure to pass the upfront share issue kills the transaction and can trigger a US$5 million shareholder-vote failure fee, on top of adviser costs already incurred. Other Telix closing conditions include satisfactory rollover of ITM’s funded debt, FDA resubmission of ITM-11 or an agreed path, pre-closing operational covenants, continuing accuracy of ITM’s representations, and no material adverse event. The stated end date is 31 December 2026, extendable by three months only for regulatory delays.[2]
Operating sequence after close is the unglamorous part. Identified key employees are to sign employment and retention agreements before closing. One ITM director plus the current CEO join the Telix board, subject to the vote. Telix has taken representation and warranty insurance, with the usual cap, timing and carve-out limits. Escrow, indemnity holdbacks and contingent payments are the rest of the risk stack. None of that is a Day-1 brand merge. The customers who already take lutetium on 24-hour clocks will notice a missed batch sooner than a new logo.[1][2]
- Telix share-issue voteEGM expected November 2026. Required for close. US$5m fee if it fails.
- ITM-11 NDA pathCRL 7 August 2026, CMC only. Resubmission or an agreed path is a closing condition.
- Funded-debt rolloverITM net debt US$302m at the disclosed split. Satisfactory rollover is a Telix condition.
- Isotope continuity65 countries, 400-plus weekly destinations. Keep the Pluvicto and clinical supply clocks intact.
Acquiry view
Acquiry view. Telix is buying the isotope factory that already feeds the radioligand market, and it is paying for ITM-11 only if the FDA and FY 2030 sales show up. The US$1.65 billion cash-free/debt-free upfront is mostly Telix paper and assumed debt. The US$700 million cap is a set of gates, not a second cheque written today. That is a disciplined way to buy a scarce manufacturing network when the late-stage therapeutic still has a CMC letter on the file.
The best companies are acquired, not sold. ITM shareholders keep 23.7% of the combined register, which is not walking away. Telix is identifying a specific capability, commercial-scale n.c.a. lutetium with a 65-country clock, and folding it under a precision-medicine group that already needs the isotope. If manufacturing keeps printing the cash Telix is modelling for 2026 and 2027, this is that purchase. If ITM-11 later clears the FDA gates, Telix will have paid for the growth it actually received.
Sources and methodology
Primary Telix and ITM disclosures rank above reporting. Calculations use disclosed inputs. Adjusted EBITDA remains the companies’ non-IFRS label. 2026 combined revenue above US$1.3 billion is a management estimate.
- 01Telix announcement, 21 September 2026Primary
- 02Telix ASX investor presentation, 21 September 2026ASX
- 03Telix ASX announcement PDF, 21 September 2026ASX
- 04ITM press release, 21 September 2026Primary
- 05Walter T, et al., The Lancet, 2 July 2026 (COMPETE; cited in the Telix presentation)Journal
- 06Telix Form 6-K coverage of the transaction termsSEC
- 07ClinicalTrials.gov NCT03049189, COMPETERegistry
- 08Acquiry Deal Intelligence calculationsAcquiry
Method: Acquiry Deal Intelligence methodology. Acquiry was not engaged by any party. Nothing here is investment advice.