What Kakao Games is buying
Kakao Games' board approved a ₩98.0bn cash purchase of 16,828,508 ME2ON shares on 15 September 2026, enough to become largest shareholder at 39.56% after a new-share issue, with close aimed at 16 November.
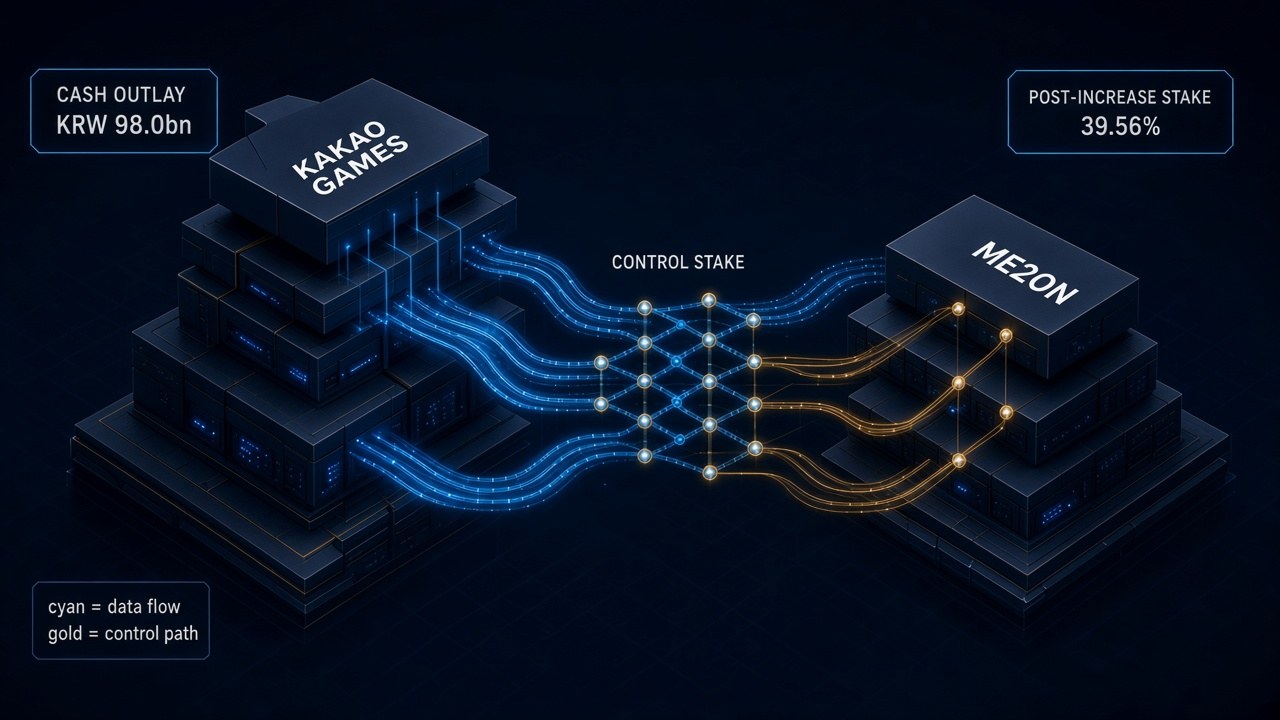
| Item | Detail |
|---|---|
| Buyer node | Kakao Games |
| Target node | ME2ON |
| Cash outlay | KRW 98.0bn |
| Stake after increase | 39.56% |
The transaction looks, in the headlines, like another Korean publisher buying another Korean game company. The filing is more specific. Kakao Games is taking a largest-shareholder seat, not swallowing the equity. The cash is split into two jobs: ₩70.1139bn for 7,011,390 existing shares from Son Chang-wook and eight related holders, and ₩27.900bn for 9,817,118 new shares issued by ME2ON itself.
Two prices, two jobs. The Elec has the existing block at ₩10,000 a share, about 3.2 times ME2ON's 14 September close of ₩3,110. The new shares are priced at about ₩2,842, 8.6% below that close. Founder cash leaves the building. Company cash stays in it. Anyone multiplying ₩98.0bn by the reciprocal of 39.56% and calling that an enterprise value is mixing those two prices. This brief does not.
ME2ON was founded in 2010 and listed on KOSDAQ in 2016. It develops and operates social casino and casual titles, with The Korea Herald putting 2025 revenue at about ₩120.9bn and operating profit at ₩12.6bn. Overseas sales are more than 80% of that. Named titles include Full House Casino and Full Pot Hold'em. The Elec also reports a later ACE Casino rail that accepts USDT. Subsidiaries include Ghost Studio and ACE Interactive Holdings Limited.
Edaily has Son selling 6.55 million shares, 20.02% of the pre-issue stock, for ₩65.5bn, with Choi Won-seok and the remaining related holders making up the rest of the 7,011,390-share block. Son and Choi stay on for three years at Kakao Games' request. Other registered directors are replaced by Kakao nominees at close. That is what "management control" looks like when you buy 39.56% rather than 100%.
Why the businesses fit
Kakao Games is buying an overseas cash engine in a genre it does not already run at this scale. ME2ON is buying a larger Korean publisher, a path toward LY Corp's Asian surfaces, and ₩27.9bn of new equity.
Kakao Games' public catalogue is still built around Korean MMORPG hits and publishing relationships. The corporate site currently lists Odin: Valhalla Rising, PUBG, Chrono Odyssey, ArcheAge War and World of Goblins. Those are live-ops, store-rank and IP problems. They are not social-casino session engines.
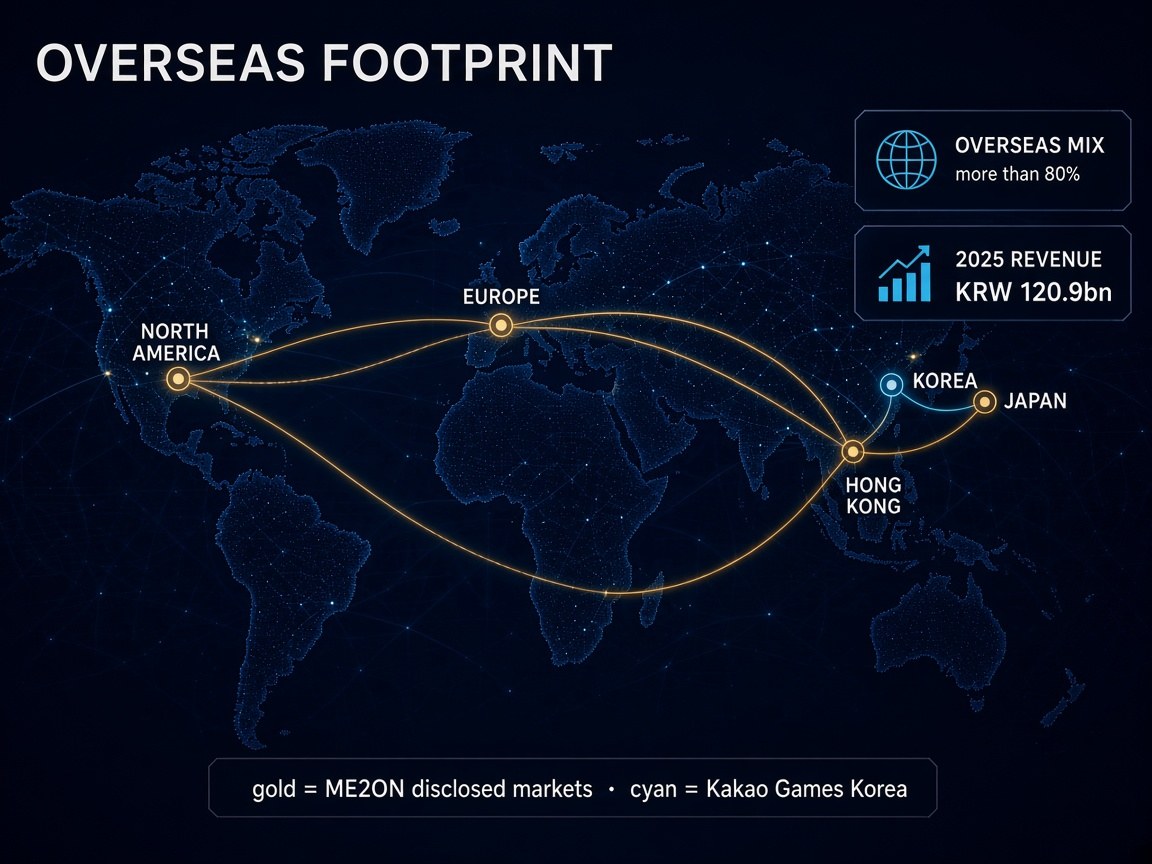
| Item | Detail |
|---|---|
| Korea | Kakao Games live MMORPG and publishing |
| Japan / Hong Kong | ME2ON Full House Casino user base |
| North America / Europe | ME2ON casual and social-casino |
| Overseas mix | ME2ON more than 80% of 2025 revenue |
ME2ON's 2025 accounts are the industrial mismatch the deal is trying to close. Revenue of ₩120.9bn, operating profit of ₩12.6bn, net income of ₩3.7bn, assets of ₩264.9bn against ₩22.7bn of liabilities, and more than 80% of sales outside Korea. Kakao Games has spent the past year telling the market it needs steadier earnings and more overseas mix. ME2ON already has both.
Timing matters. In March 2026 Kakao Games disclosed that LAAA Investment, a vehicle funded by Japan's LY Corp, would become its largest shareholder, overtaking Kakao. This is the first M&A under co-CEOs Kim Tae-hwan and Lee Si-woo. Lee told Inven the purchase is "the first step in implementing an M&A strategy focused on companies with proven business performance and profitability under our new management structure." That is a buyer saying it will keep doing this.
What ME2ON gets is equally concrete. A Korean publisher with Lionheart, XL Games and Krafton relationships. A controlling shareholder whose own controlling shareholder operates LINE and Yahoo Japan. And ₩27.9bn of new-issue cash that, unlike the ₩70.1bn founder block, lands on ME2ON's balance sheet. Son Chang-wook called Kakao Games a "strategic partner" with domestic and international service experience. He is not walking out on close.
The ₩10,000 block price versus the ₩3,110 close is a control premium on the founder shares. It is not a take-out multiple for the whole company, because the new issue is priced the other way. The filing also puts the cash outlay at 6.82% of Kakao Games' equity. For a first deal under new owners, that is a sized cheque, not a transformative bid.
How the product stacks sit together
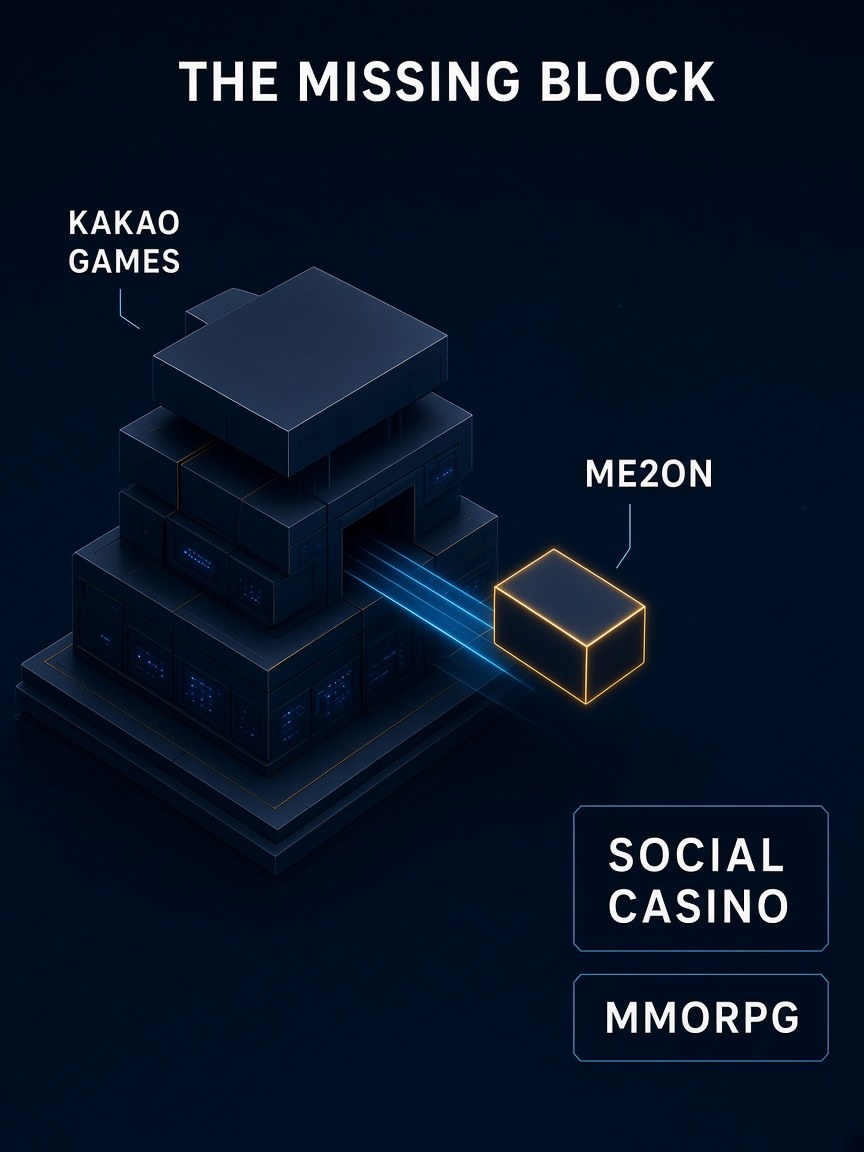
| Item | Detail |
|---|---|
| Buyer | Kakao Games MMORPG publishing |
| Missing block | ME2ON social casino |
| Fit | Control stake plus new-issue cash |
Kakao Games publishes multi-platform MMORPGs and licensed titles into app stores and PC. ME2ON runs social-casino session engines, wallet routing and a casual and mind-sports layer, with a reported USDT rail on ACE Casino.
Social casino is a session and wallet problem. Probability surfaces, engagement streams, store-policy compliance in Japan and Hong Kong, and the unglamorous work of keeping a free-to-play casino client inside platform rules. Full House Casino built that user base in Asian markets first. That is a different machine from an MMORPG live-ops calendar.
Kakao Games' stack is client-and-live-ops heavy. Lionheart Studio's Odin franchise, XL Games' ArcheAge line, and a PUBG publishing relationship with Krafton sit at the centre of the current catalogue. Those products need patch cadence, influencer spend and a hit-driven store rank. They do not already contain a social-casino probability engine or an overseas casual publishing seat of ME2ON's type.
ME2ON's disclosed operating layer is narrower and more specialised. Ghost Studio develops. ACE Interactive Holdings publishes overseas. Around the social-casino clients sit player-account ledgers, wallet routing and, more recently, the ACE Casino rail The Elec says can settle in USDT. The USDT piece is an adjacent payment path. It is not the reason Kakao Games wrote a ₩98.0bn cheque. Full House Casino-style overseas social-casino cash flow is.
Connecting the two is a portfolio and store-distribution problem before it is a shared-engine problem. Lee Si-woo also pointed to joint development with game studios in China and to ME2ON's drama, webtoon and web-novel IP. Those are options. They are not a Day-1 merge of Odin clients into a social-casino wallet. Continuity of ME2ON's live titles is the first operating requirement. Broader publishing is the second.
| Capability | Kakao Games before | ME2ON adds | Together |
|---|---|---|---|
| Genre | MMORPG and licensed publishing | Social casino, casual, mind sports | Broader live catalogue |
| Overseas mix | Korea-weighted live titles | More than 80% overseas revenue | Immediate overseas cash engine |
| Earnings quality | Turnaround brief under new owners | ₩12.6bn 2025 operating profit | A profitable division inside the group |
| Studios | Lionheart, XL Games, PUBG relationship | Ghost Studio, ACE Interactive | Studio plus overseas publishing seats |
| Distribution | KakaoTalk adjacency; LY Corp option | Hong Kong, Japan, NA, Europe users | Two different overseas routes |
| Capital | ₩98.0bn cash outlay, 6.82% of equity | ₩27.9bn new-issue proceeds | Control block plus a funded target |
Where Kakao Games can take ME2ON
Distribution leverage runs both ways, and not equally. ME2ON already sells most of its games outside Korea. Kakao Games can put those titles through a larger Korean live-ops machine, and potentially through LY Corp's LINE and Yahoo Japan surfaces.
ME2ON's named overseas weight is Asia, including Hong Kong and Japan, plus North America and Europe. That is the rare thing in this pairing: a Korean-listed game company whose revenue mix is already inverted. Kakao Games has been explicit that it wants more of that mix. Buying a company that already earns it is faster than hoping the next Odin sequel does the job alone.
KakaoTalk-adjacent Korean users are a ME2ON opportunity it did not have under a founder-led register. LINE and Yahoo Japan, if LY Corp's ownership ever becomes a distribution conversation rather than a capital one, are a Kakao Games opportunity ME2ON could not book by itself. Neither channel is an announced attach sale. Both are why a 39.56% control seat is more useful than a passive stake.
Buying control of a cash-generating operator, rather than 100% of a studio, is a pattern this series has already briefed. GiG's purchase of 888AFRICA was a control stake in a B2C engine. Same industrial shape, different continent. Kakao Games is doing the Korean-listed version: keep the target listed, keep the founder for three years, inject capital, take the board.
How the combination could work
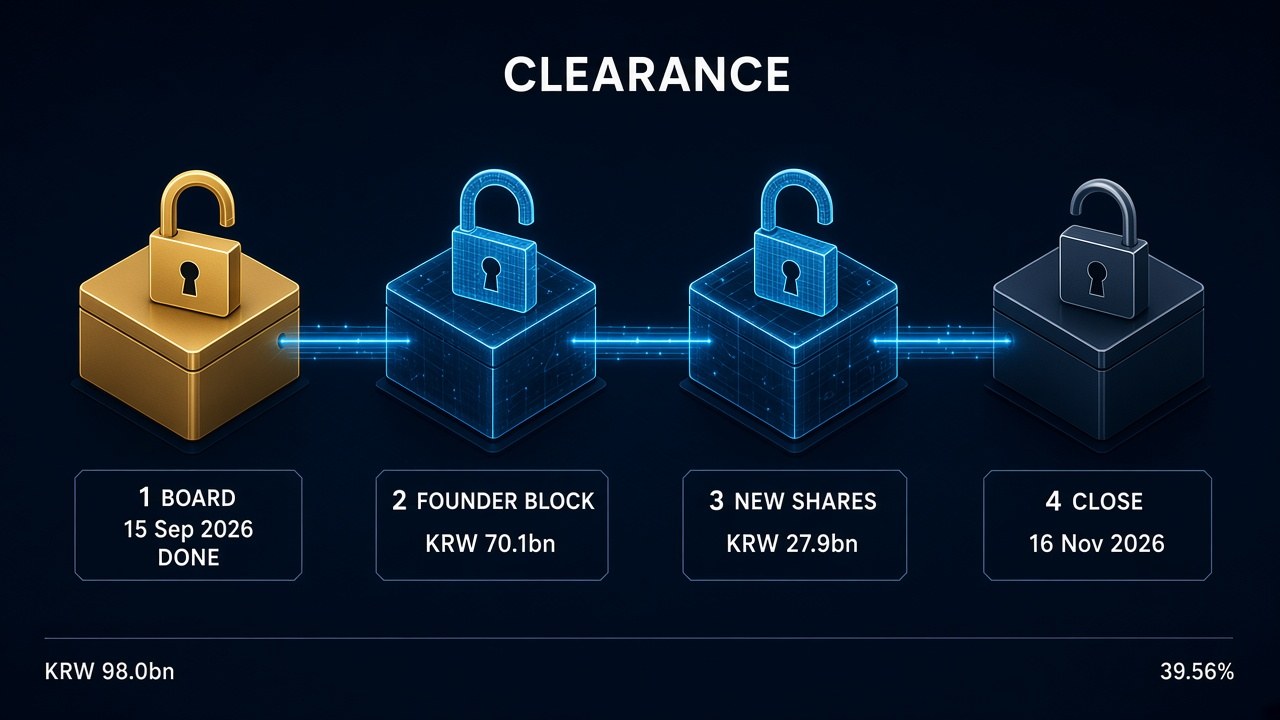
Close is a two-leg settlement on 16 November 2026, subject to Korea Fair Trade Commission merger clearance. Then the founder stays, other registered directors rotate to Kakao nominees, and the ₩27.9bn lands on ME2ON's balance sheet.
| Item | Detail |
|---|---|
| Gate 1 | Board 15 September 2026, done |
| Gate 2 | Founder block KRW 70.1bn |
| Gate 3 | New shares KRW 27.9bn |
| Gate 4 | Close 16 November 2026 |
The practical sequence is clearance, pay the founder block, allot the new shares, seat the board, keep Son and Choi. Edaily flags the KFTC filing as a condition, and the 15 September disclosure says the 16 November date can move if that process does. A 10% deposit on the existing-share SPA was due on signing. There is no disclosed put.
Working, in this case, is unromantic. ME2ON titles keep shipping. The overseas mix holds. The new-issue cash shows up in the next ME2ON balance sheet rather than in a related-party leak. A first joint publishing or China studio project that is actually live would be the proof that Lee's "several areas" remark was an operating plan and not a closing quote.
What the deal says about the market
Korean publishers have spent several years waiting for the next domestic MMORPG hit. Kakao Games' answer, under LY Corp ownership, is to buy a company that already earns money outside Korea in a genre the buyer does not run. Social casino is unfashionable in Seoul strategy decks and very fashionable in overseas cash-flow statements. That gap is the industrial logic.
Acquiry view. Kakao Games is not buying another Korean MMORPG. It is buying the largest-shareholder seat in a profitable social-casino operator whose revenue is already overseas, and putting ₩27.9bn of cash into that operator at the same time.
The best companies are acquired, not sold. ME2ON looks like that kind of asset: a specialist cash engine moving inside a publisher that has said, on the record, that it will keep buying companies that already work.