Reported talks, not an announced acquisition
The only defensible status as of 23 September 2026 is reported acquisition discussions. The parties have not announced a signed transaction.
| Field | Disclosure |
|---|---|
| Status | Reported talks; no definitive agreement |
| Reported buyer | Goldman Sachs |
| Reported target | Palmer Square Capital Management |
Bloomberg first reported on 9 September that Palmer Square was exploring a sale. Thirteen days later, it reported that Goldman had emerged as the lead bidder. That sequence supports the existence of a competitive process, but it does not establish exclusivity, signed documentation or a closing path. No party announcement, merger agreement, Form 8-K or regulatory filing confirming a Goldman-Palmer Square transaction was identified through the research cutoff. [1][2][18]
The language matters because the title's verb is “in talks,” not “agrees to buy.” A reported lead bidder can lose, withdraw, reprice or fail to reach acceptable terms. Palmer Square's owners can also elect not to sell. Until a definitive agreement is announced, every assessment of structure, economics and timing is contingent. [1][2]
Reuters Breakingviews separately described Goldman as among the leading bidders, but its discussion relied on the Bloomberg report. The commentary's $2.8 billion illustration applies a percentage of AUM used in other manager acquisitions; Reuters explicitly says Palmer Square would probably cost less. That figure is a columnist's scenario, not reported consideration, and it is excluded from Acquiry's transaction table and charts. [19]
Chart data
| Date | Event | Status |
|---|---|---|
| 2009 | Palmer Square founded | Verified |
| 9 Sep 2026 | Sale exploration reported | Reported |
| 22 Sep 2026 | Goldman lead-bidder talks reported | Reported |
| 23 Sep 2026 | No definitive agreement announced | Current |
Sources: Palmer Square; Bloomberg.
The $37 billion headline is AUM, not purchase price
Palmer Square presents more than $37.1 billion of firm AUM. Its Form ADV reports $25.591 billion of regulatory AUM at an earlier date. Neither number is deal value.
| Field | Disclosure |
|---|---|
| Firm AUM | Over $37.1bn, company presentation |
| Regulatory AUM | $25.591bn at 31 December 2025 |
| Purchase price | Not disclosed |
Palmer Square's official site describes the firm as managing more than $37.1 billion in fixed-income and credit investments. Its strategy page separately shows “$37+ billion” of approximate firm AUM, 32 investment professionals, 100% management ownership and a 95% client retention rate. Those are company marketing metrics. [3][6]
The firm's Form ADV Part 2A reports $25,590,582,955 of regulatory AUM as of 31 December 2025. Regulatory AUM is a prescribed adviser-reporting measure, measured at a stated date, and it is not automatically the same as a later firm-wide platform AUM figure. The reviewed sources do not publish a reconciliation. The right response is to preserve both figures with labels, not average, add or choose between them. [4][5]
Transaction valuation requires different information: fee-paying AUM by strategy, blended management and incentive fees, revenue, compensation, operating profit, capital commitments, seed assets, warehouse exposure, client concentration, retention obligations and contractual durability. Palmer Square does not publish standalone revenue, EBITDA or net income in the sources reviewed. AUM alone cannot supply a defensible enterprise value. [4][6]
Chart data
| Measure | Value | Date / basis |
|---|---|---|
| Firm AUM | $37.1bn+ | Company presentation |
| Regulatory AUM | $25.591bn | 31 Dec 2025 |
| CLO AUM | $27bn | S&P snapshot, 20 Feb 2026 |
| Purchase price | Not disclosed | Transaction reporting |
Sources: Palmer Square, Form ADV, S&P Global Ratings, Bloomberg.
Palmer Square is a credit-manufacturing platform
The target is a management-owned specialist spanning CLO management, opportunistic credit, income strategies, private credit and structured-credit issuance across public and private vehicles.
| Field | Disclosure |
|---|---|
| CLOs managed | 55, S&P snapshot dated 20 February 2026 |
| CLO AUM | $27bn, S&P snapshot |
| Firm AUM | Over $37.1bn, broader company presentation |
Christopher Long founded Palmer Square in 2009 and serves as Chairman, CEO and Portfolio Manager. Angie Long is Chief Investment Officer and Portfolio Manager. The firm describes itself as 100% management owned. Its Form ADV brochure says equity is held directly and indirectly by principals and senior management, principally through Palmer Square Holdings LLC, which is exclusively owned and controlled by Christopher and Angie Long. [3][4][6]
The platform is wider than CLO issuance. Palmer Square discloses opportunistic credit, CLO debt, income and short-duration strategies, direct-lending access and structured-credit issuance. It packages those capabilities through mutual funds, ETFs, collective investment trusts, private funds, warehouses, separate accounts, CLOs and an affiliated listed business development company. [4][6]
S&P Global Ratings stated on 20 February 2026 that Palmer Square Europe Capital Management LLC and affiliates managed 55 CLOs with $27 billion of CLO AUM, and $36.3 billion of total AUM including non-CLO assets. The rating-agency figure is a dated manager snapshot and overlaps the broader firm figure. It is evidence of scale and repeat issuance, not an additional $27 billion to be added to the $37.1 billion. [7]
| Field | Disclosure |
|---|---|
| Palmer Square | CLOs, private credit, mutual funds, ETFs, CITs, SMAs and BDC |
| Goldman | Institutional, wealth, insurance and alternatives distribution |
| Synergies | Not disclosed; analytical framework only |
Palmer Square Capital BDC Inc. adds a public window into one vehicle, not into the private manager's own income statement. At 30 June 2026, PSBD reported $1.1 billion of total assets, $406.2 million of net assets and $27.3 million of quarterly total investment income. Its portfolio held 282 investments across 206 companies at approximately $1.1 billion fair value. Those figures describe the listed BDC. They must not be presented as Palmer Square Capital Management revenue or balance-sheet assets. [8]
The commercial asset is therefore a connected system: investment judgement, sourcing, collateral management, repeat issuance, fund vehicles, indexes and client relationships. A buyer is not only acquiring balances labeled AUM. It is acquiring the people, mandates, operating permissions and product structures that keep those balances in place.
Why the platform could fit Goldman
The likely logic is capability adjacency: add a specialist CLO and credit engine to a scaled asset-management, wealth, institutional and insurance distribution platform.
| Field | Disclosure |
|---|---|
| Goldman AWM AUS | $4.041tn at 30 June 2026 |
| Goldman alternatives AUS | $459bn at 30 June 2026 |
| Palmer Square firm AUM | Over $37.1bn; not directly comparable to AUS |
Goldman's Asset & Wealth Management business reported $4.041 trillion of assets under supervision at 30 June 2026, including $459 billion of alternative-investment AUS. It generated $3.355 billion of management and other fees in the second quarter. Goldman defines AUS more broadly than AUM, so those figures provide strategic context rather than a directly comparable denominator for Palmer Square. [9]
Goldman's 2025 annual report identifies Wealth, Alternatives and Solutions as growth avenues. It reported $115 billion of alternatives fundraising during 2025 and set a forward-looking objective of $750 billion in fee-paying alternative AUS by the end of 2030. Goldman separately stated in May 2025 that it had $130 billion of private-credit AUM across more than 1,100 positions. [10][11]
Palmer Square would be small relative to Goldman's total AUS, but scale is not the sharpest rationale. The strategic gap is specialized structured-credit manufacturing: established CLO teams, repeat collateral-manager relationships, dedicated credit funds, indexes and vehicles that can be distributed through broader institutional, wealth and insurance channels. That could expand recurring fee streams and product density. No party has confirmed those synergies or their economics. [3][6][7][9]
Chart data
| Platform | Metric | Value |
|---|---|---|
| Goldman AWM | Total AUS | $4.041tn |
| Goldman AWM | Alternatives AUS | $459bn |
| Palmer Square | Firm AUM | $37.1bn+ |
Sources: Goldman Sachs Q2 2026; Palmer Square. AUS is broader than AUM.
Recent acquisition behavior reinforces the pattern. Goldman agreed to acquire Industry Ventures, a $7 billion venture platform, for $665 million at closing plus up to $300 million of contingent consideration; it announced a $2.0 billion transaction for Innovator, then agreed to pay up to $2.25 billion for NEOS and up to approximately $410 million for LCN. The strategic commonality is ownership of specialist products and teams that plug into a larger distribution system. Those transaction prices are not valid Palmer Square comparables without earnings, fee mix, growth, retention and balance-sheet commitments. [12][13][14][15]
Chart data
| Target | Scale | Disclosed consideration | Status at announcement |
|---|---|---|---|
| Industry Ventures | $7bn AUS | $665m plus up to $300m contingent | Agreement |
| Innovator | $28bn AUS | Approximately $2.0bn | Agreement |
| NEOS | $30bn assets | Up to $2.25bn | Agreement |
| LCN | Approximately $3bn AUS | $260m upfront plus up to $150m contingent | Agreement |
| Palmer Square | $37.1bn+ firm AUM | Not disclosed | Reported talks |
Sources: Goldman announcements; Palmer Square; Bloomberg.
What a valuation would have to underwrite
Without revenue, EBITDA, fee rates or purchase terms, the useful work is to identify the variables that determine durable manager economics, not to publish a false multiple.
The revenue base should be separated into management fees, incentive fees, CLO management fees, origination or structuring economics, fund-level reimbursements and any income linked to seed or retained investments. Each stream has a different margin, duration, volatility and capital requirement. Public AUM alone cannot reveal the mix.
The AUM quality test is equally important. Diligence should split fee-paying from non-fee-paying assets; gross from net; permanent, evergreen and closed-end capital from redeemable mandates; CLOs inside and outside reinvestment periods; third-party capital from affiliate or seeded assets; and contracted base fees from performance-linked revenue. Palmer Square's $37.1 billion headline gives scale, but not that decomposition. [3][4][6][7]
Capital intensity needs its own workstream. An asset manager does not fund every loan it manages, yet a CLO and private-credit franchise can still require warehouse lines, seed capital, risk-retention interests, CLO equity, co-investments, liquidity facilities, guarantees and balance-sheet support. The buyer's return on capital depends on how those obligations transfer or expand, not only on the purchase cheque.
Reuters Breakingviews' 7.5%-of-AUM illustration usefully demonstrates why shortcuts are tempting. It does not solve the problem. Innovator and NEOS are ETF managers with different product economics and distribution channels. Palmer Square is a structured-credit specialist with vehicles, contractual obligations and market-cycle exposure. A single AUM percentage obscures the variables that matter most. [12][14][19]
Ownership transfer is not the same as asset retention
The central execution question is whether clients, fund boards, counterparties and investment professionals remain through a change of control.
| Field | Disclosure |
|---|---|
| Current control | Christopher and Angie Long through management ownership |
| Key issue | Leadership, investment committee and client continuity |
| Terms | Retention arrangements not disclosed |
Palmer Square's current control is concentrated in Christopher and Angie Long, and the firm markets itself as 100% management owned. Their roles sit at the center of investment judgement, client confidence and product identity. Any definitive transaction would need to explain leadership retention, economics, governance and investment-committee continuity. None of those arrangements is public. [3][4][6]
Client consent and fund governance are not administrative footnotes. SEC staff guidance states that Section 205(a)(2) of the Advisers Act generally requires registered-adviser contracts to provide that they cannot be assigned without client consent. Registered funds and a listed BDC add board, shareholder, interim-contract and adviser-continuity processes. The exact obligations depend on legal structure and each agreement. [4][8][16]
CLOs, private funds, collective investment trusts, warehouses and separate accounts will have their own change-of-control, assignment, key-person, trustee, lender, investor and ratings-agency provisions. A viable close plan needs a vehicle-by-vehicle matrix, not a generic “regulatory approvals” line. The broad vehicle set disclosed in Palmer Square's Form ADV makes this a core workstream. [4][6][7]
Historical compliance belongs in diligence as well. In 2020, Palmer Square settled an SEC proceeding involving pre-trade compliance controls for certain affiliated transactions. The matter is historical and settled; it should not be presented as evidence about the current sale process. It remains a relevant item for compliance testing, remediation verification and control-environment review. [17]
Chart data
| Risk | Severity | Likelihood | Resolution evidence |
|---|---|---|---|
| Talks fail or another bidder wins | 5 | 3 | Definitive agreement |
| Leadership or investment-team attrition | 5 | 3 | Retention and governance terms |
| Client / mandate consent leakage | 5 | 3 | Consent tracker and retained AUM |
| Valuation unsupported by earnings | 4 | 4 | Standalone financials and purchase terms |
| Vehicle and contract complexity | 4 | 4 | Vehicle-by-vehicle legal matrix |
| Credit-cycle and CLO issuance volatility | 4 | 3 | Vintage, fee and reinvestment-period data |
Acquiry analysis based on disclosed platform structure and transaction status.
What has to happen before this becomes a deal
A definitive agreement would be the first decisive milestone. Everything after that depends on structure, approvals, consents and retained assets.
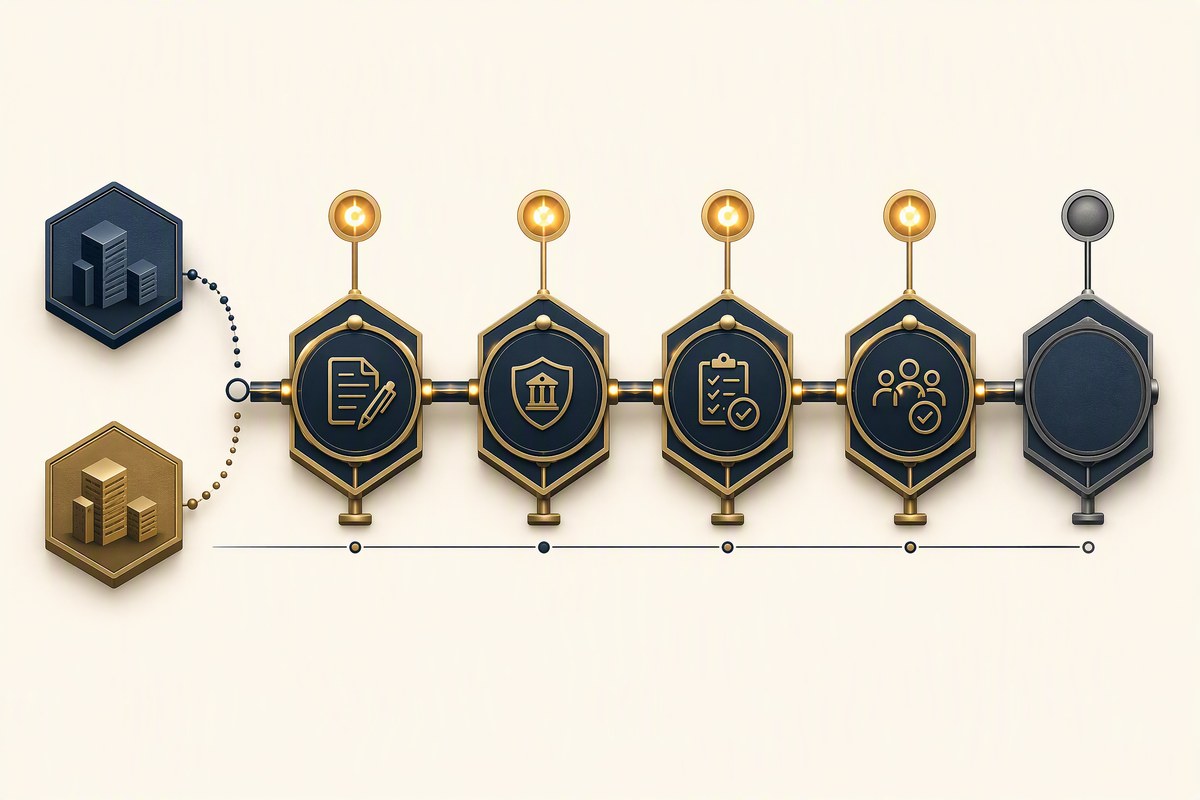
| Field | Disclosure |
|---|---|
| Current | Reported talks |
| Next possible gate | Definitive agreement |
| Then | Regulatory, fund, client and contractual approvals |
| Expected close | Not disclosed |
The immediate watch item is simple: company confirmation. A Goldman or Palmer Square announcement would need to establish buyer entity, seller or rollover holders, purchase price, consideration mix, financing, governance, leadership, employee retention, conditions, termination rights and the expected closing window. Until then, a closing timetable is not available. [1][2]
If a definitive agreement is signed, antitrust and bank-regulatory analysis would depend on acquisition value, legal entities, control and target consolidated assets. Headline AUM does not answer those tests. SEC/IARD amendments, fund-board and shareholder processes, adviser-contract consents and non-US permissions would run alongside client communications and operational separation or integration planning. [5][16]
Commercially, the most sensitive metric will be retained fee-paying AUM rather than announced AUM. A strong transaction would protect the investment team, preserve manager autonomy where it supports performance, maintain client service, and use Goldman distribution selectively rather than forcing product migration. Integration that changes portfolio process, key-person confidence or client governance too quickly could destroy the asset being acquired.
Acquiry watchlist
- Transaction statusReported talks. Watch for a definitive agreement, a bidder change or termination of the process.
- Purchase economicsUndisclosed. Require a bridge from consideration to fee-paying AUM, revenue, EBITDA and retained capital.
- LeadershipUndisclosed. Test Christopher and Angie Long's roles, ownership rollover and investment-committee continuity.
- Client retentionUnresolved. Track consent completion and fee-paying AUM retained at signing and close.
- Vehicle permissionsUnresolved. Map registered funds, BDC, CLOs, private funds, CITs, SMAs, warehouses and side letters.
- Capital intensityUndisclosed. Separate purchase price from seed, warehouse, risk-retention and co-investment obligations.
Sources and methodology
Original reporting establishes transaction status. Company, SEC and rating-agency disclosures establish platform facts. Acquiry analysis is labelled and never converted into an undisclosed deal term.
- 01Bloomberg, Goldman in Talks to Buy $37 Billion Credit Firm Palmer Square, 22 September 2026Reported
- 02Yahoo Finance / Bloomberg authorized republication of the 22 September reportReported
- 03Palmer Square Capital Management, AboutPrimary
- 04Palmer Square Capital Management LLC, Form ADV Part 2A Disclosure BrochureRegulatory
- 05SEC Investment Adviser Public Disclosure, Palmer Square, CRD 155697SEC
- 06Palmer Square, Private Funds & Customized Investment SolutionsPrimary
- 07S&P Global Ratings, Presale: Palmer Square CLO 2026-1Ratings
- 08Palmer Square Capital BDC, Q2 2026 financial resultsPrimary
- 09Goldman Sachs, Q2 2026 earnings results filed with the SECSEC
- 10Goldman Sachs 2025 Annual ReportPrimary
- 11Goldman Sachs, Private Credit’s Outlook Amid Rising VolatilityPrimary
- 12Goldman Sachs agreement to acquire Innovator Capital ManagementPrimary
- 13Goldman Sachs acquisition of Industry VenturesPrimary
- 14Goldman Sachs agreement to acquire NEOS InvestmentsPrimary
- 15Goldman Sachs agreement to acquire LCN Capital PartnersPrimary
- 16SEC Investment Management Staff Issues of Interest, Advisory Contracts: ConsentSEC
- 17SEC administrative proceeding concerning Palmer Square, 16 September 2020SEC
- 18Bloomberg, Husband and Wife Plan Sale of $37 Billion Credit Firm Palmer Square, 9 September 2026Reported
- 19Reuters Breakingviews, Goldman sets M&A pace with freed capitalCommentary
- 20Acquiry Deal Intelligence methodologyAcquiry
Method: Acquiry Deal Intelligence methodology. Acquiry was not engaged by any party. Nothing here is investment, legal or financial advice.