Summary
Summary
- Transaction costs are the fees you pay to get a deal done: lawyers, accountants, technical reviewers, advisers, lenders, insurers and regulators. They are separate from the purchase price.
- Escrow, working-capital adjustments and deferred consideration are not costs. They are parts of the price that move in time or depend on outcomes, and mixing them into the cost budget distorts both numbers.
- Most diligence spend happens between signing a letter of intent and signing the purchase agreement. That is the money at risk if the deal falls through.
- Who pays is negotiable, but the usual starting point is that each side pays its own advisers and the buyer pays for its own diligence, financing and insurance.
- A written budget by stage, with a cap per provider and a clear walk-away point, is the single best protection against cost overrun.
01 · Guides
What counts as a transaction cost
Fees to get the deal done, not the price of the business.
A transaction cost is money spent to investigate, negotiate, finance and complete an acquisition. It goes to third parties: law firms, accounting firms, technical reviewers, brokers and advisers, lenders, insurers and government agencies. None of it buys any part of the target. That is what separates it from the purchase price, and it is why accountants usually expense acquisition costs rather than adding them to the value of what was bought, depending on the accounting framework and deal type.
Budgeting starts with a clean separation. On one side sits the price: the enterprise value agreed in the letter of intent, adjusted for cash, debt and working capital, and paid partly at completion, partly later. On the other side sit the costs: the fees each party pays to reach that price. Our guide to enterprise value vs equity value covers how the price side bridges to cash at completion.
02 · Guides
The cost categories, and who typically pays
Seven buckets cover almost every acquisition.
The table below lists the main categories for a private acquisition. "Typically" means the common starting position, not a rule: allocation is negotiated and recorded in the letter of intent and the purchase agreement.
| Category | What it covers | Who typically pays | What drives the amount |
|---|---|---|---|
| Legal | Term sheet and LOI review, legal due diligence, purchase agreement, disclosure letter, ancillary documents, completion mechanics | Each side pays its own counsel | Deal complexity, number of jurisdictions, how heavily the purchase agreement is negotiated |
| Financial diligence and QoE | Quality of earnings review, net debt and working-capital analysis, revenue testing | Buyer, for its own review. Some sellers commission a vendor QoE up front | Quality of the target's books, number of entities, revenue model complexity |
| Tax diligence and structuring | Historic tax exposures, structure of the acquisition vehicle, transfer taxes, post-close tax planning | Buyer for diligence, each side for its own structuring | Cross-border elements, entity count, sales-tax or VAT footprint |
| Technical and product diligence | Code review, architecture, security posture, open-source licences, data protection, AI use | Buyer | Size of the codebase, regulated data, scope of the security testing |
| Deal advisers and introducers | Origination, process management, buyer or seller introductions | Each side pays any adviser it appoints, under its own engagement terms | Transaction size and complexity, fee structure agreed per engagement |
| Financing | Arrangement and commitment fees, lender legal costs, lender diligence, security registration | Buyer (borrower) | Amount borrowed, lender type, how quickly funds must be committed |
| Insurance | Warranty and indemnity (W&I) or representations and warranties (R&W) insurance premium, underwriting fee, broker fee, premium taxes | Buyer usually, sometimes shared | Policy limit, retention, sector risk, jurisdiction |
| Regulatory and filings | Merger-control filings, foreign-investment notifications, transfer taxes, registry fees | Varies by regime. In the US the acquiring person pays the HSR fee | Deal size, jurisdictions touched, sector sensitivity |
Regulatory costs you can look up
Some costs are published. In the United States, filing a Hart-Scott-Rodino premerger notification carries a fee set by transaction size. The Federal Trade Commission's 2026 schedule (opens in a new tab) starts at $35,000 for transactions under $189.6 million and rises to $2,460,000 at $5.869 billion or more. The FTC says the acquiring person pays at filing, though the parties may agree to split it.
In the UK, buying existing shares in a UK company usually carries Stamp Duty or Stamp Duty Reserve Tax of 0.5% (opens in a new tab) of the price paid, which matters on share deals and does not arise in the same way on an asset purchase. Deals touching sensitive sectors may also need a notification under the National Security and Investment Act (opens in a new tab). Rules differ in every jurisdiction, so the regulatory line needs confirming with counsel for each country the target operates in.
03 · Guides
Not costs: escrow, working capital and deferred consideration
Three things that look like spend but are really price.
Three items regularly turn up in cost budgets when they belong in the price model.
- Escrow and holdbacksPart of the price held back, by a third-party agent or by the buyer, to cover warranty claims or adjustments. If no claim is made it is released to the seller. The escrow agent's fee is a transaction cost; the escrowed money is not. See W&I insurance vs escrow.
- Working-capital adjustmentA true-up of the price so the buyer receives a normal level of working capital at completion. It can move the price up or down. The NWC peg calculator shows how a peg is set; locked box vs completion accounts covers the mechanism.
- Deferred and contingent considerationSeller notes, deferred payments and earnouts are price paid later. They affect funding and risk, not the fee budget. Model them with the earnout modelling tool, and see seller financing for note protection.
04 · Guides
Costs by stage, and what is at risk
The spend curve is back-loaded, but the risk peaks before signing.
Acquisition spend is uneven. Very little is committed before a letter of intent. Most diligence and drafting happens in the exclusivity period, and that is where a failed deal hurts most. Financing and insurance costs often fall due at signing or completion, and some are only payable if the deal closes.
| Stage | Typical spend | At risk if the deal fails? |
|---|---|---|
| 1. Screening and first calls | Internal time, light desk research, early adviser conversations | Low. Mostly internal time |
| 2. Indicative offer and LOI | Counsel review of the LOI, initial financial model, early lender and insurer soundings | Low to moderate |
| 3. Confirmatory diligence (exclusivity) | QoE, legal, tax, technical and commercial diligence, insurer underwriting call | High. This is the bulk of sunk cost |
| 4. Purchase agreement negotiation | Drafting and negotiating the SPA or APA, disclosure, financing documents | High |
| 5. Signing | Insurance premium (often bound at signing), commitment fees, filings | Partly. Some fees are refundable or contingent |
| 6. Completion | Success-based adviser fees, arrangement fees, transfer taxes, registry costs | Usually payable only if the deal closes |
The money at risk in stages 3 and 4 is why exclusivity terms matter. Buyers sometimes negotiate expense reimbursement if a seller withdraws without cause during exclusivity, and sellers sometimes ask for a reverse break fee if a buyer fails to close for financing reasons. Neither is standard in smaller private deals, and both are worth raising before the LOI is signed rather than after. Our LOI teardowns and the LOI value decoder show where those terms sit.
05 · Guides
A sample budget worksheet
Hypothetical figures for a mid-sized software acquisition.
The worksheet below uses hypothetical figures for a single-entity, single-country software business bought for $20 million of enterprise value with partial bank financing and a W&I policy. It is a format, not a benchmark: real quotes vary widely with complexity, jurisdiction and provider, and a buyer should replace every line with written quotes.
| Line | Stage committed | Hypothetical budget | Cap or basis | Contingent on close? |
|---|---|---|---|---|
| Buyer legal counsel | LOI to completion | $250,000 | Capped fee per phase | No |
| Quality of earnings | Diligence | $90,000 | Fixed fee, scope agreed | No |
| Tax diligence and structuring | Diligence | $45,000 | Fixed fee | No |
| Technical and security diligence | Diligence | $40,000 | Fixed fee | No |
| Commercial or customer diligence | Diligence | $25,000 | Fixed fee | No |
| Lender fees and lender counsel | Signing to completion | $160,000 | Per term sheet | Mostly yes |
| W&I premium, broker and taxes | Signing | $230,000 | Per quote | Partly |
| Regulatory filings | Signing | Per regime | Published fee schedules | No |
| Contingency | Throughout | 10% of the above | Released only with approval | n/a |
Read the worksheet by column. "Stage committed" tells you when the cash goes out. "Contingent on close?" tells you how much of it you lose if the deal dies. In this hypothetical, roughly $450,000 of the budget is exposed before signing.
06 · Guides
Questions to ask when comparing provider quotes
Most overruns come from scope, not hourly rates.
Quotes are rarely comparable on headline price. The questions below expose the differences that drive the final bill.
- 01ScopeWhat exactly is included, and what triggers a change order? Ask for scope in writing, by workstream.
- 02Fee basisFixed, capped, phased or hourly? If hourly, what is the estimate and who approves overruns?
- 03Abort termsWhat do you charge if the deal stops at each stage? Is there a reduced abort fee?
- 04StaffingWho will do the work, and at what seniority? How much partner time is assumed?
- 05RelianceWill the report be addressed to, or relied upon by, our lender and insurer? Reliance letters sometimes cost extra.
- 06TimingCan you meet the exclusivity timetable? What happens to the fee if the timetable slips?
- 07OverlapWhich questions will another provider also cover? Overlap between QoE, tax and legal diligence is common and avoidable.
- 08ConflictsHave you acted for the seller, the target or a competing bidder?
07 · Guides
How to keep costs under control
Sequence the spend so you can stop cheaply.
- Gate the diligenceRun the cheapest disqualifying checks first: revenue quality, customer concentration, key contracts. Commission the expensive workstreams after the red-flag review passes.
- Use a data-room indexA complete index early reduces repeated requests, which is where advisers' hours disappear.
- Ask for a vendor packIf the seller has a vendor QoE or a legal fact book, reviewing it is usually cheaper than rebuilding it, though most buyers still test it independently.
- Set walk-away pointsAgree in advance which findings end the deal. It keeps sunk cost from driving the decision.
For the financing side of the budget, the capital stack builder and the deal structure comparison model how debt, equity and seller paper combine; this page deliberately does not repeat them. The due diligence checklist lists what each diligence workstream should cover.
Reference
Frequently asked questions
What are M&A transaction costs?
They are the fees paid to third parties to investigate, negotiate, finance and complete an acquisition: legal, accounting, tax and technical diligence, adviser fees, financing fees, insurance premiums and regulatory filings. They are separate from the purchase price.
Who pays transaction costs, buyer or seller?
The usual starting point is that each side pays its own advisers, and the buyer pays for its own diligence, financing and insurance. Allocation is negotiable and should be written into the letter of intent and the purchase agreement.
Is escrow a transaction cost?
No. Escrow is part of the purchase price held back to cover claims, and it is released to the seller if no claims are made. Only the escrow agent's fee is a transaction cost.
How much of the budget is lost if a deal falls through?
Usually most of the diligence and legal drafting spend, which is committed during exclusivity. Success-based fees and many financing fees are only payable on completion.
Can a buyer recover costs if the seller walks away?
Only if the documents say so. Some letters of intent include expense reimbursement if the seller withdraws without cause during exclusivity. It is not standard in smaller private deals and must be negotiated up front.
Who pays the US HSR filing fee?
The FTC says the acquiring person is responsible for paying the fee at filing, but the parties may agree alternative arrangements, such as splitting it, and note them on the form.
Further reading
Sources
Research current to 16 October 2026.
- Filing Fee Information (opens in a new tab)Federal Trade Commission · Accessed 16 Oct 2026 · Primary
- Tax when you buy shares (opens in a new tab)GOV.UK · Accessed 16 Oct 2026 · Primary
- National Security and Investment Act (opens in a new tab)GOV.UK · Accessed 16 Oct 2026 · Primary
Keep reading
Related analysis
Guides · M&A
W&I Insurance vs Escrow: How Buyers and Sellers Protect a Deal
Every acquisition carries a question nobody can fully answer at signing: what if something the seller promised turns out to be untrue? Escrow, holdbacks and warranty and indemnity insurance are three answers. They move risk to different places, and they suit different deals.
Guides · M&A
Locked Box vs Completion Accounts: How the Final Price Gets Set
The headline price in a letter of intent is not the cheque the seller receives. Cash, debt and working capital move every day until completion. Two mechanisms decide who carries that movement: the locked box fixes the price early, completion accounts true it up afterwards.
Research · Research
Buyer Underwriting Checklist
A structured checklist for pre-LOI, commercial, technical, and legal diligence on digital asset acquisitions.
Research · Research
Deal Structure Playbook
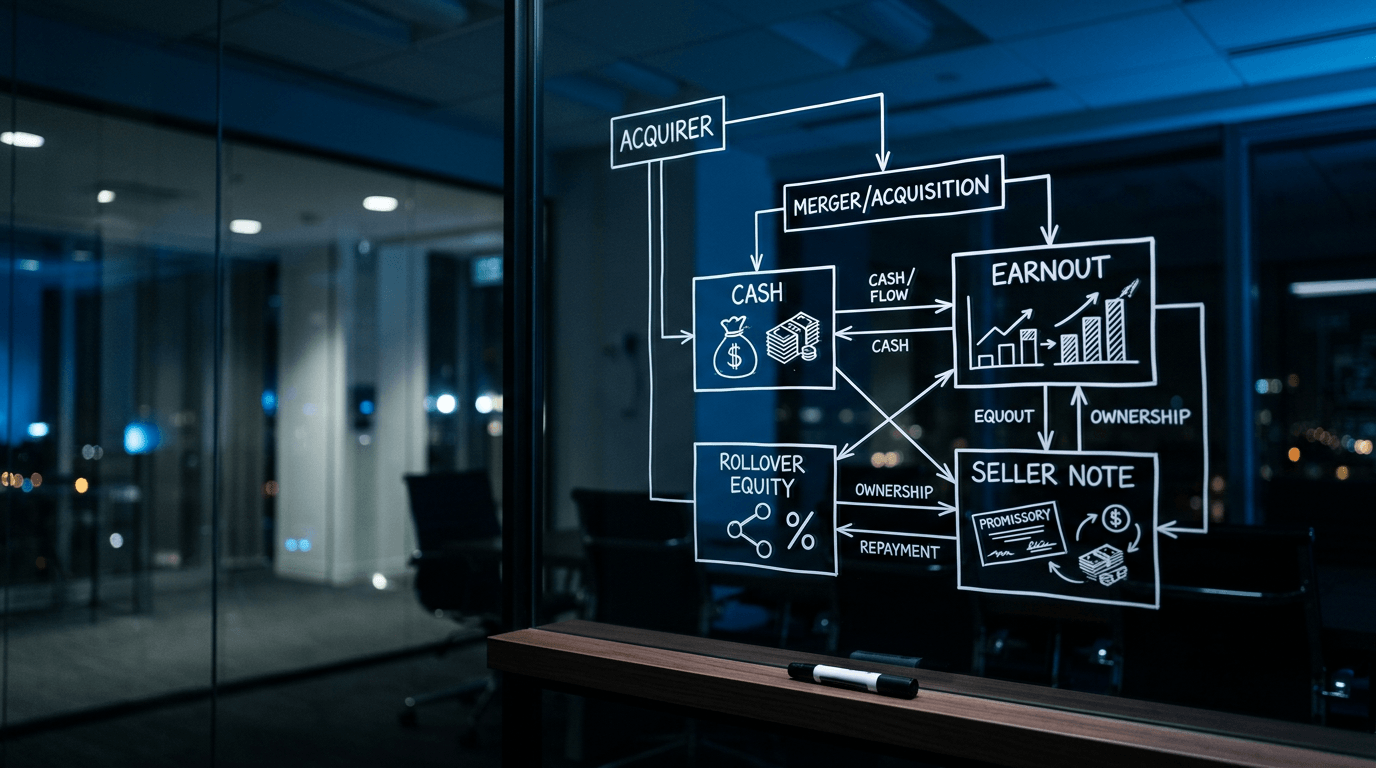
Market benchmarks for earnouts, rollovers, seller notes, and working capital adjustments in digital asset M&A.
Explore the sector:/acquisitions//process/
About the analyst
Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, an M&A firm built around buy-side acquisition origination. He works with strategic acquirers, private equity firms and advisers supporting buyers on mandates from USD $1M to $500M. Most of the work sits in technology, SaaS, fintech, payments, gaming and digital assets, and it is not limited to them: any sector, any market.