Summary
Summary
- Both mechanisms answer the same question: how does the agreed enterprise value become the exact amount paid for the shares?
- A locked box fixes the equity price using a balance sheet dated before signing. From that date the business is run for the buyer's benefit, and the seller promises no value leaks out to itself.
- Completion accounts pay an estimated price at completion, then prepare accounts at the completion date and adjust the price up or down for actual cash, debt and working capital.
- Locked box gives price certainty and a cleaner exit but relies on trustworthy historic accounts and strong leakage protection. Completion accounts are more precise but take months and often lead to disputes.
- The choice affects cash, timing and risk. It needs agreeing in principle at the letter-of-intent stage, not discovered in the purchase agreement.
01 · Guides
The problem both mechanisms solve
Enterprise value is fixed; the business keeps moving.
Most acquisitions are priced on a cash-free, debt-free basis with a normal level of working capital. The buyer agrees an enterprise value. The equity price, what is actually paid for the shares, is that enterprise value plus cash, minus debt and debt-like items, plus or minus any difference between actual and normal working capital. Our guide to enterprise value vs equity value walks through the bridge.
The difficulty is timing. Cash, debt and working capital are different on every day between the letter of intent and completion. Someone has to decide which day's balance sheet sets the price, and who keeps the profit, or bears the loss, generated in between. That is the job of the price mechanism.
02 · Guides
How a locked box works
Price fixed on a past balance sheet; value protected by leakage rules.
In a locked box deal the parties choose a locked box date, usually the date of the most recent audited or reviewed balance sheet. The equity price is calculated from that balance sheet and written into the purchase agreement as a fixed number. There is no adjustment after completion.
From the locked box date, economic risk and reward pass to the buyer, even though the seller still owns and runs the company until completion. To stop the seller extracting value in that window, the seller promises there has been, and will be, no leakage: no dividends, management fees, bonuses, asset transfers, waived debts or other payments to the seller or its connected parties, except for permitted leakage listed and quantified in the agreement. Leakage is usually repaid pound-for-pound or dollar-for-dollar.
- Locked box dateThe balance sheet date the price is based on. The older it is, the more the buyer relies on how the business has performed since.
- LeakageAny value passing from the target to the seller side after the locked box date. Defined broadly, listed precisely.
- Permitted leakageAgreed exceptions, such as normal salaries to seller-employees, each named and capped.
- Ticker or interestA daily amount sometimes added to the price to compensate the seller for profits generated after the locked box date. Often linked to cash generation.
- Conduct of businessUndertakings that the seller runs the business normally between signing and completion.
03 · Guides
Leakage and permitted leakage in practice
The locked box only works if value cannot quietly leave the business between the balance sheet date and completion. Leakage clauses are how that promise is enforced.
Leakage is any transfer of value from the target to the seller or the seller's connected parties after the locked box date. Dividends, return of capital, management fees to a shareholder, bonuses triggered by the sale, waived debts and transaction costs paid by the company on the seller's behalf are the usual examples. The seller promises that none of these have happened except those specifically agreed, and repays the buyer pound for pound if they have.
Permitted leakage is the agreed list of payments that may go out during the locked box period. Normal salaries at existing rates, payments under existing arm's-length contracts and a specific, quantified dividend are common entries. Because the price was set on the locked box balance sheet, anything on the permitted list should already be reflected in the price. A buyer reviewing the list will check that each item is either small, ordinary course, or already deducted.
Who counts as connected
The definition of the seller's connected parties decides how far the leakage promise reaches. Family members, other companies owned by the seller and, in a private equity sale, other portfolio companies of the same fund are often included. A narrow definition leaves gaps; a very broad one can catch ordinary trading between group companies that nobody intended to stop, so it is common to carve out normal trading on existing terms.
The ticker
Because the buyer takes the economic benefit of the business from the locked box date, sellers frequently ask for compensation for the cash the business generates while they still own it. This is usually a daily amount, sometimes called a ticker or equity interest charge, paid on top of the price from the locked box date to completion. It can be a fixed sum per day, or a rate applied to the equity price. A ticker is most persuasive where the business is reliably cash generative and the gap to completion is long, for example because regulatory clearance is needed.
04 · Guides
How completion accounts work
Estimate now, measure afterwards, settle the difference.
Under completion accounts the buyer pays an estimated equity price at completion, using the seller's estimate of cash, debt and working capital at that date. After completion, one party, often the buyer because it now controls the books, prepares completion accounts as at the completion date using agreed accounting policies. The other party reviews them. The price is then adjusted for the difference between estimated and actual figures.
- 01Preparation periodCommonly 60 to 90 days after completion for the draft accounts.
- 02Review periodThe other side checks them and raises objections within a set window.
- 03Dispute resolutionUnresolved items go to an independent accountant acting as expert, whose decision is usually binding on those items.
- 04SettlementThe paying party settles the adjustment, sometimes from an adjustment escrow set up at completion.
The working-capital peg
The peg (or target) is the normal level of working capital the buyer expects to receive, usually based on a trailing average to smooth out seasonality. If actual working capital at completion is above the peg, the price goes up; below it, the price goes down. Setting the peg well matters more than almost any other term in a completion accounts deal. The NWC peg calculator shows how averages and seasonality change the number.
05 · Guides
Setting the working capital target
Under completion accounts, much of the final price adjustment comes from working capital. The target, or peg, decides whether that adjustment goes up or down.
The buyer wants the business delivered with a normal level of working capital, enough receivables, stock and payables headroom to keep trading without injecting extra cash. The target is usually set by looking at the average of monthly working capital over the last twelve months, adjusted for anything unusual. If actual working capital at completion is above the target, the price goes up; if it is below, the price comes down.
Seasonal businesses need particular care. A retailer that closes just before its busiest period will naturally carry high stock, and a target based on a simple twelve-month average could produce a large, unexpected upward adjustment, or the reverse if completion falls at a seasonal low. Some deals use a month-specific target for this reason. Others agree a range, or collar, inside which no adjustment is made, which reduces arguments over small movements.
Accounting policies decide the outcome
Completion accounts are only as predictable as the rules used to draw them up. Purchase agreements usually set a hierarchy: specific policies agreed in the agreement come first, then the company's past practice, then the relevant accounting standards. Specific policies on provisions for bad debts, stock obsolescence, accruals and deferred revenue are worth agreeing in detail, because each one moves working capital and therefore price.
06 · Guides
Side by side
Certainty against precision.
| Row | Locked box | Completion accounts |
|---|---|---|
| Price set by | Historic balance sheet, fixed at signing | Balance sheet at completion, adjusted after |
| Economic risk from | Locked box date | Completion date |
| Certainty for seller | High: known price, no true-up | Lower: price moves after completion |
| Precision for buyer | Relies on historic accounts and leakage protection | Reflects actual position at completion |
| Post-completion work | Minimal, unless leakage is claimed | Accounts, review and possible expert determination |
| Dispute risk | Focused on leakage | Higher: accounting policies, judgements, peg |
| Suits | Stable businesses with reliable recent accounts; auctions; private equity sellers | Volatile working capital; carve-outs; weak or old accounts; first-time sellers |
07 · Guides
A worked example
Hypothetical figures, the same business both ways.
A buyer agrees an enterprise value of $30 million for a software company. Normal working capital (the peg) is $1.0 million. The figures below are hypothetical.
| Item | Locked box (balance sheet at 31 March) | Completion accounts (estimate at 30 June) | Completion accounts (actual at 30 June) |
|---|---|---|---|
| Enterprise value | $30.0M | $30.0M | $30.0M |
| Plus cash | $2.0M | $2.6M | $2.4M |
| Less debt and debt-like items | ($3.0M) | ($2.8M) | ($2.9M) |
| Working capital vs $1.0M peg | $1.2M: +$0.2M | $1.1M: +$0.1M | $0.8M: ($0.2M) |
| Equity price | $29.2M fixed | $29.9M paid at completion | $29.3M final |
In the locked box column the seller receives $29.2 million, plus any agreed ticker, and keeps nothing generated after 31 March except through that ticker. In the completion accounts column the buyer pays $29.9 million at completion and, after the accounts are agreed, the seller repays $0.6 million because cash and working capital came in below the estimate. Same business, different timing, different risks.
08 · Guides
How to choose, and what to negotiate
Agree the mechanism early, then negotiate its details.
- Quality of accountsRecent audited or reviewed accounts favour locked box. Unaudited or complex books favour completion accounts.
- VolatilityIf working capital swings with seasons or large contracts, completion accounts protect both sides better.
- Carve-outsA business separated from a group rarely has standalone historic accounts, which pushes towards completion accounts.
- Seller prioritiesSellers wanting certainty and a quick distribution usually push for locked box.
- Buyer prioritiesBuyers short on diligence time or wary of the accounts usually prefer completion accounts.
Terms to watch
- In locked box deals: breadth of the leakage definition, the permitted leakage list, the claim period, and any ticker
- In completion accounts deals: the accounting policy hierarchy, the peg methodology, de minimis thresholds, the adjustment escrow and the expert process
- In both: what counts as debt and debt-like items, how cash is defined (trapped cash, customer deposits), and how earnouts or deferred payments interact with the price
Related reading: M&A transaction costs explains why adjustments are price, not cost; W&I insurance vs escrow covers how warranty claims are funded; the earnout modelling tool models contingent price. Our LOI teardowns show where the mechanism should first appear.
09 · Guides
Disputes, expert determination and hybrid structures
Most price mechanisms run smoothly. When they do not, the agreement needs a quick and contained way to resolve the numbers.
Completion accounts disputes are usually resolved by an independent accountant acting as expert, not by the courts. The agreement sets out how the draft accounts are prepared, how long the other side has to review them, how objections are raised and when an unresolved item goes to the expert. Tight timetables and a requirement to give specific, itemised objections keep the process short and stop it becoming a reopening of the whole deal.
Locked box disputes are less frequent because there is no post-completion calculation. When they happen they are usually leakage claims, and they are argued under the contract rather than through an expert process. That difference is one reason sellers in competitive processes favour the locked box: the price is known at signing and the scope for later argument is narrower.
| Point | Locked box | Completion accounts |
|---|---|---|
| Price certainty at signing | High: price fixed subject to leakage | Lower: final price known after completion |
| Post-completion work | Minimal | Draft accounts, review, possible expert determination |
| Who carries trading risk to completion | Buyer, from the locked box date | Seller, until completion |
| Typical setting | Competitive auctions, stable businesses | Carve-outs, volatile working capital, longer gaps |
Hybrid approaches
- A locked box price with a completion adjustment for cash and debt only, leaving working capital fixed.
- Completion accounts with a narrow collar, so small working capital movements do not change the price.
- A locked box with a buyer right to switch to completion accounts if signing slips beyond an agreed date.
Hybrids are useful where neither side wants to carry the whole risk of a long gap between signing and completion. The cost is more drafting and a little less certainty, so they work best when the reason for them is clear and written into the term sheet from the start.
Reference
Frequently asked questions
What is a locked box in M&A?
A pricing mechanism where the equity price is fixed using a balance sheet dated before signing. The seller promises no value leaks to it after that date, and there is no post-completion price adjustment.
What are completion accounts?
Accounts prepared as at the completion date after a deal closes. The estimated price paid at completion is adjusted up or down for actual cash, debt and working capital.
What is leakage?
Any value that passes from the target company to the seller or its connected parties after the locked box date, such as dividends, fees or asset transfers, unless it is listed as permitted leakage.
Which is better for sellers?
Sellers usually prefer a locked box because the price is certain and there is no true-up. It works best when the business has reliable recent accounts.
What is a working capital peg?
The normal level of working capital the buyer expects at completion. In a completion accounts deal, the price rises or falls by the difference between actual working capital and the peg.
Are completion accounts the same as a closing statement?
Broadly yes. US agreements usually call the process a closing statement or post-closing purchase price adjustment; the mechanics are similar.
Keep reading
Related analysis
Guides · M&A
M&A Transaction Costs: What to Budget When Acquiring a Business
The purchase price is only part of what an acquisition costs. Legal work, diligence, financing, insurance and filings add up, and most of the spend lands before you know the deal will close. This is how to budget for it, stage by stage.
Guides · M&A
W&I Insurance vs Escrow: How Buyers and Sellers Protect a Deal
Every acquisition carries a question nobody can fully answer at signing: what if something the seller promised turns out to be untrue? Escrow, holdbacks and warranty and indemnity insurance are three answers. They move risk to different places, and they suit different deals.
Guides · M&A
Enterprise Value vs Equity Value: From Headline Price to Cash in Hand
A buyer says "we value your business at $20 million". The owner hears $20 million in the bank. They are usually talking about two different numbers. Enterprise value prices the business; equity value is what the shareholders receive. The bridge between them decides the cheque.
Research · Research
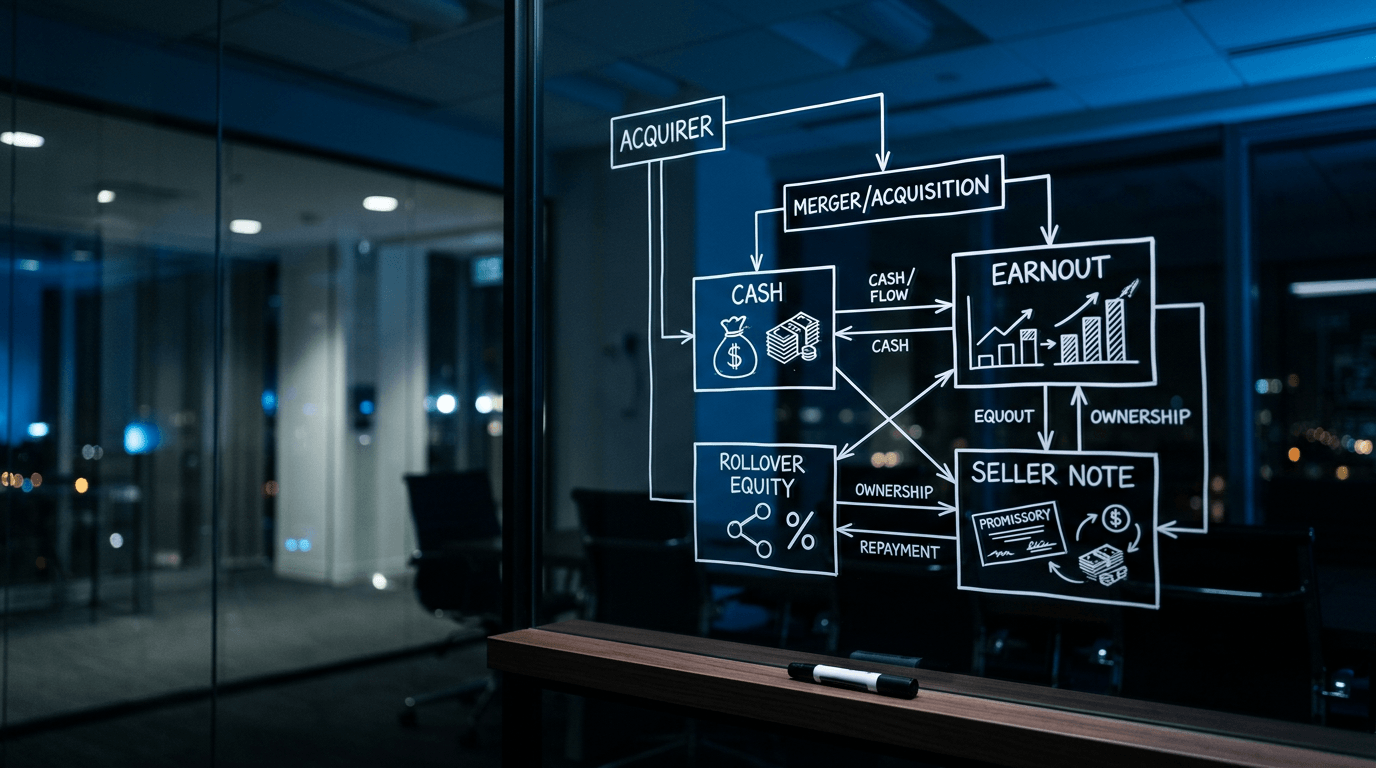
Deal Structure Playbook
Market benchmarks for earnouts, rollovers, seller notes, and working capital adjustments in digital asset M&A.
Explore the sector:/acquisitions//exits/
About the analyst
Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, an M&A firm built around buy-side acquisition origination. He works with strategic acquirers, private equity firms and advisers supporting buyers on mandates from USD $1M to $500M. Most of the work sits in technology, SaaS, fintech, payments, gaming and digital assets, and it is not limited to them: any sector, any market.