Summary
Summary
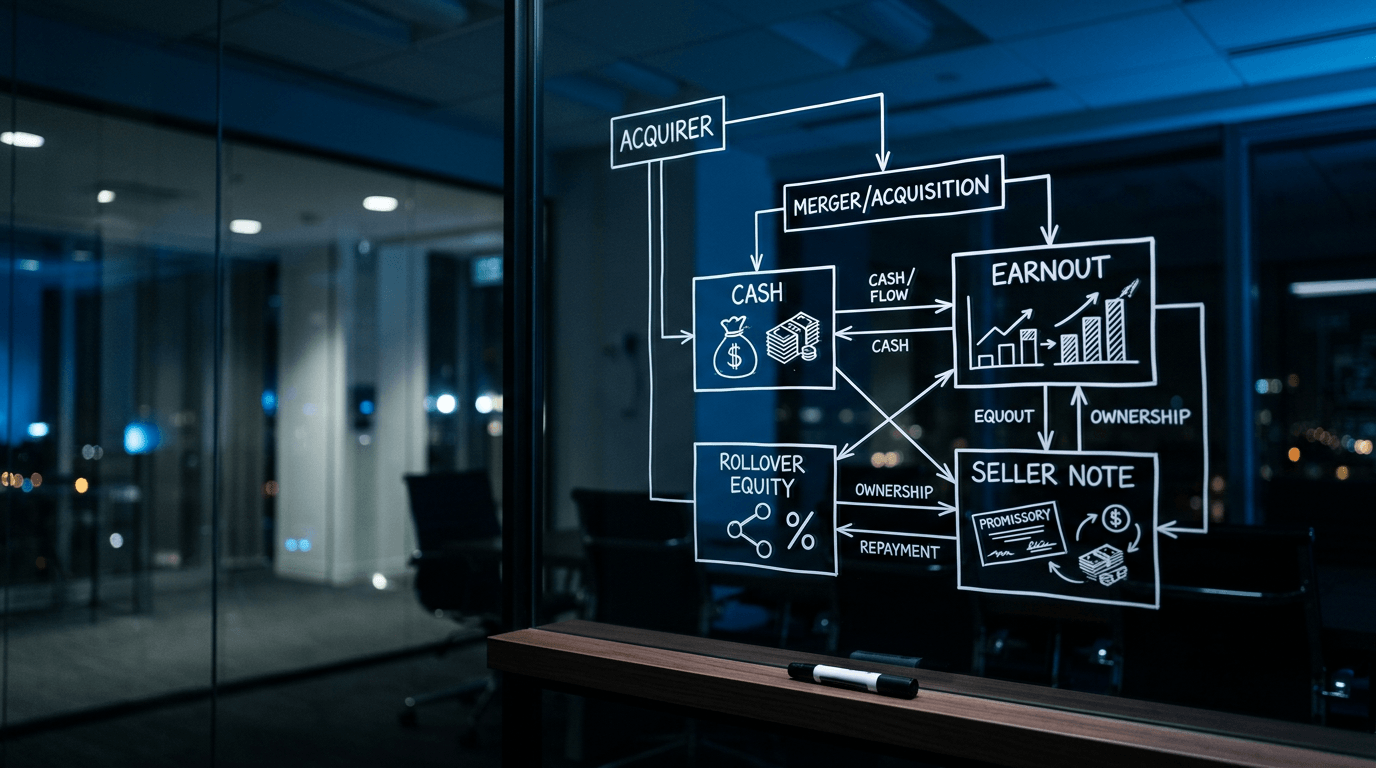
- Between 40% and 60% of digital deals include an earnout, usually 10% to 40% of enterprise value.
- Earnouts commonly run 12 to 36 months; sellers prefer revenue triggers, buyers prefer EBITDA.
- Escrow or retention of 5% to 15% of EV for 12 to 18 months is standard for warranty claims.
- The working capital definition is the most common source of post-close disputes.
01 · Research
Executive Summary
Deal structure is a primary lever in digital M&A. How consideration is split between cash at close, earnout, rollover equity, and seller notes directly affects the risk profile for both buyer and seller. Understanding market norms for each component allows both parties to negotiate from an informed position and avoid structures that are commercially unusual or legally fragile.
02 · Research
Structural Archetypes
| Structure | Typical Use Case | Buyer Profile |
|---|---|---|
| Cash Heavy (>80% cash) | Stable, profitable business with clean financials and low integration risk. | Strategic acquirer or PE with high conviction. |
| Cash + Earnout | High-growth business with uncertain forward performance. | Buyer wants to share risk on future performance. |
| Cash + Rollover | Founder-led business where key person retention is critical. | PE or strategic acquirer wanting founder aligned post-close. |
| Majority Recap | Founder wants liquidity but retains upside in a second bite. | PE firm executing a majority recapitalization. |
| Growth Equity | Business needs capital to scale, founder retains majority control. | Growth equity or venture investor. |
03 · Research
Earnout Benchmarks
| Parameter | Market Range | Note |
|---|---|---|
| Prevalence | 40-60% of digital deals include an earnout | More common in growth-stage and founder-led businesses. |
| Earnout Size | 10-40% of total EV | Higher earnout = more risk transferred to seller. |
| Duration | 12-36 months | Shorter durations are seller-preferred. |
| Trigger Metric | Revenue or EBITDA | Revenue triggers are seller-preferred; EBITDA triggers are buyer-preferred. |
04 · Research
Rollover, Seller Notes & Escrow Norms
| Component | Typical Range | Key Considerations |
|---|---|---|
| Equity Rollover | 10-30% of EV | Governance rights, drag-along, and tag-along provisions are critical negotiation points. |
| Seller Note Interest | 6-10% per annum | Subordinated to senior debt. Typically 2-4 year term. |
| Escrow / Retention | 5-15% of EV | Held for 12-18 months to cover warranty and indemnity claims. |
| Working Capital Peg | Based on trailing 12-month average | Definition of "cash" and "debt" items is the most common source of post-close disputes. |
05 · Research
Choosing a Structure
Each component moves risk between buyer and seller. The right mix depends on what is hardest to verify about the business.
| If the main uncertainty is | Use | Why |
|---|---|---|
| Future growth | Earnout | Seller is paid for growth only if it happens. |
| Founder retention | Rollover equity | Founder shares in the upside of staying. |
| Undisclosed liabilities | Escrow or warranty insurance | Funds sit aside for claims. |
| Buyer financing capacity | Seller note | Seller funds part of the price, at interest. |
| Short-term trading | Working capital peg and completion accounts | Price adjusts to the balance sheet delivered at close. |
06 · Research
Negotiation Points That Decide Value
- Earnout definitionsFix the accounting policies, who controls spend and what happens if the business is integrated or sold. Vague definitions cause most earnout disputes.
- Acceleration clausesSellers should ask for the earnout to pay out in full if the buyer sells the business or breaches operating covenants.
- Rollover rightsMinority protections, tag-along and drag-along terms, and how the second exit is valued.
- Escrow releaseStaged releases (for example half at 12 months) reduce how long seller cash is locked up.
- Note securitySubordinated seller notes rank behind bank debt; ask for a guarantee or a step-up in rate on default.
Model the trade-offs with the Deal Structure Comparison and Earnout Modelling Tool.
07 · Research
Headline Price vs Real Value
A higher headline price with a large earnout can be worth less than a lower all-cash offer. Value each component at what it is likely to pay, discounted for time and risk, before comparing offers.
08 · Research
Work with Acquiry
Acquiry runs buy-side and sell-side mandates for digital businesses. We are not limited to the sectors or markets covered here: any sector, any market, bring it to us anyway. Start a mandate (opens in a new tab).
Reference
Frequently asked questions
How common are earnouts in digital M&A?
In Acquiry's observed deal flow, 40% to 60% of digital deals include an earnout, more often in growth-stage and founder-led businesses.
How big is a typical earnout?
Usually 10% to 40% of total enterprise value, paid over 12 to 36 months against revenue or EBITDA targets.
How much escrow is normal in an acquisition?
Commonly 5% to 15% of enterprise value, held for 12 to 18 months to cover warranty and indemnity claims. Warranty insurance can reduce it.
What causes most post-close disputes?
The working capital adjustment, specifically how cash-like and debt-like items are defined. Agree the definitions in the LOI.
Keep reading
Related analysis
Research · Research
Buyer Underwriting Checklist
A structured checklist for pre-LOI, commercial, technical, and legal diligence on digital asset acquisitions.
Research · Research
Deal Team Operating Model
Our repeatable process architecture for executing buy-side and sell-side mandates from intake to close.
Research · Research
International Deal Structuring Notes
High-level notes on M&A mechanics in key global markets for digital assets.
About the analyst
Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.