Summary
Summary
- A seller note, also called vendor finance or a vendor loan note, is part of the purchase price the buyer pays later, with interest, under a written loan agreement.
- The seller usually ranks behind bank debt. If the business struggles, the bank is repaid first and the seller may be barred from collecting or enforcing for a period.
- Protection comes from four places: security over assets, guarantees from people or companies with money, covenants that limit what the buyer can do, and information rights that show trouble early.
- The intercreditor or subordination agreement with the senior lender often matters more than the note itself, because it decides when the seller can be paid and act.
- Treat a seller note as a credit decision. Review the buyer's capital structure, cash-flow cover and fallback options as a lender would.
01 · Guides
What seller financing is and why it is used
Part of the price, paid later, as a loan.
In seller financing, the seller accepts a promissory note for part of the purchase price instead of cash at completion. The buyer, usually the acquiring company or a new holding company, repays the note over an agreed term with interest. Unlike an earnout, the amount is fixed: the seller is owed it whether or not the business hits targets, as long as the buyer can pay.
- Bridges a funding gapLenders and equity partners may not fund the full price. A note fills the gap.
- Signals confidenceLenders and buyers often read a seller note as a sign the owner believes in the business.
- Supports a higher priceBuyers may pay more in total if some is deferred.
- Spreads taxIn some jurisdictions instalment treatment can spread the seller's tax over the payment period. Take tax advice; rules vary widely.
02 · Guides
Where the note ranks
Most seller notes sit behind the bank.
If the buyer uses bank or private credit, the senior lender will almost always require the seller note to be subordinated: the senior lender is repaid first and holds first-ranking security. The terms are set out in an intercreditor or subordination agreement signed by the lender, the seller and the borrower.
| Rank | Layer | Usual position |
|---|---|---|
| 1 | Senior debt | First claim on cash flow and assets, first-ranking security |
| 2 | Mezzanine or junior debt (if any) | Behind senior, often with second-ranking security |
| 3 | Seller note | Subordinated; may have second- or third-ranking security, or none |
| 4 | Rollover and new equity | Last; paid only after all debt |
Subordination terms usually limit when the seller can be paid (for example, only if the borrower is within its covenants with the senior lender) and impose a standstill: a period during which the seller cannot enforce even if the buyer defaults on the note. Some lending programmes require seller notes to be partly or fully on standby, meaning no payments for a set time. Check the specific lender's requirements early, because they shape everything else.
The capital stack builder shows how each layer is funded and repaid; the deal structure comparison compares a note against cash, earnout and rollover structures.
03 · Guides
The protections to negotiate
Security, guarantees, covenants and information.
| Protection | What it does | What to ask for |
|---|---|---|
| Security | Gives the seller a claim over assets if the note is not paid | Charge over shares and assets, ranking behind senior; share pledge over the target |
| Personal or parent guarantee | Someone with assets stands behind the note | Guarantee from the buyer's principals or parent company, with evidence of means |
| Financial covenants | Early warning that cash flow is weakening | Minimum cash or leverage tests mirroring the senior facility |
| Negative covenants | Stop the buyer moving value out | Limits on dividends, management fees, new debt, asset sales and acquisitions while the note is outstanding |
| Information rights | Let the seller see trouble early | Monthly management accounts, annual accounts, copies of lender compliance certificates |
| Events of default | Define when the note is in default | Missed payment, insolvency, change of control, breach of covenants, cross-default to senior debt |
| Acceleration | Make the whole balance payable on default | Full acceleration, subject to the intercreditor standstill |
| Change-of-control repayment | Get paid if the business is sold again | Mandatory repayment on any sale of the business or its main assets |
| Set-off limits | Stop the buyer withholding note payments for disputed claims | Set-off only for agreed or determined warranty claims |
04 · Guides
Commercial terms that change the risk
Interest, term, amortisation and size.
- SizeThe larger the note as a share of the price, the more the seller is exposed. Keep cash at completion sufficient to meet personal priorities on its own.
- TermShorter terms reduce exposure. Long terms with a single balloon payment concentrate risk at the end.
- AmortisationRegular principal repayments reduce exposure over time; interest-only notes leave the full balance outstanding.
- InterestShould reflect the risk of a subordinated loan. Some notes pay interest in kind (added to the balance) rather than in cash.
- PrepaymentAllowing early repayment without penalty can help the buyer refinance and pay the seller out sooner.
A hypothetical comparison
| Row | Note A | Note B |
|---|---|---|
| Term | 3 years | 5 years |
| Repayment | Quarterly amortisation from month 6 | Interest only, balloon at year 5 |
| Security | Second-ranking charge and share pledge | Unsecured |
| Guarantee | Parent company guarantee | None |
| Balance after 2 years | About $0.8M | $2.0M |
Both notes have the same face value, but Note A reduces the seller's exposure quickly and gives recourse if something goes wrong. Note B leaves the whole amount at risk for five years.
05 · Guides
Underwrite the buyer like a lender would
A note is credit; treat it as such.
- 1.Ask for the buyer's full sources and uses of funds, including senior debt terms
- 2.Review projected debt service: can the business pay senior debt and the note from cash flow, with headroom?
- 3.Check the buyer's track record and, if a sponsor, its capital partners; see evaluating independent sponsor offers
- 4.Understand any planned changes: new debt, acquisitions or management fees that compete with note payments
- 5.Agree a clear path if things go wrong: notice, cure periods and what happens under the standstill
The LOI value decoder separates cash at completion from deferred and contingent value, so a note can be compared fairly with other offers. For how deferred consideration fits into transaction budgeting, see M&A transaction costs.
Reference
Frequently asked questions
What is a seller note?
A loan from the seller to the buyer for part of the purchase price, repaid later with interest under a written agreement. It is also called vendor finance or a vendor loan note.
Is a seller note secured?
Only if negotiated. Sellers can ask for a charge over assets and a share pledge, usually ranking behind the senior lender, plus guarantees from the buyer's principals or parent.
What does subordinated mean for a seller note?
The senior lender is repaid first, and the seller's right to receive payments or enforce is limited by an intercreditor or subordination agreement.
What is a standstill period?
A period set in the intercreditor agreement during which the seller cannot enforce the note after a default, giving the senior lender time to act first.
How is a seller note different from an earnout?
A seller note is a fixed debt the buyer owes regardless of performance. An earnout is paid only if agreed performance targets are met.
Can a buyer stop paying a seller note because of a warranty claim?
Only if the documents allow set-off. Sellers should limit set-off to claims that are agreed or finally determined.
Keep reading
Related analysis
Guides · M&A
Independent Sponsor Offers: How to Evaluate a Buyer Without a Fund
An independent sponsor is a dealmaker who finds a company first and raises the money second. Many close excellent deals and bring real operating experience. Others never assemble the capital. For an owner, the task is to tell the difference before granting exclusivity.
Guides · M&A
W&I Insurance vs Escrow: How Buyers and Sellers Protect a Deal
Every acquisition carries a question nobody can fully answer at signing: what if something the seller promised turns out to be untrue? Escrow, holdbacks and warranty and indemnity insurance are three answers. They move risk to different places, and they suit different deals.
Research · Research
Deal Structure Playbook
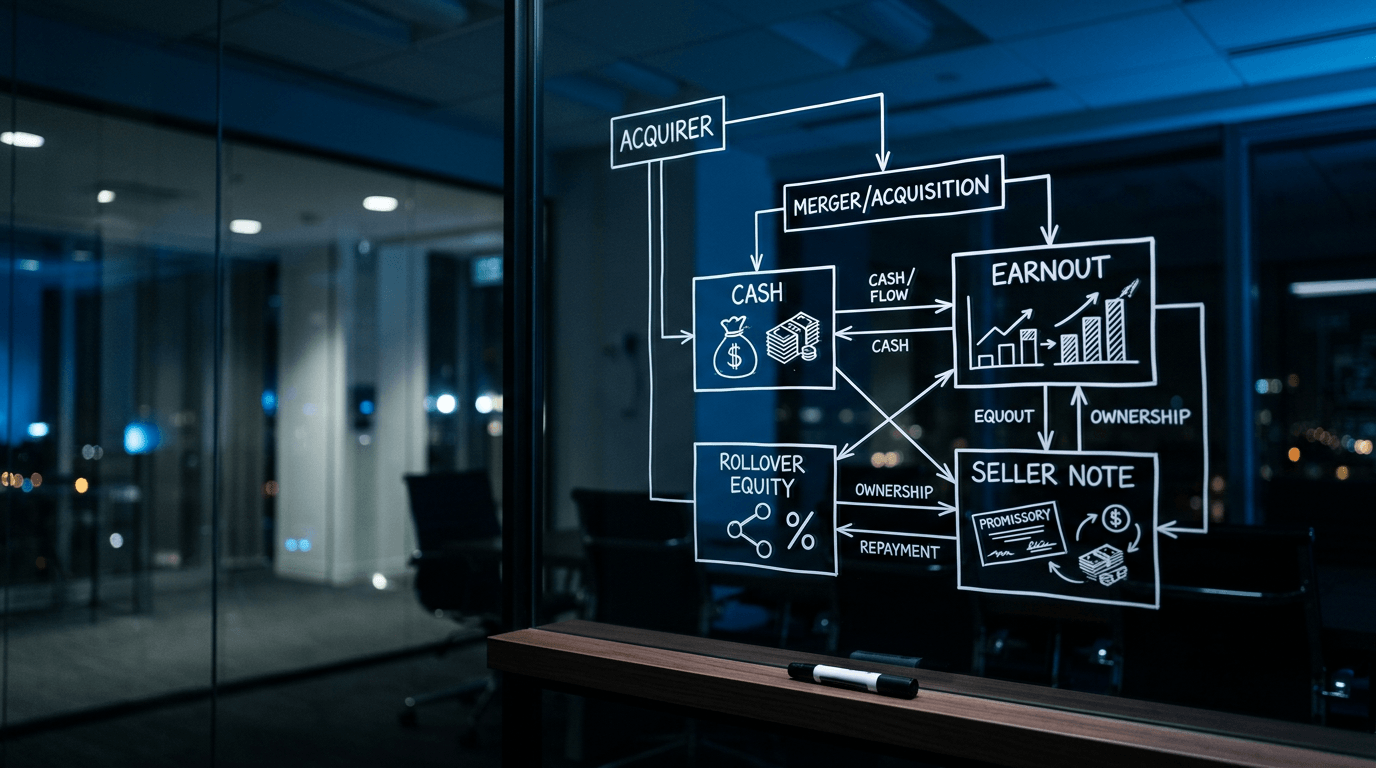
Market benchmarks for earnouts, rollovers, seller notes, and working capital adjustments in digital asset M&A.
Guides · M&A
M&A Transaction Costs: What to Budget When Acquiring a Business
The purchase price is only part of what an acquisition costs. Legal work, diligence, financing, insurance and filings add up, and most of the spend lands before you know the deal will close. This is how to budget for it, stage by stage.
About the analyst
Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, an M&A firm built around buy-side acquisition origination. He works with strategic acquirers, private equity firms and advisers supporting buyers on mandates from USD $1M to $500M. Most of the work sits in technology, SaaS, fintech, payments, gaming and digital assets, and it is not limited to them: any sector, any market.