
01 · Deal Intelligence
What Winvia is buying
Winvia signed an asset purchase agreement on 28 September 2026 for the trade, business and key assets of The Giveaway Guys and Win Life, with £19.1m of disclosed cash and an extra earnout the announcement does not cap.
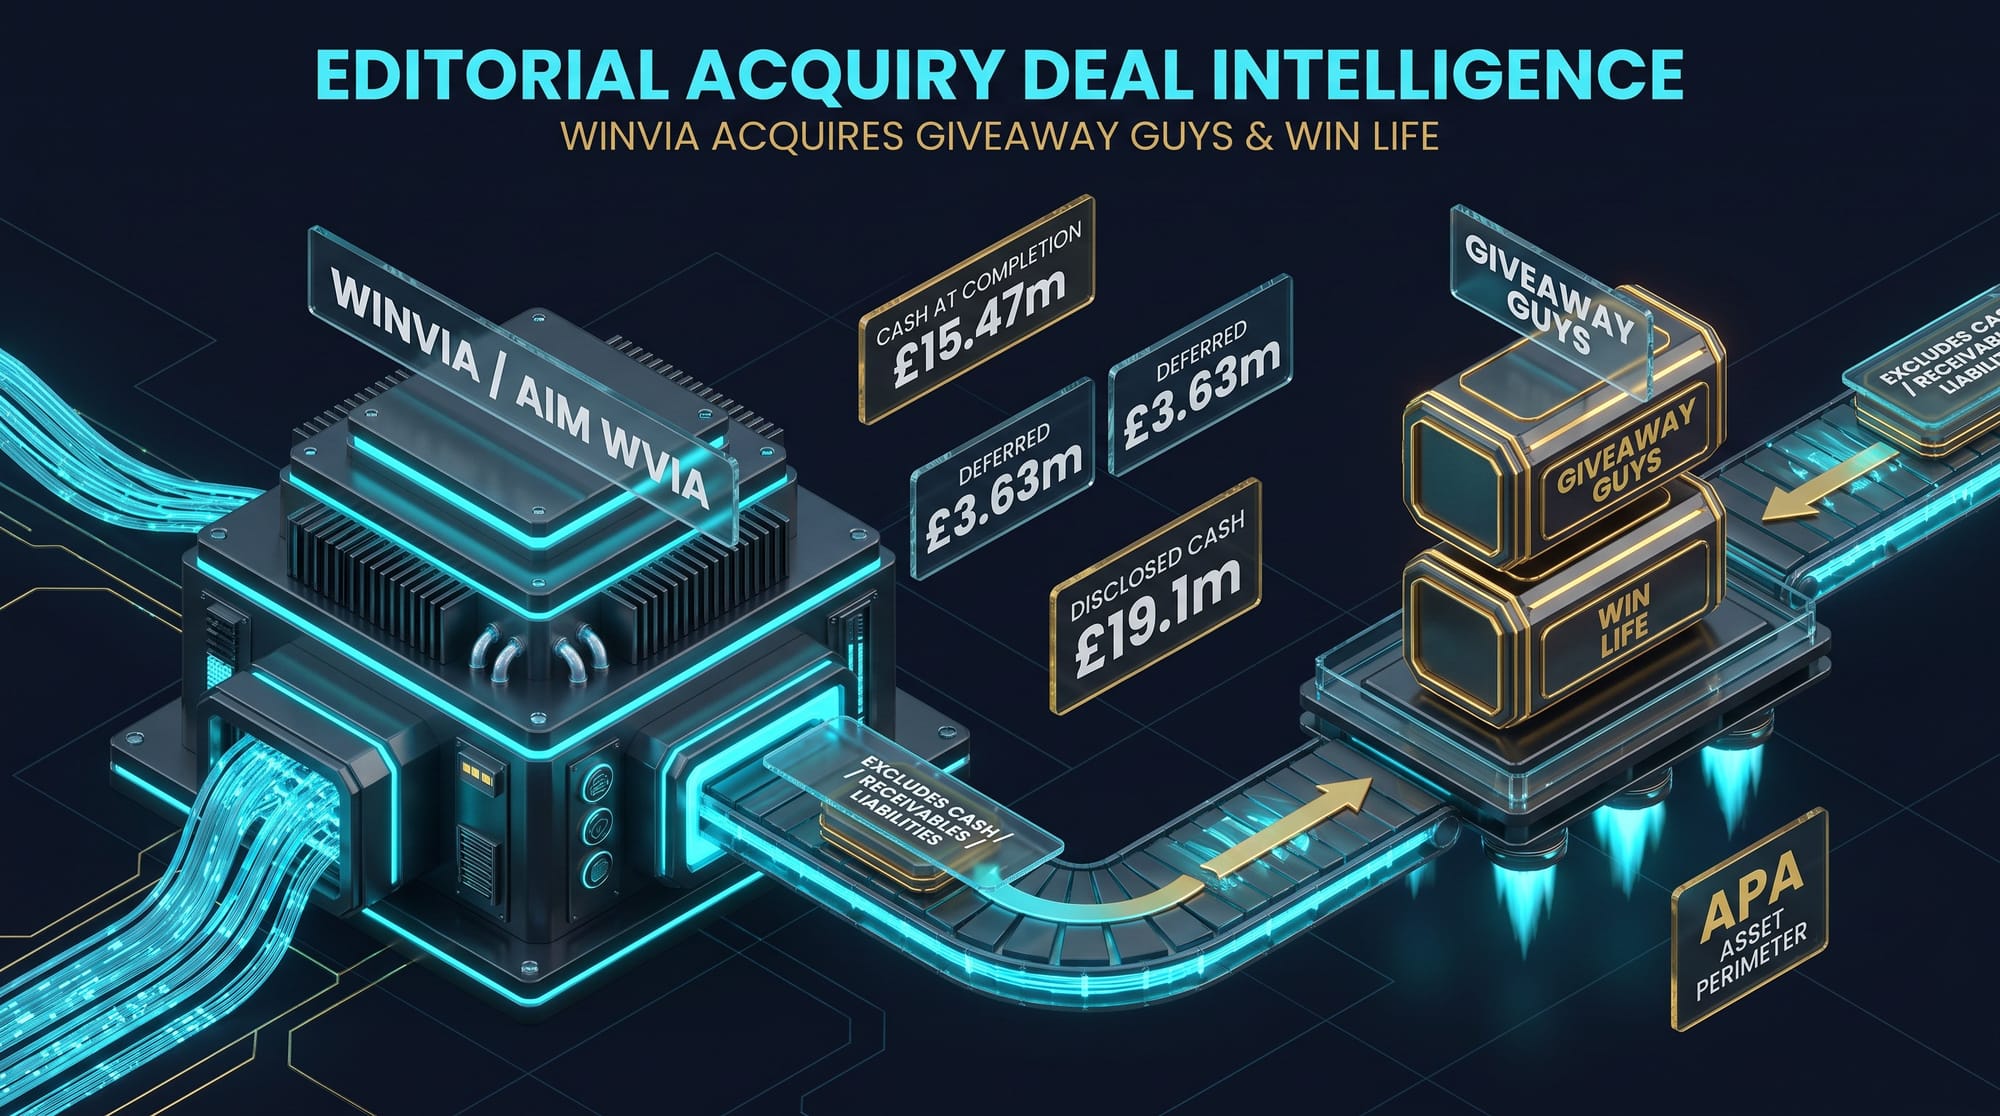
('Winvia Entertainment (AIM': 'WVIA) is a technology-led entertainment group with two published channels, UK prize-draw competitions and regulated online gaming in Romania. On 28 September 2026 it told the market it had signed an asset purchase agreement with The Online Giveaway Guys and Win Life Competitions Limited. The object is the trade, business and key assets. Liabilities, cash and trade receivables stay with the sellers. That is a ring-fenced asset deal, not a share purchase of the two companies.')
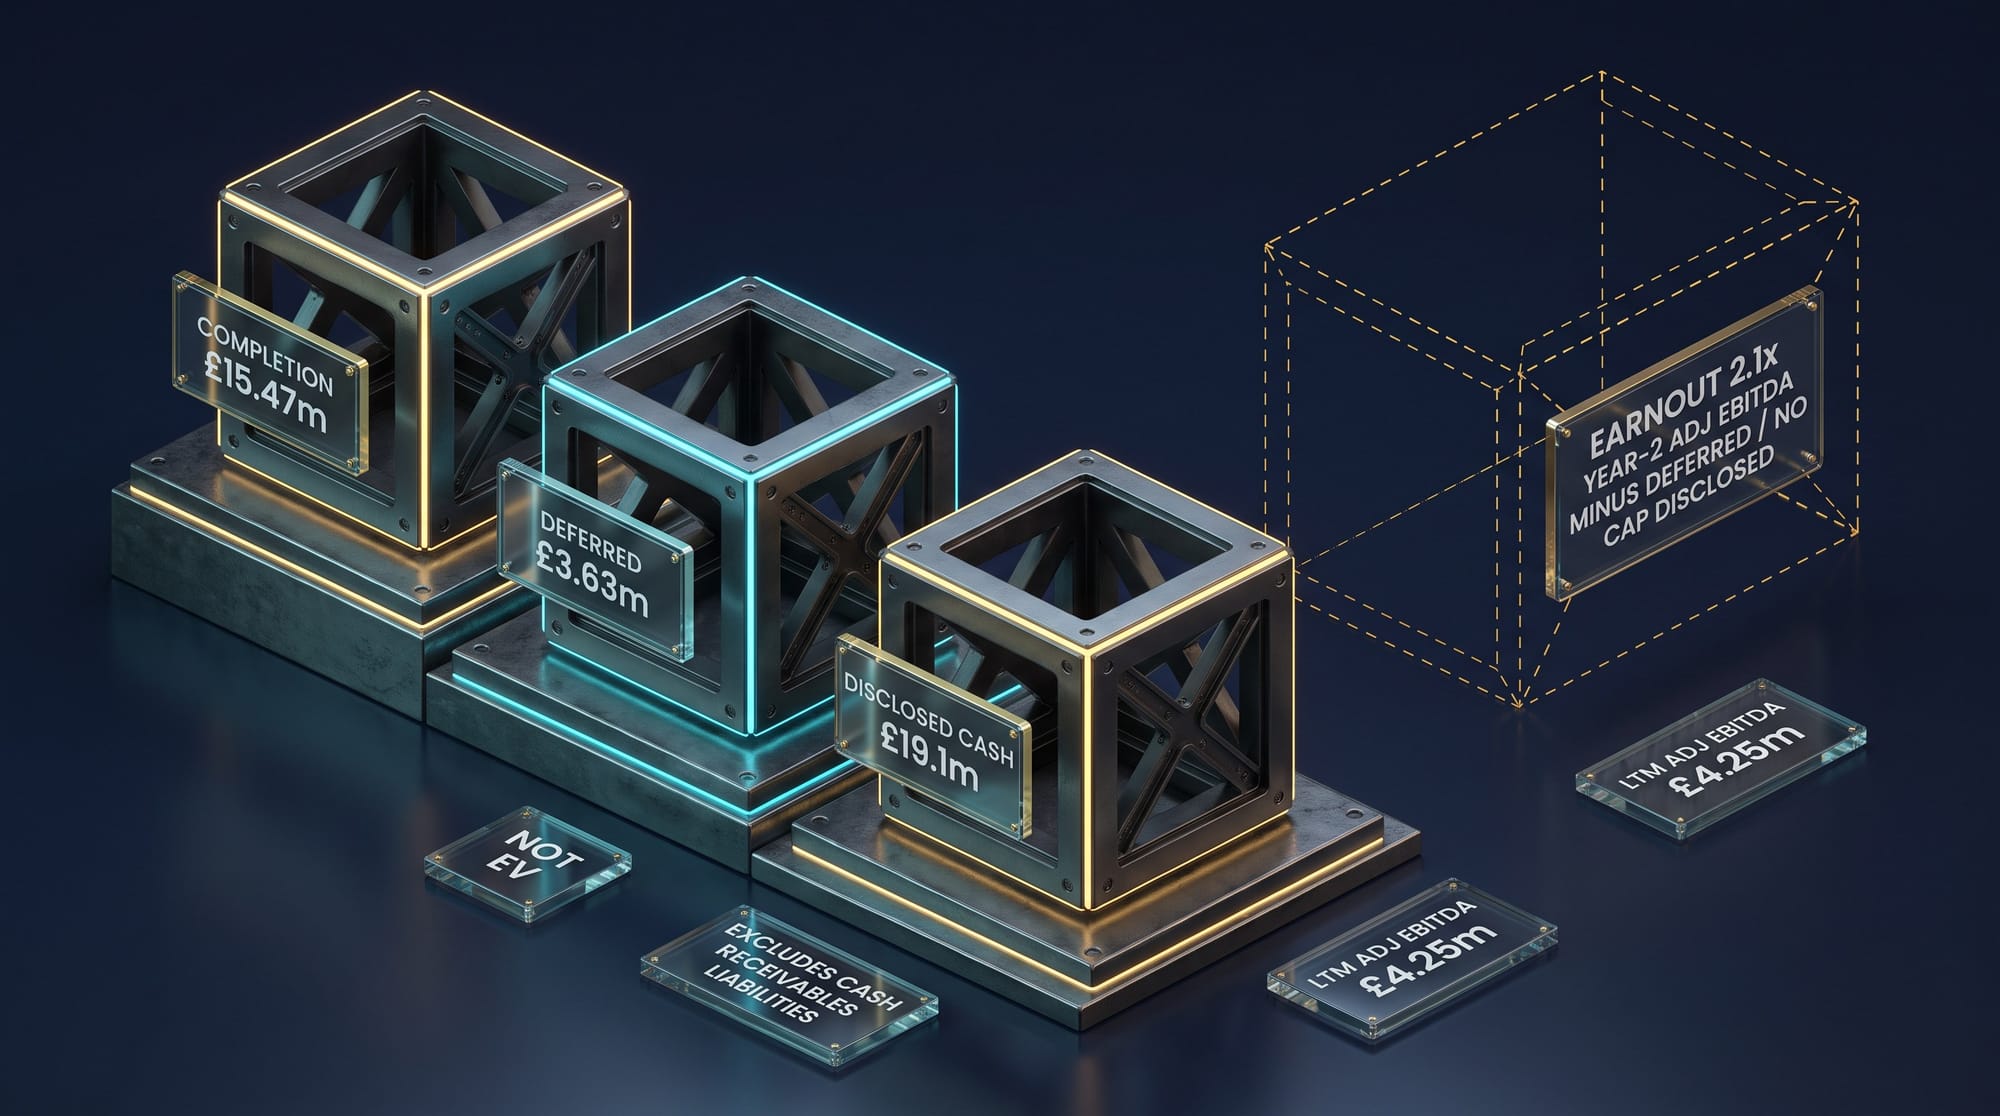
Law360's headline calls the targets online lottery companies and prices the deal at up to £19.1m ($25.3m). The RNS is more precise, and less convenient. The £19.1m is a cash purchase price built from £15.47m at completion and £3.63m on the first anniversary. A potential earnout then applies to adjusted EBITDA in the twelve months ending on the second anniversary of completion, at 2.1 times that EBITDA minus the £3.63m deferred amount. There is no disclosed earnout cap. "Up to £19.1m" is the trade-press frame. It is not a ceiling.
The price is anchored to an agreed adjusted EBITDA of £4.25m and combined gross revenue of £30.3m for the twelve months to the end of June 2026. Dividing £19.1m by £4.25m produces about 4.5 times LTM adjusted EBITDA on the disclosed cash legs only. That is an Acquiry inference from two printed numbers. It is not an enterprise value. Cash, receivables and liabilities are excluded from the perimeter, so inverting the cash price into EV is the wrong arithmetic.
The Giveaway Guys launched in 2020 as a digitally-led UK prize-draw platform with daily and scheduled draws. Win Life is described by the buyer as a recently launched brand focused on campervans, with a strong base of recurring revenue. Both are currently owned by Peter Toye. Win Life sits as a 100% subsidiary of TOGG. The operator sites themselves describe raffle-style ticketed draws, live-streamed winner selection and a free postal-entry route. That is the UK prize-draw model, not a Gambling Commission lottery licence.
Completion is not automatic. It is conditional on the transfer of key supplier agreements, expected by the end of October 2026. The announcement does not name the suppliers. Certain employees will remain inside the wider group after completion. Funding is existing cash, not a new equity issue and not, on the face of this RNS, a draw on the Barclays acquisition facility disclosed in the same-day half-year results.
“This acquisition represents another significant step in delivering our strategy to build a leading position in the UK prize draw market.” - Mihai Manoila, Chief Executive Officer, Winvia Entertainment (AIM RNS, 28 September 2026).
02 · Deal Intelligence
Why the businesses fit
Winvia is already a named consolidator in UK prize draws. The Giveaway Guys and Win Life are two more digitally-led brands in the same product, sold by a founder, at a cash multiple the announcement lets you calculate.
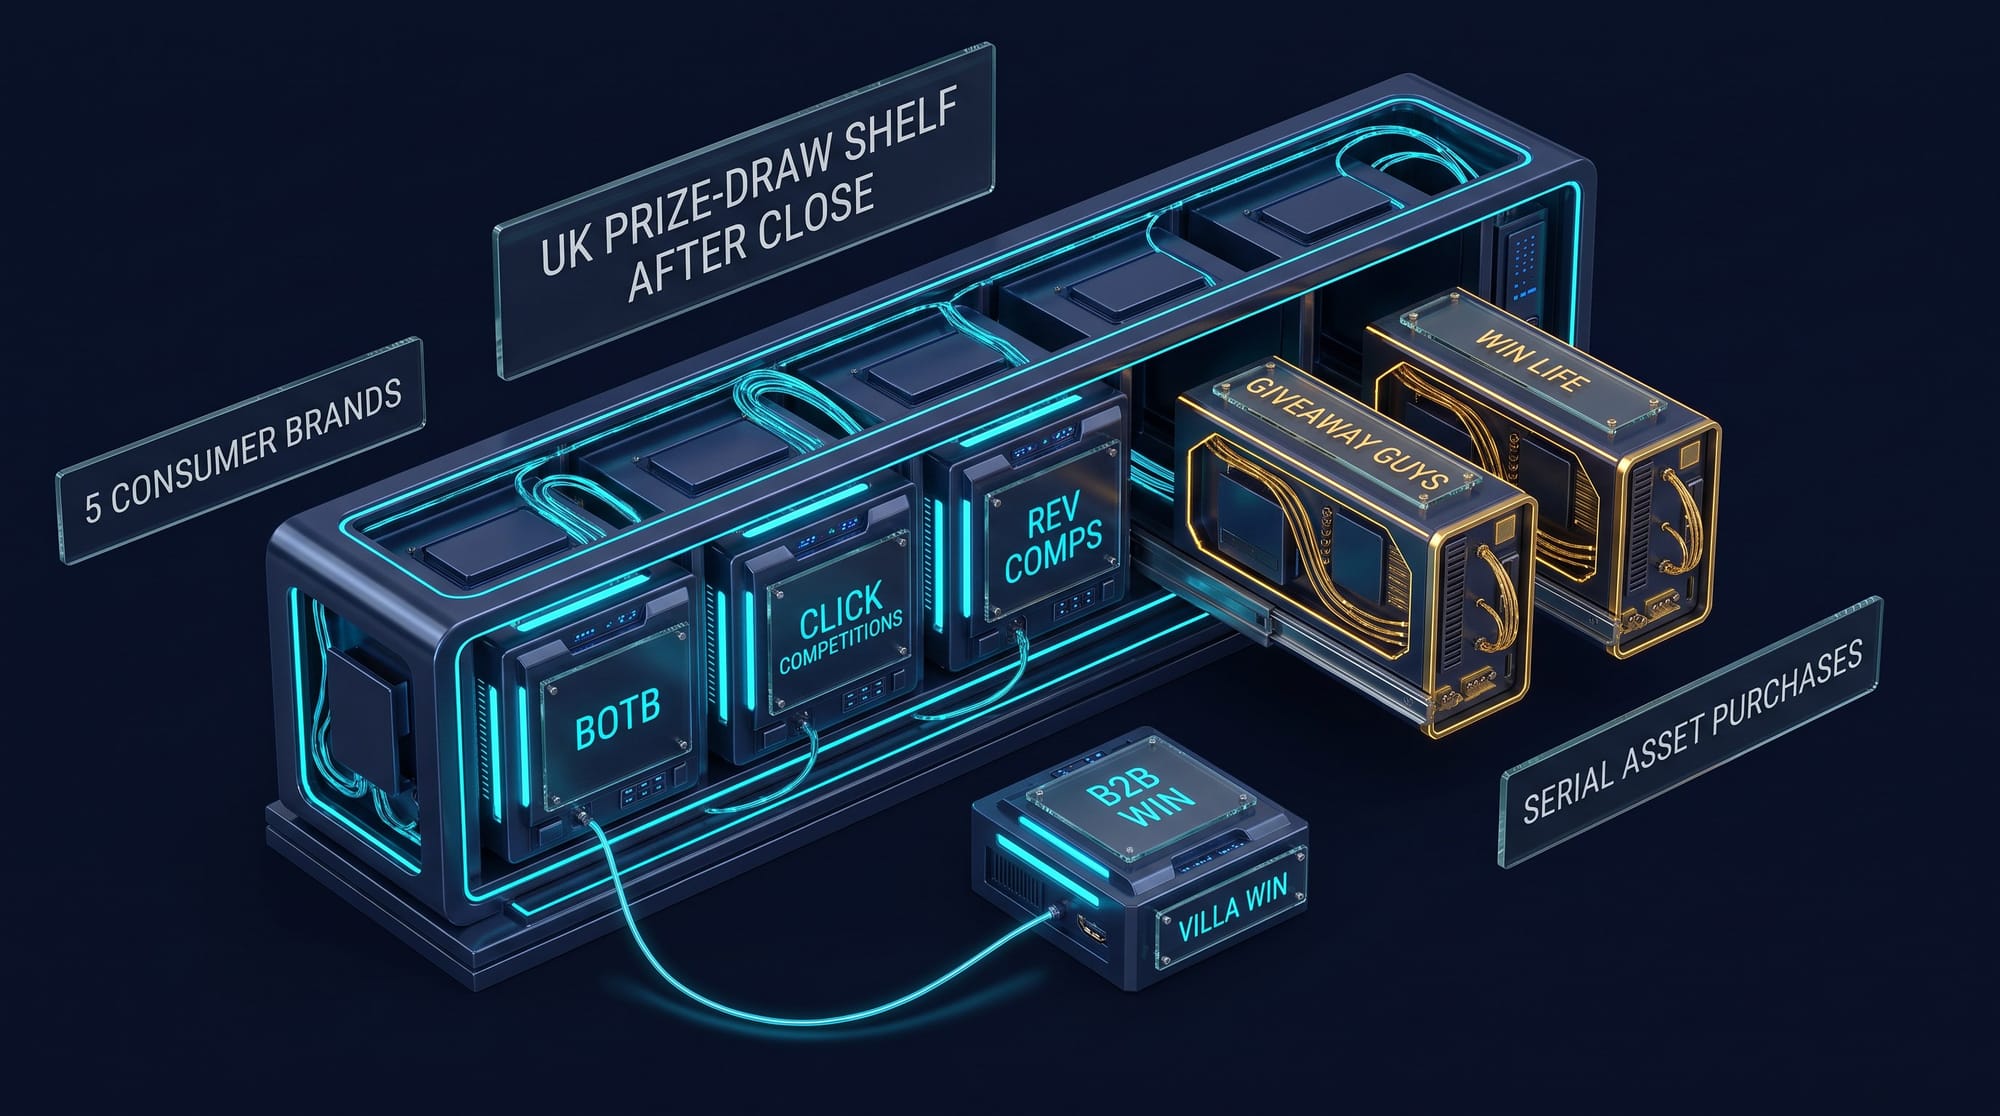
Fit is industrial, not conceptual. Winvia's published prize-draw shelf before this agreement is Best of the Best, Click Competitions and Rev Comps, plus a B2B rail in Villa Win with Aston Villa. Click completed in 2025. Rev Comps was an £11.8m cash asset purchase announced in May 2026, with migration onto Winvia's core platform as a completion condition. This deal is the same shape. Buy the brand and the player file as assets, keep selected people, put the tickets through the group stack.
The UK prize-draw market is the reason the cheque gets written. London Economics, commissioned by DCMS and published in June 2025, estimated 7.4 million UK adults had played prize draws and competitions in the prior twelve months, spending about £1.3bn, across at least 401 operators. One operator, Omaze, accounted for more than 60% of the surveyed player base. Best of the Best, Winvia's heritage brand, was 4.7% on that eleven-operator cut. Winvia's own RNS calls the group the UK's second-largest prize-draw operator by market share on that London Economics work. That claim is the buyer's. The underlying study shows a long tail of subscale operators, which is the acquisition map Winvia has been describing to investors since the AIM admission.
Economics are printed. Combined LTM gross revenue of £30.3m and agreed adjusted EBITDA of £4.25m sit behind a £19.1m cash price. On those two figures the cash legs are about 4.5 times LTM adjusted EBITDA. Acquiry inference, not a broker multiple and not EV. The earnout re-opens the price if the brands keep printing EBITDA. Hold LTM EBITDA flat at £4.25m into the year-2 measurement window and the formula 2.1 × £4.25m − £3.63m produces about £5.3m of extra cash. Total cash consideration would then be about £24.4m, or roughly 5.7 times the original LTM EBITDA. That illustration is Acquiry arithmetic on disclosed inputs. It is not a company forecast. No earnout cap is disclosed, so strong delivery costs more.
What the targets add is distribution Winvia does not have to build from zero. The Giveaway Guys already run live-streamed, fixed-odds draws with published entry lists. Win Life concentrates the same mechanic on campervans and a recurring-revenue claim the buyer made but did not quantify. Complementary prize verticals inside one customer type. Winvia already sells cars, property, travel, gadgets, luxury goods and cash through BOTB and Click. Campervan density and a second live-draw community are the incremental files.
What Winvia adds the other way is a listed cash vehicle, a three-pillar technology stack, a subscription product in BOTB Pass, and a stated playbook for moving acquired brands onto that stack. The Rev Comps precedent matters here. Migration onto the group platform was a closing condition, not a year-two hope. This announcement is softer on day-one migration. It talks about shared infrastructure, automation, new product features and subscription-led offerings after completion. Continuity of the live brands is the first operating requirement. Platform attach is the second.
03 · Deal Intelligence
How the technology fits
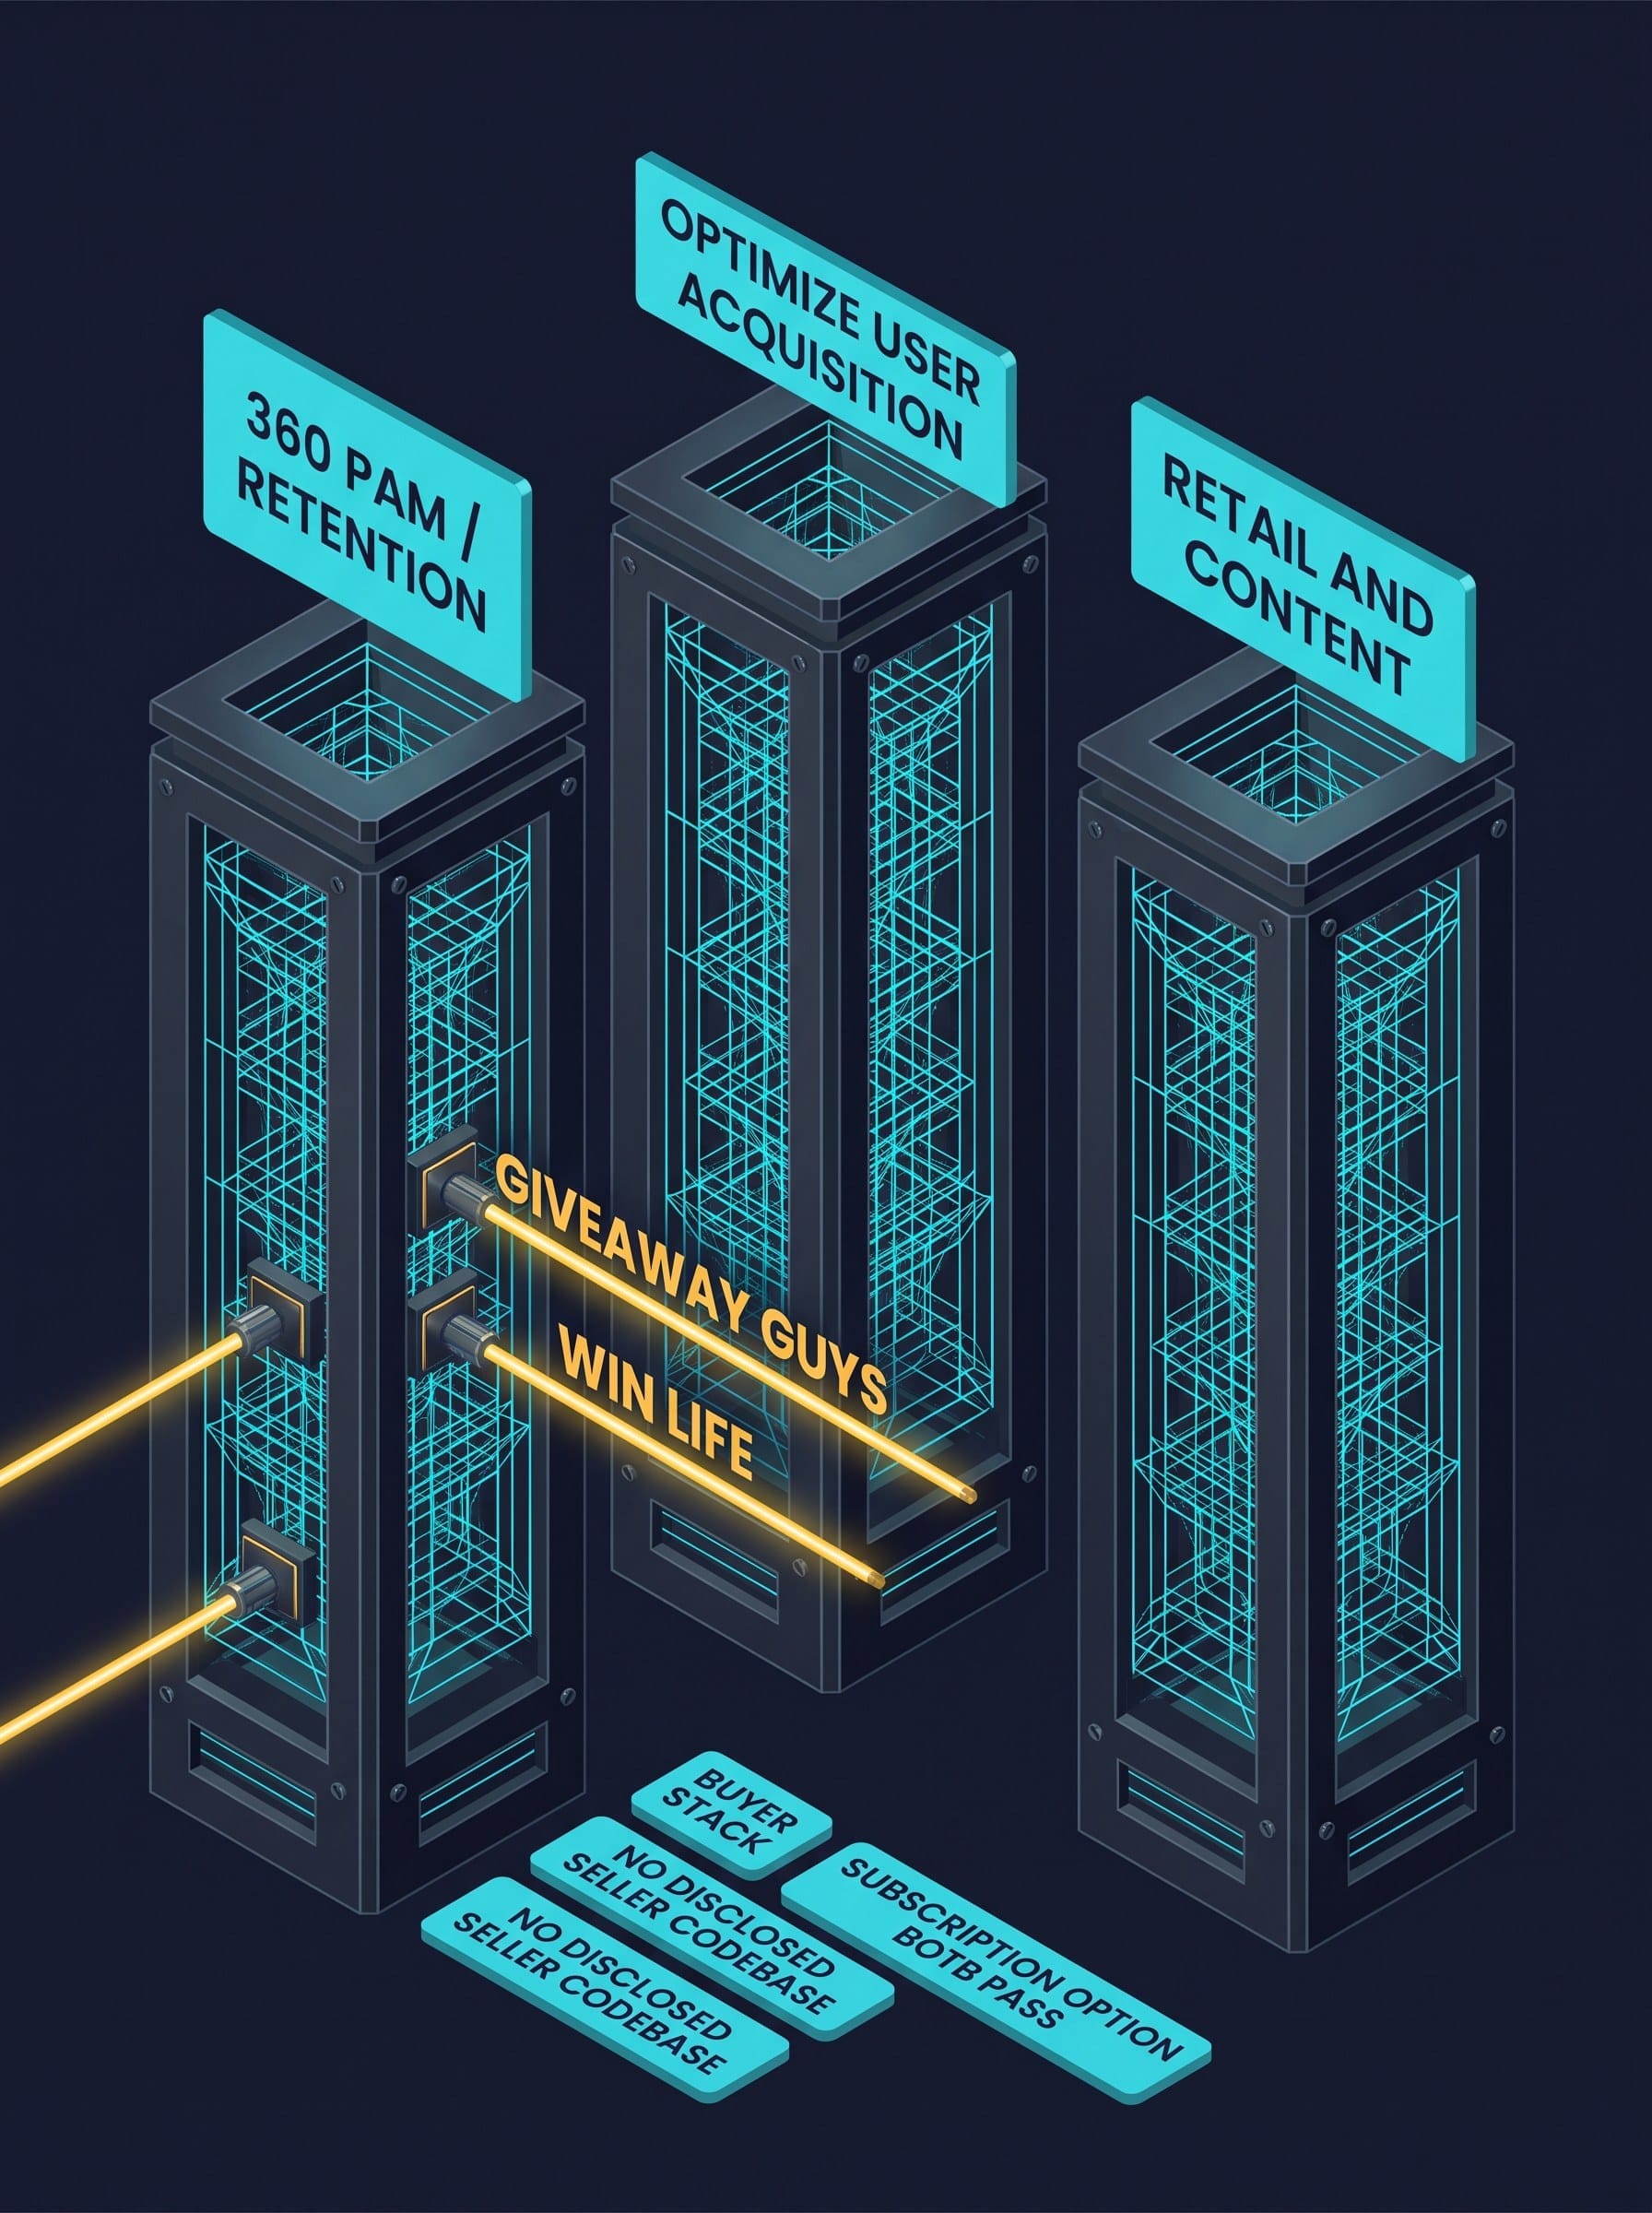
Winvia's public stack is a three-pillar in-house platform. The Giveaway Guys and Win Life are two more brand fronts that can, in principle, sit on it. Connecting them is a migration job, not a new engine.
Prize-draw technology is a ticket, wallet, draw-integrity and performance-marketing problem. Operators sell numbered entries into a capped draw, take payment, run a verifiable random selection, ship a physical prize, and buy the next cohort of players. The Giveaway Guys and Win Life already do the front of that job. They publish entry lists, livestream draws, use RANDOM.org, and sell fixed-odds tickets. Winvia is not buying a new random-number method. It is buying two live brand machines it can attempt to run on software it already paid to build.
The buyer's published stack has three named pillars. 360 is the customer-management, engagement and retention layer, with an attribution engine, journey automation, bonus and rewards, CMS, gamification and real-time analytics. Optimize is the performance user-acquisition and analytics layer, campaign management, testing, attribution modelling and conversion tracking. Retail and Content extends the same group into physical terminals and B2B content. Those pages are Winvia's own product marketing. They are not a due-diligence dump of the TOGG or Win Life codebases. The announcement does not describe the sellers' current platform, hosting or payment stack.
That gap is the integration risk. Rev Comps had to migrate onto Winvia's core platform before completion. This APA is conditional on supplier-agreement transfers, not on a disclosed day-one cutover. Shared infrastructure, automation, new product features and subscription-led offerings are the stated post-close plan. BOTB Pass, launched July 2025, is the subscription pattern Winvia will want to export. H1 2026 figures put BOTB Pass at more than 35% of monthly BOTB revenue and over 17% of prize-draw divisional revenue by 30 June. Those are group numbers, not Giveaway Guys numbers. Applying a subscription wrapper to a live-draw, campervan-led community is an operating choice after close, not a printed term of the APA.
The other half of Winvia's technology argument sits in Romania, not in UK prize draws. Online gaming on the same proprietary platform generated H1 2026 revenue of £88.7m and adjusted EBITDA of £20.4m, with 1.3 million active customers. That cash engine is why a £15.47m completion cheque is payable from existing resources. It is not why The Giveaway Guys are useful. Cross-selling Romanian casino brands into UK prize-draw players is not an announced plan and is not inferred here. The technology fit that is actually on the page is narrower. Two more UK prize-draw fronts, one buyer stack, one stated ambition to automate marketing and attach subscriptions.
Capability map
| Capability | Winvia before | Targets add | Together | |||
|---|---|---|---|---|---|---|
| Prize-draw brands | BOTB, Click Competitions, Rev Comps, Villa Win B2B | Giveaway Guys (2020) and Win Life (campervan rail) | Five consumer brands plus one B2B rail after close | |||
| Customer type | UK prize-draw players across cars | property | travel | luxury | Same mechanic, live-draw community, campervan density | Broader prize calendar inside one regulated-adjacent product |
| Economics | Group H1 2026 net revenue £109.7m, adj. EBITDA £17.2m, net cash £31.8m | LTM gross revenue £30.3m, agreed adj. EBITDA £4.25m | Cash-funded bolt-on against printed LTM earnings | |||
| Technology | In-house 360, Optimize, Retail and Content | Digitally-led draw engines, live-streamed winner selection | Buyer stack over two more brand fronts | |||
| Deal shape | Serial asset purchases. Rev Comps £11.8m cash in May 2026 | Asset APA, founder-owned, supplier-transfer gate | Same consolidator pattern, larger LTM EBITDA than Rev Comps | |||
| Capital | Existing cash. H1 net cash £31.8m covers the £15.47m completion cheque | No cash or receivables transferring in | Cash leaves Winvia. Working capital stays with Peter Toye |
04 · Deal Intelligence
Where Winvia can take the brands
Distribution leverage is domestic and already built. Winvia does not need a new country. It needs the two brands inside a five-brand UK prize-draw calendar, and onto the marketing machine that is already buying players for BOTB and Click.
The addressable market is the UK prize-draw sector DCMS had London Economics measure. 7.4 million adults, about £1.3bn of spend, 401 operators, one dominant consumer brand in Omaze. Winvia is not trying to take Omaze's 61% surveyed player share in a single cheque. It is buying density in the long tail. Cross-play is the distribution logic the growth-strategy page already states. Customers typically play on more than one site. A larger prize calendar across more fronts is supposed to lift marketing efficiency and let the group control draw timing.
Villa Win is the B2B version of the same idea. Aston Villa's supporter file is a media channel Winvia does not own. The Giveaway Guys and Win Life are consumer files it will own, subject to close. Putting those files onto Optimize, then offering BOTB Pass-style subscriptions and a shared prize pool, is the path. None of that is a named, contracted attach sale in the 28 September RNS. It is the industrial reason a consolidator pays 4.5 times printed LTM EBITDA in cash and still writes an earnout on year-two EBITDA.
There is no overseas distribution argument in this announcement. Win Life and The Giveaway Guys are UK digitally-led platforms. Winvia's other growth market is Romanian online gaming. Those are parallel channels on one technology group, not a single player passport. Anyone briefing this as a lottery-plus-sportsbook geographic expansion is reading the Law360 headline, not the RNS.
05 · Deal Intelligence
How the combination could work
Close is a supplier-agreement gate by the end of October 2026, then a £15.47m cash payment, then a year of brand continuity before the deferred cheque and a second year before the earnout formula can be run.
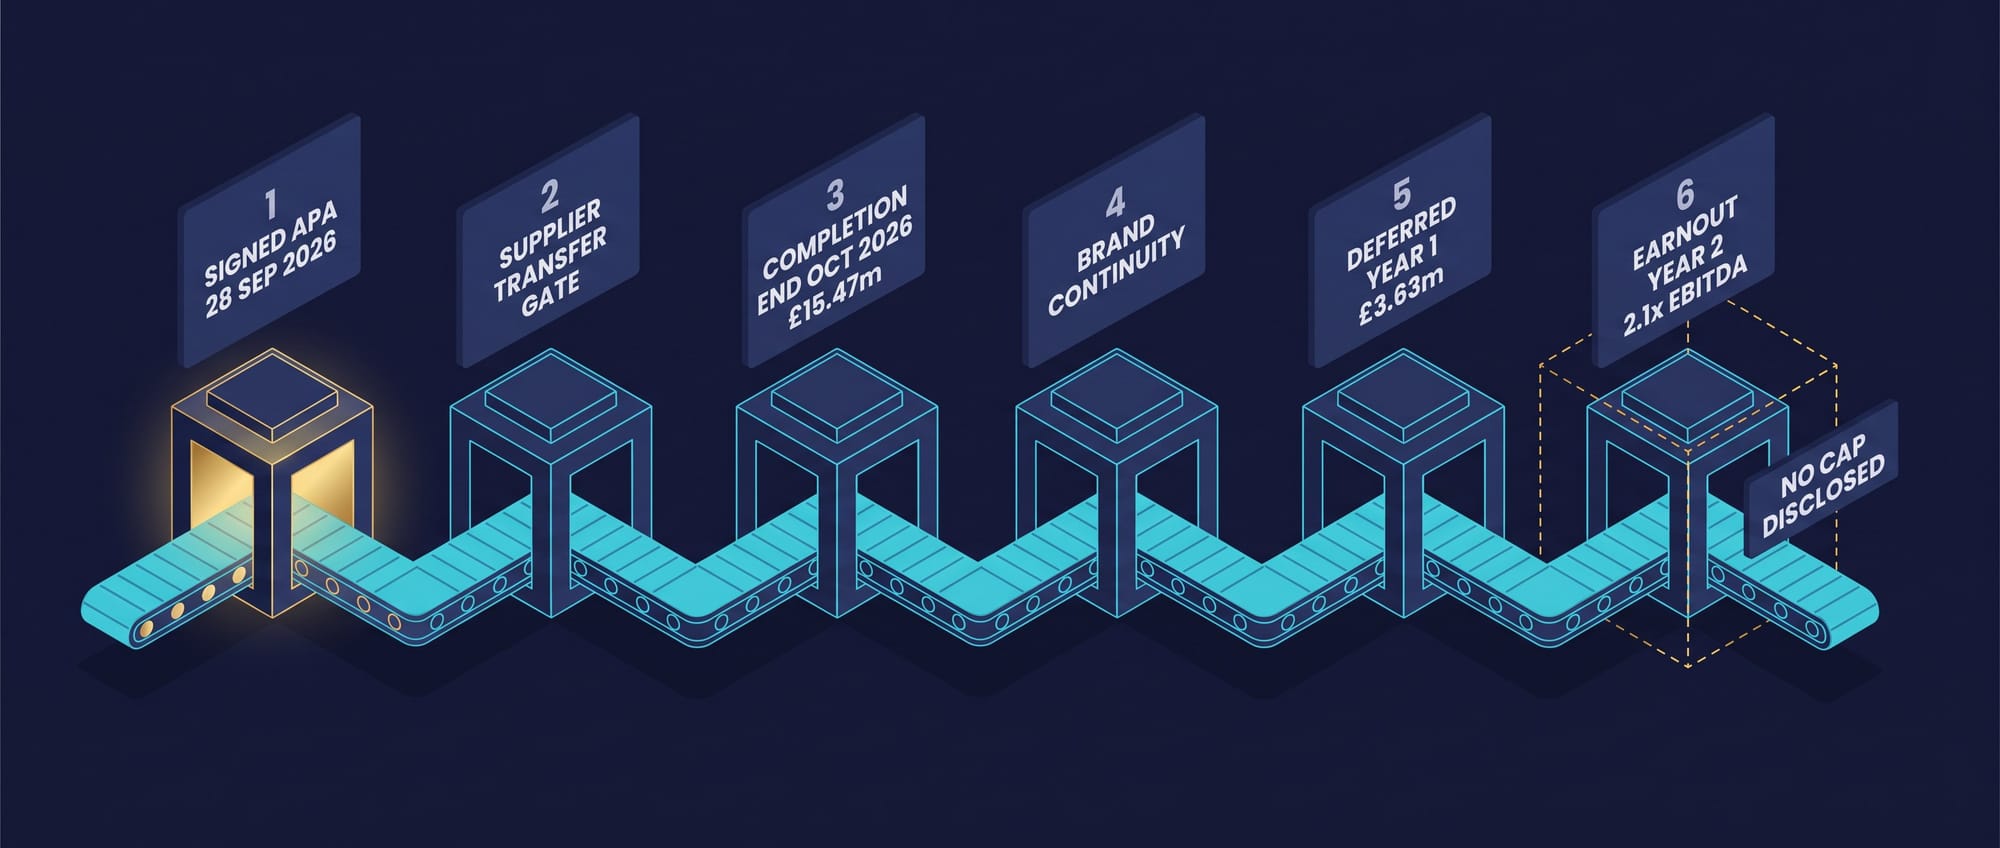
| Watch 1 | Transfer of the unnamed key supplier agreements inside the end-October 2026 window |
|---|---|
| Watch 2 | Completion confirmation and the £15.47m cash outflow from existing resources |
| Watch 3 | Retention of the selected TOGG and Win Life employees, and continuity of live-draw calendars |
| Watch 4 | Whether the two brands migrate onto 360 and Optimize, and on what timetable relative to the Rev Comps precedent |
| Watch 5 | First anniversary payment of the £3.63m deferred cash |
| Watch 6 | Year-two earnout calculation, 2.1 times achieved adjusted EBITDA minus deferred cash, with no cap disclosed |
| Watch 7 | Prize-draw divisional monthly adjusted EBITDA against the group's Q4 guide of close to £2m, which is a Winvia group figure, not a target-brand figure |
| Watch 8 | Any development on the contingent UK VAT question over prize-draw ticket sales disclosed in the half-year results |
The practical sequence is narrower than a typical regulated gaming combination. There is no disclosed competition filing, no lottery-licence transfer and no shareholder vote. The only named closing condition is transfer of key supplier agreements. Until those contracts novate, Winvia does not own the draws. The announcement does not identify the counterparties. Prize, payment, logistics and livestream suppliers are the obvious candidates. They are not confirmed.
Cash is the second gate. Group net cash was £31.8m at 30 June 2026. The completion cheque is £15.47m. Arithmetic says the balance sheet can write it without a placing. Arithmetic also says the deferred £3.63m and any earnout still have to be funded later. Same-day half-year results described a Barclays package of a £33m three-year term loan, a £5m revolving acquisition facility and an uncommitted £15m accordion. This RNS says existing cash. Mixing those two facts into a drawn facility would be an inference the announcement does not support.
Working, in this case, is unromantic. Draws keep running on the advertised dates. Live-streamed winner selection does not skip a Sunday. Selected employees stay. Brands keep their names long enough that the player file does not churn. Then the group has to decide whether Giveaway Guys and Win Life migrate onto 360 and Optimize on a Rev Comps timetable or continue on whatever stack they run today. The APA as summarised does not force that cutover as a closing condition.
The earnout is the seller's remaining leverage. 2.1 times year-two LTM adjusted EBITDA, minus £3.63m, with no printed cap, means Peter Toye is paid for delivery after ownership has already changed. It also means Winvia's final multiple is path-dependent. A badly integrated brand that loses EBITDA cheapens the earnout and damages the strategic case at the same time. A brand that holds or grows EBITDA costs more than the £19.1m headline. Both outcomes are inside the printed formula.
Acquiry view. The industrial logic is the easy part. UK prize draws are a £1.3bn consumer market with hundreds of operators and one dominant consumer name. Winvia is listed, funded and already on its third and fourth prize-draw asset deals in eighteen months. The Giveaway Guys and Win Life look like the product that programme is designed to buy. Digitally-led, founder-owned, subscale relative to a listed consolidator, and printing £4.25m of agreed adjusted EBITDA on £30.3m of gross revenue.
The forensic points sit in the structure. This is an asset deal, so historic liabilities stay out. The £19.1m is a cash price, not EV. Law360's "up to £19.1m" frame understates an uncapped earnout. Completion still depends on supplier contracts Winvia has not named. Migration onto the group platform is a stated ambition, not a closing condition. Those are not reasons the deal fails. They are the items that decide whether 4.5 times printed LTM EBITDA stays 4.5 times, or becomes a more expensive year-two story.
The best companies are acquired, not sold. These two brands look like that kind of asset for a consolidator that has already decided the UK prize-draw long tail is its near-term M&A calendar. The test after October is operational, not conceptual. Do the draws still run, does the player file stay, and does the stack actually take the tickets.
Reference
Frequently asked questions
Is Winvia buying lottery companies?
The Law360 headline says online lottery companies. The AIM announcement, the operator sites and the DCMS / London Economics study describe UK prize-draw competitions. Win Life's own terms state it is a prize draw with a free postal-entry route, not a lottery. No Gambling Commission lottery licence transfer is disclosed.
What is the £19.1m?
Disclosed cash purchase price of £15.47m at completion plus £3.63m deferred for one year. It is not stated as enterprise value. An additional earnout sits on top and is not capped in the RNS. Law360's "up to £19.1m" wording treats the cash legs as a ceiling. The printed formula does not.
How does the earnout work?
For the twelve months ending on the second anniversary of completion, the earnout is 2.1 times achieved adjusted EBITDA of TOGG and Win Life, minus the £3.63m deferred consideration. No maximum is disclosed. No EBITDA forecast for that window is disclosed.
When is close expected?
By the end of October 2026, conditional on transfer of key supplier agreements. The counterparties are not named. Until that condition is satisfied the APA has not completed.
Share deal or asset deal?
Asset purchase. Winvia is buying the trade, business and key assets. Liabilities, cash and trade receivables are excluded. Peter Toye remains the owner of the seller companies. Certain employees transfer into the wider group.
Can Winvia pay without raising equity?
The RNS says the acquisition is funded from existing cash resources. Group net cash at 30 June 2026 was £31.8m against a £15.47m completion cheque. Deferred cash and any earnout remain future outflows. Same-day results also described Barclays facilities. This announcement does not say those facilities are being drawn for this APA.
What is Winvia as a group?
AIM-listed since 3 November 2025. Prize-draw brands Best of the Best, Click Competitions and Rev Comps, plus Villa Win with Aston Villa. Online gaming in Romania through own brands including Princess Casino, Royal Slots and Luck, plus white-label and B2B. The buyer cites a London Economics / DCMS June 2025 report as the basis for calling itself the UK's second-largest prize-draw operator by market share.
Keep reading
Related analysis
Deal Intelligence · Gaming
CIRSA Acquires Slots del Sol and Opens a Paraguay Route for Omnichannel Gaming
CIRSA has acquired a majority stake in Slots del Sol, adding a Paraguay online casino and land-based footprint. Acquiry Deal Intelligence examines the disclosed facts, platform logic and execution agenda.
Deal Intelligence · Gaming
GiG Buys Control of 888AFRICA and Brings a B2C Growth Engine Into a Leaner iGaming Platform
GiG Software has proposed a €16.4m acquisition of 80% of 888AFRICA, backed by €8.5m of completed equity and convertible funding. Acquiry Deal Intelligence examines the disclosed terms, target operating metrics, integration agenda and source record.
Deal Intelligence · Gaming
Caesars Shareholders Approve Fertitta’s $17.6bn Take-Private
Acquiry analysis of Caesars Entertainment shareholders’ approval of Tilman Fertitta’s ~$17.6bn take-private: the $31.00 cash price, the ticking fee, the vote tally and the FTC review that now decides whether it closes.
Explore the sector:Gaming acquisitionsFintech M&A
About the analyst

Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.