
01 · Deal Intelligence
What Merkur is buying
Merkur is buying 95% of Casigrangi, the private holding company that already controls 81.21% of listed Société Française de Casinos, at a transparency price of €6.19 a share, with a mandatory cash tender to follow.
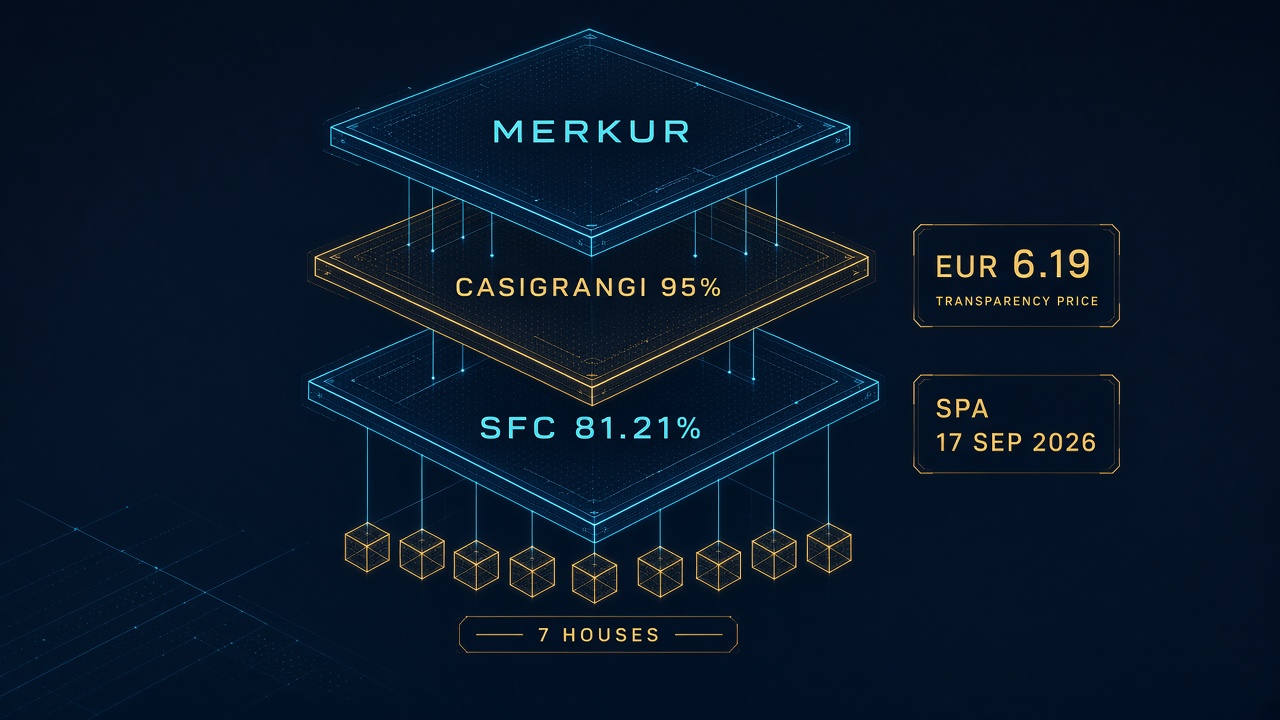
The legal wrapper is a sandwich. Merkur does not buy SFC shares from the market in this first step. It buys 95% of Casigrangi from GPG Groupe Philippe Ginestet and DOFA. Casigrangi holds the 4,135,434-share control block, counted against 5,092,470 SFC shares and theoretical voting rights as of 31 October 2025. DOFA keeps the remaining 5% of Casigrangi under reciprocal put and call options exercisable after completion.
The 27 August put-option announcement is where the price language is fullest. €6.19 is a 195.9% premium to the 240-day volume-weighted average closing price before 27 August 2026, 145.2% to the 60-day VWAP, and 157.9% to that day's close. Those premiums are company figures on the listed share, not a published enterprise value for Casigrangi. Casigrangi also operates three casinos in its own name. Multiplying 5,092,470 SFC shares by €6.19 produces about €31.5 million of SFC equity if every share were taken at the tender price. That €31.5 million is an Acquiry arithmetic check on the disclosed share count and the disclosed cash price. It is not the Casigrangi cheque, because the three direct Casigrangi houses sit outside that multiplication.
Employee steps for the first closing are already done. The social and economic committee of Casino de Gruissan gave a positive opinion on 2 September 2026. The mandatory information procedure with Casigrangi employees finished on 7 September. The SFC board will still form an ad hoc committee and appoint an independent expert under Article 261-1 I of the AMF General Regulations before it publishes a reasoned opinion on the later offer.
02 · Deal Intelligence
Why the businesses fit
Merkur already manufactures games and machines and operates casinos across Europe. Casigrangi and SFC add seven licensed French land-based houses Merkur does not currently run as a listed regional estate.
Merkur's 28 August statement is the industrial brief in one sentence. Casigrangi's track record and market expertise, combined with Merkur's pan-European footprint and technological capabilities, are "the ideal partnership to strengthen and expand its presence in France." That is a buyer saying France is a distribution problem it wants to own, not a supplier relationship.
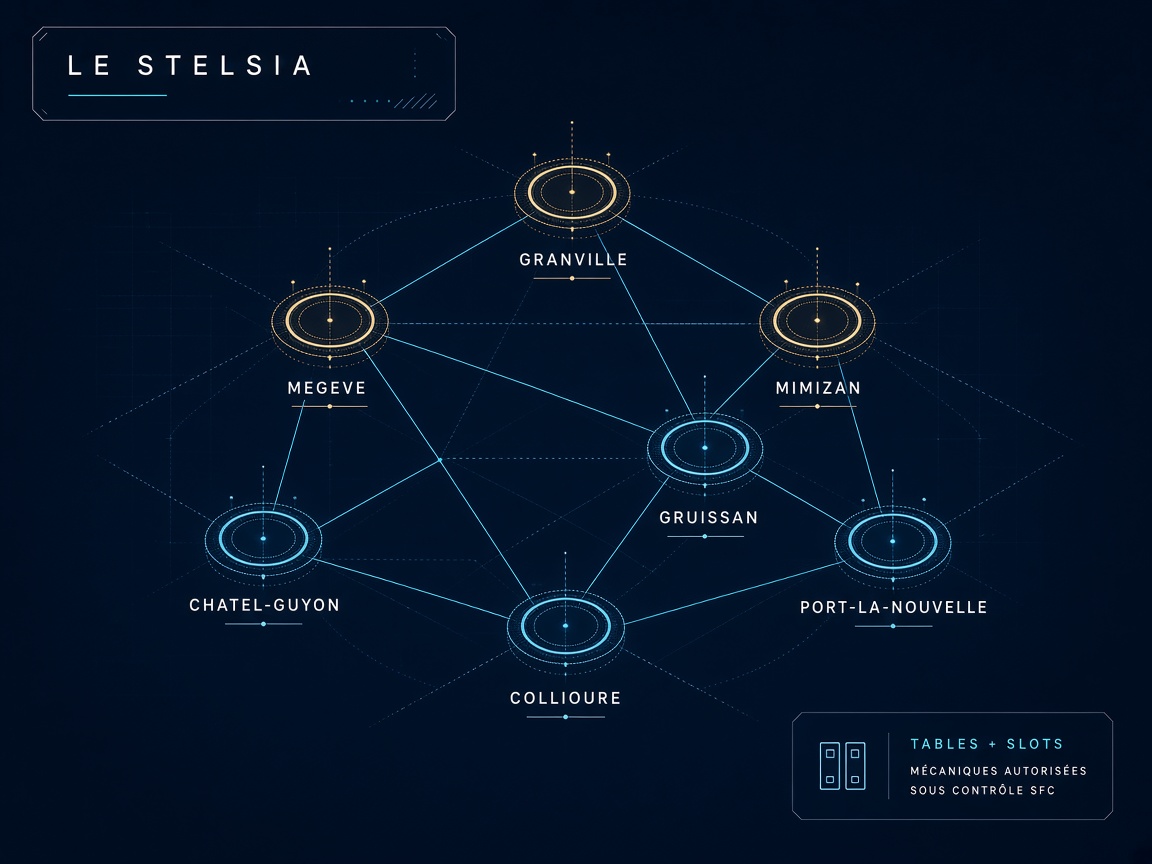
The seven houses are small to mid-size venues in regional and coastal towns, not Paris palaces. Table games and slot machines are the majority of the business. Hotels, restaurants and shows sit around the gaming floor. That is a local leisure operator. Merkur's 2024 book, more than 15,000 people and over €2 billion of revenue, is a manufacturing and multi-channel gaming group. The fit is a large operator taking a licensed French estate it can stock, systemise and hold.
SFC's own 2025–2026 outlook, published with the put option, is the scale of the listed slice. Management anticipates gross gaming revenue of about €22.5 million, net gaming revenue of about €13.3 million, net revenue after levies of €14.2 million, and EBITDA of about €3.5 million. Those are company estimates for the SFC Group, not a forecast for Casigrangi's three direct houses and not a purchase multiple. They tell you the listed vehicle is a regional cash engine, not a national champion.
French land-based casino M&A is already a theme on this series. Banijay Gaming's purchase of Groupe JOA pulled a larger French estate into a media-and-betting group. Cirsa's acquisition of Slots del Sol was a slots-route combination in a neighbouring market. Merkur is doing the German-operator version: buy the holding company, keep the licences, then tender the stub.
03 · Deal Intelligence
How the casino stack sits together
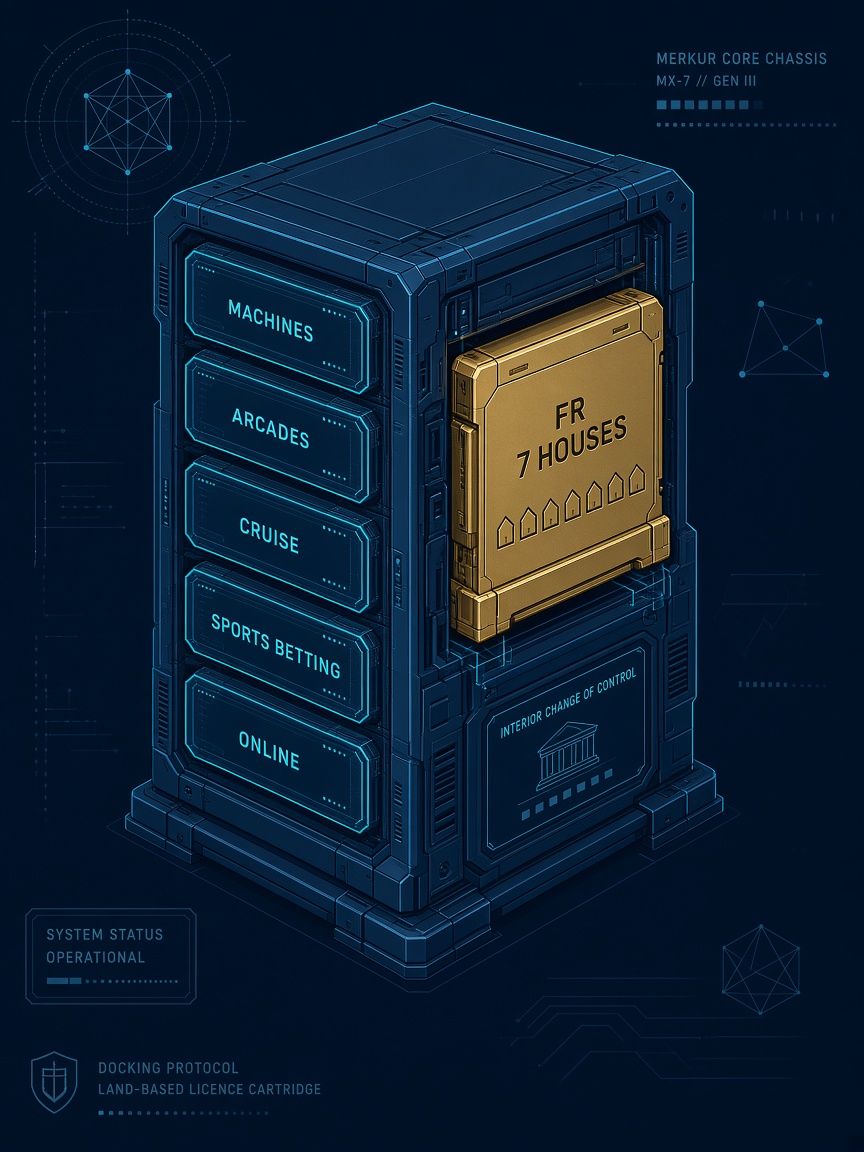
Merkur's public stack is machines, arcade systems, cash handling, land-based and cruise casinos, sports betting and online gaming. Casigrangi and SFC add licensed French table-and-slot floors with hospitality attached.
A French casino licence is a floor, a game mix and a local operating file, not a software module. Each of the seven houses is authorised for table games and slot machines. The majority of the business, on both companies' descriptions, is those games. Hospitality, food, entertainment and shows are the adjacent rooms. Merkur already designs and distributes gaming machines and cash-management systems. Putting those products into floors it owns is a different job from selling them to a third-party concessionaire.
The Merkur perimeter already includes arcades, casinos on land and on cruise ships, sports betting and online gaming. The French estate is land-based. Nothing in the announcement says the seven houses will be wired into Merkur's online or betting rails on close. Continuity of the licensed floors is the first operating requirement. Machine supply, systems and cash handling are the second. A later online overlay would be a separate regulatory conversation in France, not a closing condition in this SPA.
Connecting the two is an estate and licence problem before it is a platform problem. Interior approval under Article L. 323-3 is a change-of-control test on the people who run the games, not a software integration milestone. Internal reorganisation steps sit in the same condition list. Until those clear, the seven clocks keep running under Casigrangi and SFC as they do today.
Capability map
| Capability | Merkur before | Casigrangi / SFC add | Together |
|---|---|---|---|
| Floors | Arcades, casinos, cruise casinos | Seven licensed French houses | A French land-based estate inside the group |
| Games | Machine design and distribution | Tables and slots as the majority of the business | Supply into floors Merkur owns |
| Geography | Pan-European operator, Germany HQ | Seven named French towns | Licensed French presence, not a new continent |
| Corporate form | Private group under the Gauselmann Family Foundation | Listed SFC plus a private holding company | 95% of Casigrangi now, tender for the SFC stub later |
| Adjacent | Sports betting and online gaming | Hospitality, food, entertainment | Leisure rooms around licensed floors |
Before
Casigrangi holds 81.21% of listed SFC. Merkur is a German operator without this French estate.
Seven small and mid-size casinos run as Le Stelsia under two corporate wrappers.
→
After
Merkur owns 95% of Casigrangi, subject to Interior. DOFA keeps 5% on a put and call.
Remaining SFC holders are offered €6.19 in cash. Squeeze-out and delisting only if the thresholds are met.
04 · Deal Intelligence
Where Merkur can take the French estate
Distribution here is seven named French towns, not a new continent. Merkur brings a pan-European operator and a machine-manufacturing bench. The licences stay French.
The named map is short on purpose. Granville, Megève, Mimizan, Châtel-Guyon, Collioure, Gruissan and Port-la-Nouvelle. Coastal and alpine leisure towns. Merkur does not need a guessed national heatmap. It needs those seven files to remain in force after the Interior review, and it needs the hospitality rooms around the floors to keep trading while ownership moves.
What Merkur can add, if Interior agrees, is group purchasing, machine supply and operating systems it already sells elsewhere. What it cannot add by announcement is a new French online-casino licence. The 28 August release talks about strengthening and expanding Merkur's presence in France. The disclosed perimeter of this transaction is land-based casinos and the related leisure businesses.
A larger listed US casino combination on this series, Fertitta's agreement for Caesars, is a different scale of floor. The industrial rhyme is still operator-to-operator. Merkur is buying regional French licences it can hold. It is not buying a destination-resort brand.
05 · Deal Intelligence
How the combination could work
Close of the Casigrangi SPA is targeted for Q1 2027 after Interior approval. The simplified tender at €6.19 is then filed in H1 2027. Squeeze-out and a Euronext delisting follow only if the legal thresholds are met.
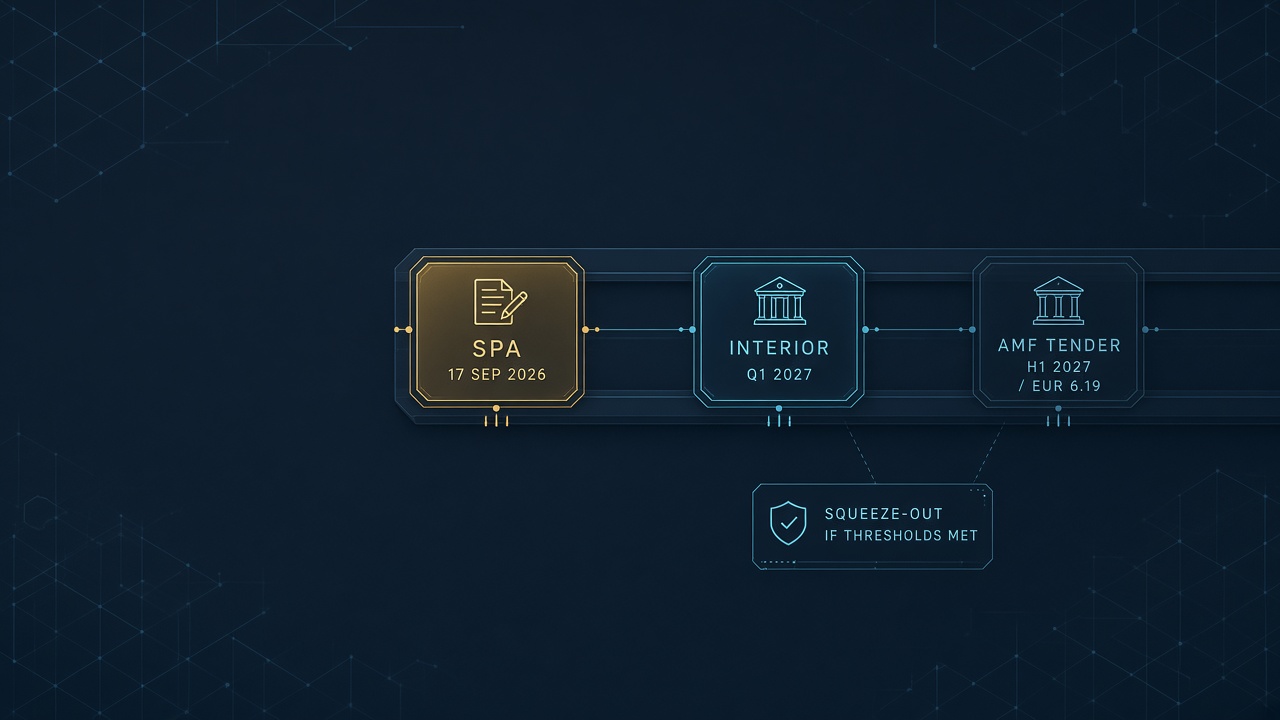
| Interior approval | French Ministry of Interior clearance under Article L. 323-3, the live condition on the Casigrangi SPA. |
|---|---|
| Q1 2027 close | 95% of Casigrangi transfers, with DOFA's 5% remaining on the published put and call. |
| AMF tender | Simplified offer at €6.19 filed in H1 2027 and opened on the AMF timetable. |
| Squeeze-out test | Thresholds met or not at the end of the offer; delisting is an intention, not a first-step condition. |
The practical sequence is Interior, internal reorganisation, pay for 95% of Casigrangi, then the AMF timetable. The Autorité des marchés financiers opened a pre-offer period on 28 August 2026 under notice 226C1409. Filing of the simplified tender is expected in the first half of 2027 if the SPA completes. The offer opens after AMF clearance, on a timetable the AMF will publish. Merkur currently intends to request a squeeze-out and to delist SFC if the conditions are met at the close of that offer.
Working, in this case, is unromantic. The seven houses keep their tables and slots running. DOFA's 5% stub in Casigrangi sits on the published put and call. The independent expert's report lands before SFC shareholders have to decide on the €6.19 cash. A delisting is an intention, not a closing condition of the first step.
Acquiry view. Merkur is buying control of a licensed French casino estate the way French takeover law actually works: take the holding company that already owns 81.21% of the listed vehicle, then offer the same cash price to everyone else. €6.19 is a disclosed listed-share price with a very large premium to the summer tape. It is not a published enterprise value for Casigrangi.
The best companies are acquired, not sold. Seven small and mid-size French casinos inside a machine-and-operator group that already reports more than €2 billion of revenue is that kind of asset. If Interior clears the change of control, Merkur will have paid for a French floor it can stock and hold. The later tender is how the stub gets the same number.
Reference
Frequently asked questions
Who is buying Société Française de Casinos?
Merkur Spielbanken Beteiligungs GmbH, a subsidiary of MERKUR.COM AG, which is fully owned by the Gauselmann Family Foundation. The first step is 95% of Casigrangi, the holding company that already owns 81.21% of SFC.
How much is Merkur paying?
The companies published a transparency price of €6.19 in cash per SFC share, and said the later simplified tender will be at the same price. They did not publish an enterprise value or a euro total for 95% of Casigrangi. Applying €6.19 to 5,092,470 SFC shares is about €31.5 million of listed equity, an Acquiry arithmetic check, not the Casigrangi cheque.
When could the deal close?
The Casigrangi share transfer is targeted for the first quarter of 2027, subject to Ministry of Interior approval and internal reorganisation. The simplified tender would then be filed in the first half of 2027.
What casinos are in the perimeter?
Seven licensed houses. Casigrangi operates Granville, Megève and Mimizan. SFC operates Châtel-Guyon, Collioure, Gruissan and Port-la-Nouvelle. All seven are authorised for table games and slot machines.
Does Merkur buy 100% of SFC on signing?
No. The 17 September agreement is 95% of Casigrangi. Remaining SFC shareholders are meant to receive a later cash offer at €6.19. A squeeze-out and delisting are stated as Merkur's intention if the legal conditions are met after that offer.
What still has to clear?
French Ministry of Interior approval under Article L. 323-3 of the Code de la sécurité intérieure, internal reorganisation steps, then AMF clearance of the simplified tender. Casino de Gruissan's works council already gave a positive opinion on 2 September 2026.
Keep reading
Related analysis
Deal Intelligence · Gaming
Gaming1 Acquires Pac-Man NV: Full Ownership of Belgian Operator Carousel
Gaming1 acquired 100% of Pac-Man NV, the company behind Belgian online casino operator Carousel / Carousel Group. The long-standing partnership since 2012 becomes full ownership, with Pac-Man NV's Belgian licence and digital portfolio integrated immediately and no employees transferred.
Deal Intelligence · Gaming
BetMGM acquires online casino rights for The Traitors
BetMGM's exclusive online casino rights partnership with All3Media International turns The Traitors into a planned multi-title iGaming franchise. The first title is live across six named U.S. and Canadian regions inside BetMGM Casino and Borgata Online.
Deal Intelligence · Gaming
Barry Diller Drops Bid to Acquire MGM Resorts: 'We Didn't Feel the Mix Was Coming Together'
People Incorporated withdrew its proposal to purchase the remaining public shares of MGM Resorts International. Barry Diller cited a mix that was not coming together. People keeps about 27% of MGM while the board commits to a standalone strategy.
Explore the sector:Gaming acquisitions
About the analyst

Joash Boyton
Founder and Managing Director, Acquiry · Melbourne, Australia · Global coverage
Joash Boyton is the Founder and Managing Director of Acquiry, a specialist M&A advisory firm focused on the acquisition and sale of businesses. He executes buy-side and sell-side mandates from USD $1M to $500M across technology, SaaS, fintech, payments, gaming, blockchain and emerging verticals, and is not limited to them. Any sector, any market.