Overview
Electronic Arts is no longer a public company. On 4 August 2026, EA announced that its acquisition by a consortium of PIF, Silver Lake and Affinity Partners had closed. Stockholders receive $210 in cash for each share, EA common stock has stopped trading and the shares will be delisted from NASDAQ.
The parties put the enterprise value at approximately $55 billion and called it the largest all-cash sponsor take-private in history. The deal was announced on 29 September 2025, approved by stockholders on 22 December 2025 and completed a little over ten months after signing. Andrew Wilson remains Chairman and CEO.
The transaction
The $210 offer was a 25% premium to EA's unaffected close of $168.32 on 25 September 2025, and above its unaffected all-time high of $179.01 on 14 August 2025. The consortium acquires 100% of EA, which stays headquartered in Redwood City, California.
| Term | Detail |
|---|---|
| Buyer | Consortium of PIF, Silver Lake and Affinity Partners |
| Target | Electronic Arts Inc. (formerly NASDAQ: EA) |
| Structure | Take-private, 100% acquisition |
| Enterprise value | Approximately US$55 billion |
| Consideration | $210 a share in cash; PIF rolls its existing 9.9% stake |
| Announced | 29 September 2025 |
| Stockholder approval | 22 December 2025 |
| Completed | 4 August 2026 |
| Status | Completed |
At signing, EA expected the deal to close in the first quarter of its fiscal 2027, which runs April to June 2026. It closed a few weeks after that window. For a transaction of this size involving a sovereign wealth fund, a short overrun is ordinary. It isn't a sign of trouble.
How the deal is financed
The agreement release disclosed three parts of the financing. They are parts of one price, so they shouldn't be added together as if they were separate amounts of capital.
| Component | Disclosed amount | Detail |
|---|---|---|
| Equity | ~$36bn | Cash from PIF, Silver Lake and Affinity, plus the rollover of PIF's existing 9.9% stake |
| Debt committed | $20bn | Fully and solely committed by JPMorgan Chase Bank, N.A. |
| Debt funded at close | $18bn (expected) | Portion of the $20bn commitment expected to be drawn at closing |
Each consortium member said it would fund its equity entirely from capital under its own control. That matters for a deal this size. No equity syndication process can stall the deal, and once regulators and stockholders approved it, very little financing risk remained.
Equity of about $36 billion against expected drawn debt of $18 billion means the buyout is roughly two-thirds equity. That's conservative for an LBO and reflects how much cash PIF brought. Even so, $18 billion of debt is about 2.4 times EA's fiscal 2026 net revenue, and the business will have to service it every year.
What the consortium bought
EA develops and publishes games and live services across consoles, PC and mobile. The completion release reports fiscal 2026 GAAP net revenue of about $7.5 billion, from a portfolio that spans sports, live-service shooters, life simulation and racing.
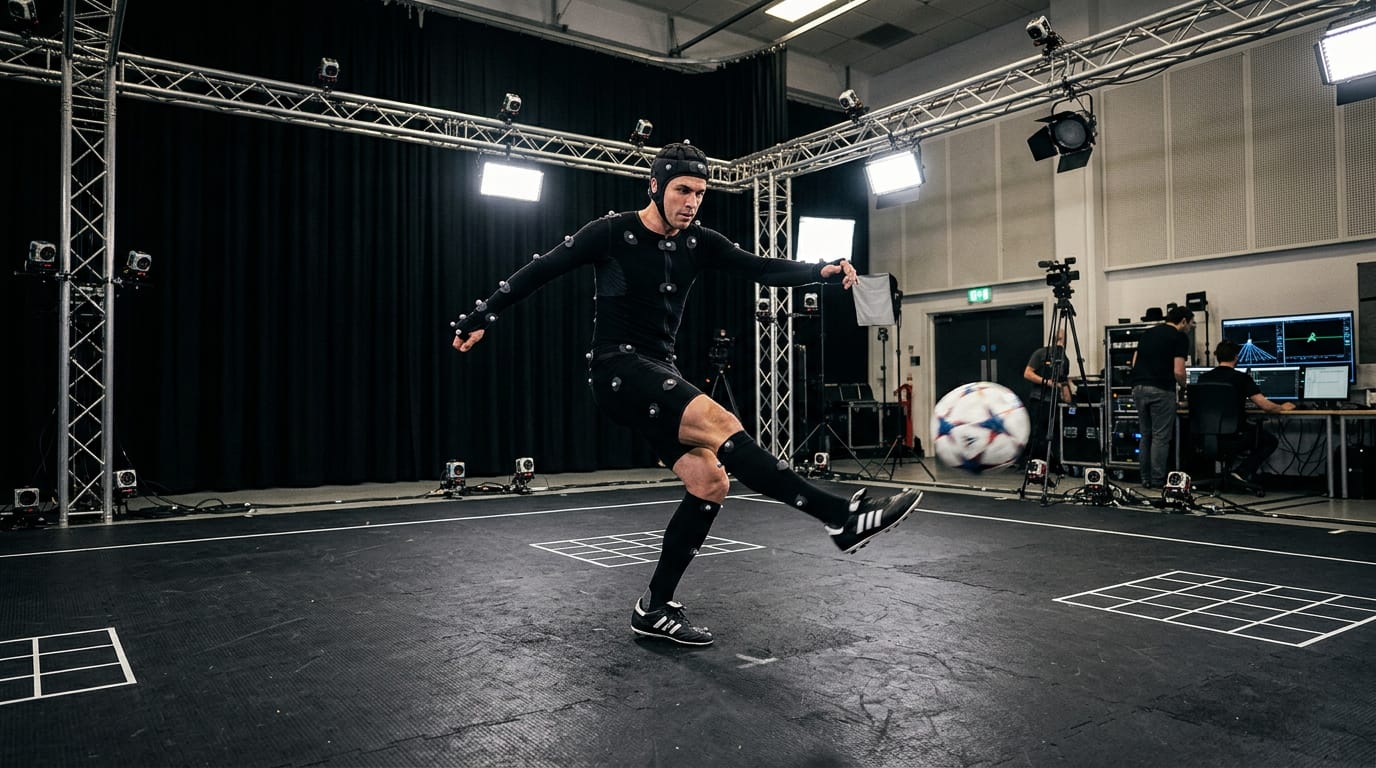
The attraction for long-term capital is the mix of durable franchises and recurring revenue. Annual sports releases and live services built around in-game content behave more like subscriptions than hit-driven launches. Few gaming assets at this scale ever come up for sale, which is why a premium was paid.
In an employee note, Our Next Chapter, Wilson presents private ownership as a new chapter. He names Cam Weber (President and Chief Studios Officer) and David Tinson (President and COO) as key partners. Keeping that leadership team together is part of the investment case.
Why the consortium bought
Each member of the consortium brings something different.
- PIF had been a minority investor in EA for more than five years and already knew its sports and gaming franchises. Gaming is a stated priority for Saudi Arabia's sovereign fund.
- Silver Lake brings experience investing in large technology companies and has said it will invest heavily in EA's growth, including in AI for game development.
- Affinity Partners adds flexible growth capital to the equity.
For public stockholders, the deal locked in value at a 25% premium. Certain cash was their reason to say yes. For the buyers, the reasons were control and a longer time horizon: they can fund multi-year franchise investment and new technology without a share price passing judgement every quarter.
| Date | Milestone | Detail |
|---|---|---|
| 29 Sep 2025 | Definitive agreement | ~$55bn EV; $210 a share; PIF rolls its 9.9% stake |
| 22 Dec 2025 | Stockholder approval | Approved at a special meeting of stockholders |
| 4 Aug 2026 | Completion | EA private; delisting from NASDAQ; Wilson continues as CEO |
Running the numbers
The disclosed figures support a few simple checks. The calculator below starts from EA's own numbers. Change any of them to see how the premium and the debt load move.
Test the EA take-private on your own assumptions
Defaults are the figures in EA's agreement and completion releases.
Not investment advice. Outputs are arithmetic on disclosed figures. EA has not published earnings-based valuation multiples for the deal, and Acquiry does not estimate them.
On the defaults, the offer is a 24.8% premium, which EA rounded to 25%. It is also about 17% above the unaffected all-time high. Debt makes up about a third of the funding. The structure is less a highly leveraged buyout and more a sovereign-backed equity deal with a large loan alongside it.
Acquiry's read
The freedom case
Private ownership can let EA invest in studios, live services and new entertainment formats over longer periods than a public company could easily justify to shareholders. Wilson staying on and the emphasis on studio leadership support that reading.
The discipline case
A take-private this large still has to service its debt and deliver returns to its owners. That can mean sharper decisions about which franchises to back, tighter cash management and less patience for experiments that don't work. The $18 billion expected to be drawn at close is the reminder that this freedom comes at a cost.
What it means for gaming M&A
Large-scale gaming IP is scarce. When sovereign and private capital can back tens of billions against long-lived franchises, staying listed becomes a choice rather than a given. For buyers and sellers of gaming assets, EA is now a valuation reference point. It shows that scarce IP still sells when the buyers have enough capital and the management team stays.
What to watch
- Release cadence across the sports and live-service franchises.
- Debt levels relative to earnings as EA pays down the buyout debt.
- Culture: whether the creative culture Wilson describes survives the change of ownership.
Those will show whether the freedom case or the discipline case wins. We don't assume either. Acquiry runs buy-side and sell-side mandates in gaming and interactive entertainment, and in any sector or market beyond it.
Frequently asked questions
Who bought Electronic Arts?
A consortium of PIF (Saudi Arabia's Public Investment Fund), Silver Lake and Affinity Partners acquired 100% of EA.
How much was the EA take-private worth?
The deal valued EA at an enterprise value of approximately $55 billion, with stockholders receiving $210 in cash per share. The parties described it as the largest all-cash sponsor take-private in history.
When did the EA deal close?
It was announced on 29 September 2025, approved by stockholders on 22 December 2025 and completed on 4 August 2026. EA stock has been delisted from NASDAQ.
How was the EA buyout financed?
About $36 billion of equity, including PIF rolling its existing 9.9% stake, plus $20 billion of debt fully committed by JPMorgan, of which $18 billion was expected to be drawn at close.
What premium did EA stockholders receive?
The $210 offer was a 25% premium to EA's unaffected close of $168.32 on 25 September 2025, and above its unaffected all-time high of $179.01.
Who runs EA after the take-private?
Andrew Wilson remains Chairman and CEO. EA stays headquartered in Redwood City, California.
Sources
- 1
- 2
- 3
- 4
Joash Boyton is a technology sector analyst, publisher, and the founder of Acquiry, where he executes buy-side and sell-side M&A mandates across digital assets, software, and gaming technologies. He is the author of peer-reviewed corporate finance literature indexed across institutional repositories including Google Scholar and the ORCID Registry. Joash publishes Acquiry Deal Intelligence to deliver independent, forensic strategic reviews and valuation benchmarks of global technology acquisitions, compiling primary data directly from corporate disclosures, SEC filings, and regulatory ledgers.
Research support: Acquiry Deal Intelligence.